

Omnicom’s OMC growth is supported by post-Interpublic cross-selling opportunities, new business wins, expanding artificial intelligence (AI)-enabled capabilities and substantial shareholder returns. The combination is also creating a multi-year path to cost efficiencies and a more integrated operating model.
The company’s third-quarter 2026 earnings are expected to increase 19.6% year over year. Its 2026 earnings are projected to rise 21.4%, while revenues are anticipated to grow 49.6% during that period.
Factors That Bode Well for OMC’s Success
Post-Acquisitions Benefits & New Business Wins: Omnicom is leveraging its broader capabilities following the post-Interpublic acquisition capabilities to deepen existing client relationships and pursue larger, integrated mandates. In the second quarter of 2026, the company expanded services across sports, media, production, commerce, social and influencer marketing for clients including American Express, General Mills and Uber. It secured integrated media wins with Adidas, IBM and Subway. Management noted that expansion within existing accounts was a major contributor to organic growth during the quarter. Beyond revenue opportunities, the Interpublic combination also creates a multi-year path to cost efficiencies and earnings improvement through integration synergies and a more streamlined operating model.
Omnicom Group Inc. Revenue (TTM)
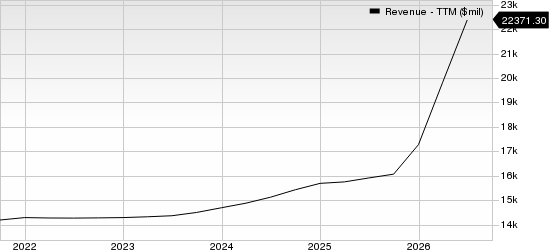
Omnicom Group Inc. revenue-ttm | Omnicom Group Inc. Quote
Data, AI & Connected Marketing Should Expand Capabilities: OMC is integrating Acxiom’s data and identity capabilities with its AI-driven Omni platform across media, commerce and marketing workflows. Management sees agentic marketing, connected commerce, sports and entertainment, social and creator marketing, and AI-driven discovery as key avenues for expanding client relationships. AI-enabled workflows are also improving efficiency, measurement and outcomes, while client savings are being reinvested into marketing activity.
Shareholder Returns Remain Strong: Omnicom repurchased about $3 billion of shares in the first half of 2026 and declared an 80-cent quarterly dividend in July. Shares outstanding fell to 274.3 million as of July 22. Management plans roughly $500 million of additional buybacks in 2026 and expects to complete the $5 billion authorization by the end of the first quarter of 2027.
Watch Out for These Risks to OMC Stock
Advertising Remains a Weak Spot: Omnicom’s Advertising organic revenues declined by high single digits in the second quarter of 2026 and accounted for 15.7% of Core Operations revenues, while Integrated Media and Experiential & Other each grew more than 10%. Management attributed the weakness mainly to post-Interpublic brand realignments, brand eliminations, internal restructuring and disposals of slower-growing businesses. Although the reorganization has progressed, management did not provide a timeline for a return to growth, making a recovery in Advertising important for broader, more balanced organic growth.
Debt & Integration Costs Remain Elevated: The Interpublic acquisition materially increased Omnicom’s cost base, debt and financing expense. In the second quarter of 2026, the company recorded $40.1 million of integration costs and $47 million of severance and repositioning expenses. Gross long-term debt stood at $10.2 billion at quarter-end, while net interest expense rose to $93 million from $41 million a year earlier. Management expects 2026 net interest expense to increase by about $200 million from the $167 million reported in 2025, mainly due to assumed Interpublic debt and refinancing activity.
OMC’s Zacks Rank & Stocks to Consider
Omnicom currently carries a Zacks Rank #3 (Hold) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
A couple of better-ranked stocks in the broader Business Services sector are Coherent Corp. COHR and CBIZ, Inc. CBZ
Coherent Corp. carries a Zacks Rank #2 (Buy) at present. It has a long-term earnings growth expectation of 52.5%.
COHR beat earnings estimates in three of the trailing four quarters and matched once, delivering an earnings surprise of 6.2%, on average.
CBIZ currently holds a Zacks Rank of 2. It has a long-term earnings growth expectation of 10%.
CBZ beat earnings estimates in three of the last four quarters and missed once, with an average earnings surprise of 8.9%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Omnicom Group Inc. (OMC): Free Stock Analysis Report
CBIZ, Inc. (CBZ): Free Stock Analysis Report
Coherent Corp. (COHR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).