

PepsiCo, Inc. PEP has reported better-than-expected third-quarter 2026 results, wherein earnings and revenues surpassed the Zacks Consensus Estimate and improved year over year. Results benefited from organic revenue growth, favorable foreign currency translation and contributions from acquisitions, net of divestitures.
PEP’s third-quarter core earnings per share (EPS) of $2.34 beat the Zacks Consensus Estimate of $2.29 and improved 2% year over year. The company’s core constant-currency EPS increased 1.5%. Foreign currency hurt EPS by 1%. Reported earnings rose 17% to $2.23 per share versus $1.90 in the year-ago quarter.
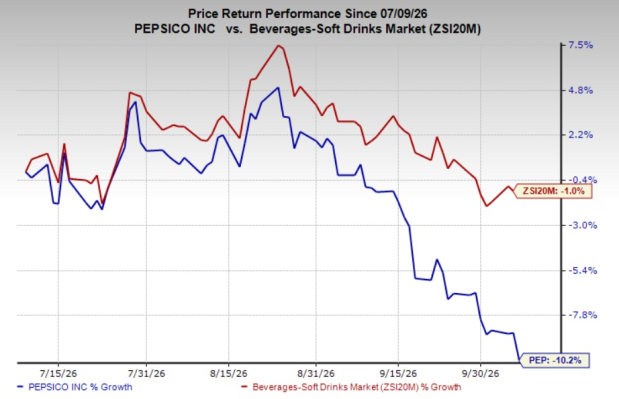
Shares of the Zacks Rank #4 (Sell) company have lost 10.2% in the past three months compared with the industry’s 1% decline.
Image Source: Zacks Investment Research
PEP's Q3 Revenue Performance
Net revenues increased 5.6% year over year to $25.27 billion and surpassed the Zacks Consensus Estimate of $24.88 billion. Organic revenues grew 3.1%, reflecting effective net pricing and contributions from organic volume growth. This marked the company's strongest organic revenue growth since the fourth quarter of 2023.
PepsiCo's reported revenue growth included a 1.7-percentage-point net benefit from acquisitions and divestitures, and a 0.7-percentage-point benefit from foreign exchange translation. International organic revenues advanced 8%, marking the 22nd consecutive quarter of at least mid-single-digit growth. Global beverages and convenient foods organic volumes increased 3% and 1%, respectively, supported by robust international performance.
Our model predicted year-over-year organic revenue growth of 2.5% for the third quarter, with a 2.1% gain from the price/mix and a 0.4% rise in volume.
PepsiCo, Inc. Price, Consensus and EPS Surprise
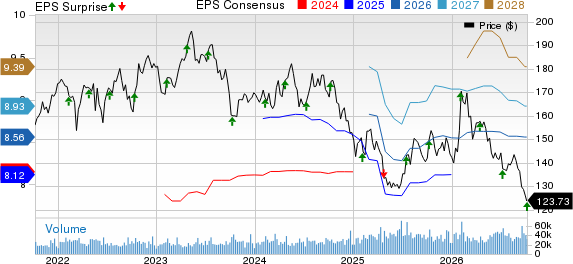
PepsiCo, Inc. price-consensus-eps-surprise-chart | PepsiCo, Inc. Quote
PepsiCo's Profitability Trends
On a consolidated basis, reported gross profit increased 7.3% year over year to $13.754 billion from $12.82 billion. The reported gross margin expanded 80 basis points (bps) to 54.4% from 53.6% in the year-ago quarter, reflecting stronger gross profit growth than revenues.
The core gross profit increased 6.5% year over year to $13.748 billion. The core gross margin rose 50 bps to 54.4%.
We anticipated the core gross margin to increase 30 bps year over year to 54.2% in the third quarter. In dollar terms, core gross profit was expected to improve 4.1%.
PepsiCo's reported operating profit increased 19% to $4.26 billion, while core operating profit advanced 3% to $4.28 billion. The reported operating margin expanded 195 bps to 16.9%, whereas the core operating margin contracted 35 bps.
Core operating profit benefited from productivity savings, effective net pricing and $178 million in tariff refunds. However, operating cost inflation, and increased advertising and marketing investments partly offset these gains.
Our model predicted core SG&A expenses of $9.1 billion, which indicated year-over-year growth of 4%. As a percentage of revenues, core SG&A expenses were anticipated to be 36.8%, suggesting a 20-bps rise from the prior-year quarter.
We expected a core operating margin of 17.4%, implying a 10-bps increase from the year-ago quarter’s actual.
PEP's North American Business Performance
PepsiCo Foods North America (PFNA) generated revenues of $6.5 billion, slightly below $6.53 billion in the year-ago quarter. Organic revenues declined marginally as lower effective net pricing offset volume gains. Organic volume benefited from improved performance in U.S. savory and salty snacks.
The segment's core operating margin contracted 280 bps, reflecting affordability investments, higher advertising spending and the comparison with a prior-year asset sale gain. Productivity savings and increased organic volume provided partial offsets.
PepsiCo Beverages North America (PBNA) reported revenues of $7.71 billion, up 5% year over year. Acquisitions primarily drove reported growth, while organic revenues declined slightly. Organic beverage volume fell 2%, although functional hydration and zero-sugar offerings performed well.
PepsiCo's International Segments Deliver Growth
International Beverages Franchise revenues increased 8% year over year to $1.4 billion, with organic revenues advancing 7%. Beverage volume grew 5%, supported by sustained demand across international markets.
Europe, Middle East and Africa generated revenues of $5.41 billion, up 8% year over year. Organic revenues grew 9%, supported by effective net pricing and beverage volume growth.
Latin America Foods' revenues climbed 14% year over year to $3.02 billion, while organic revenues advanced 6%. The segment registered 3% volume growth, reflecting continued demand across key markets.
Asia Pacific Foods delivered revenues of $1.23 billion, representing 10% year-over-year growth. Organic revenues increased 9%, supported by an 11% rise in organic volume, the strongest volume performance among PepsiCo's reported segments.
PEP's Financial Position & Cash Flow
PepsiCo ended third-quarter 2026 with cash and cash equivalents of $10.68 billion as of Sept. 5, 2026, compared with $9.16 billion at the end of 2025. Short-term debt obligations totaled $9.22 billion, while long-term debt stood at $42.66 billion.
Net cash provided by operating activities reached $7.95 billion as of the end of third-quarter 2026 compared with $5.47 billion in the year-ago period. Capital spending totaled $2.18 billion.
The company paid out cash dividends of $5.94 billion and repurchased shares worth $739 million in the year-to-date period.
PepsiCo Updates Its 2026 Outlook
PEP updated its outlook for 2026. PepsiCo expects organic revenue growth of 3% for 2026 compared with the previously mentioned 2-4%. Reported net revenue growth is projected at 6% versus the earlier stated 4-6%.
The company lowered its core constant-currency earnings growth outlook to 1-2% from the previously mentioned low end of 4-6%. Core earnings growth is projected at 2.5-3.5% compared with the earlier stated low end of 5-7%.
Management expects continued North American margin pressure in the fourth quarter. PepsiCo anticipates a core effective tax rate of 21% and capital spending below 5% of revenues.
The company maintained its shareholder cash-return target of $8.9 billion, comprising $7.9 billion in dividends and $1 billion in share repurchases.
Don’t Miss These Better-Ranked Stocks
Diageo Plc DEO is a global beverage alcohol company that produces, distills, brews, bottles, packages and distributes spirits, wine and beer. The company currently flaunts a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for DEO’s fiscal 2027 sales implies a decline of 3.1% and the same for earnings suggests 2.1% growth from the previous year’s reported numbers.
The Coca-Cola Company KO is the world's largest non-alcoholic beverage company, marketing a broad portfolio of sparkling soft drinks, water, juice, coffee, tea and sports beverages. It currently carries a Zacks Rank #2 (Buy).
The Zacks Consensus Estimate for Coca-Cola’s 2026 sales and earnings indicates growth of 4% and 9.7%, respectively, from the prior-year reported levels. KO delivered a trailing four-quarter earnings surprise of 4.6%, on average.
Mondelez International Inc. MDLZ is a global snack food company that owns a broad portfolio of brands, including Oreo, Cadbury, Toblerone, Ritz and LU. MDLZ carries a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Mondelez’s 2026 sales and earnings implies increases of 3.7% and 4.5%, respectively, from the prior-year reported levels. MDLZ delivered a trailing four-quarter earnings surprise of 5.8%, on average.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
PepsiCo, Inc. (PEP): Free Stock Analysis Report
CocaCola Company (The) (KO): Free Stock Analysis Report
Diageo plc (DEO): Free Stock Analysis Report
Mondelez International, Inc. (MDLZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).