

Delta Air Lines, Inc. DAL emphasized pricing strength, resilient travel demand and disciplined capacity management during its third-quarter 2026 earnings call. Management maintained that stronger revenues and diversified income streams are helping offset sharply elevated fuel expenses.
Executives also addressed persistent nonfuel cost pressures, operational investments and the sustainability of higher fares. Their outlook points to continued revenue momentum, although fuel volatility remains a major consideration for 2027 profitability.
Delta Sees Revenue Momentum Continuing Into Q4
Chief commercial officer Joe Esposito said broad-based demand and stronger yields supported third-quarter revenue growth of 16% on essentially flat capacity.
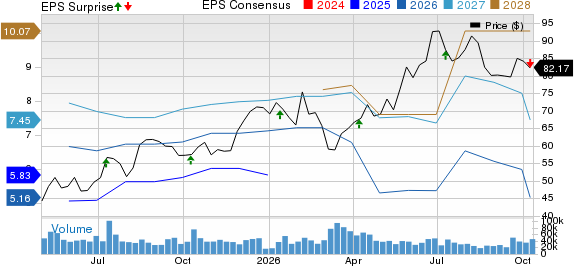
Adjusted revenues reached $17.59 billion, below the Zacks Consensus Estimate of $17.74 billion. Adjusted earnings of $1.72 per share missed the consensus estimate of $1.8.
Delta Air Lines, Inc. Price, Consensus and EPS Surprise
Delta Air Lines, Inc. price-consensus-eps-surprise-chart | Delta Air Lines, Inc. Quote
Esposito expects fourth-quarter revenue growth of approximately 20% on 3% higher capacity. During the analyst discussion, he noted that more than 60% of fourth-quarter bookings were already secured, with strong early booking trends extending into 2027.
DAL Faces Elevated Fuel Costs Despite Strong Pricing
Chief executive officer Ed Bastian emphasized that Delta's diversified business model has strengthened its ability to withstand substantial fuel inflation.
Management expects approximately $4.5 billion in full-year pretax profits despite a projected $6 billion increase in annual fuel expenses. Fourth-quarter earnings are projected between $1.15 and $1.65 per share, with operating margins of 7% to 9%.
Chief financial officer Erik Snell indicated that fourth-quarter fuel costs could reach $4.25 per gallon, including a refinery benefit of approximately 40 cents. Management expects full-year earnings between $5.1 and $5.6 per share.
Delta's Nonfuel Costs Remain Under Scrutiny
Snell acknowledged that nonfuel unit costs increased 7.3% year over year, reflecting higher crew expenses, revenue-related costs and operational disruptions.
Responding to a Bank of America analyst's concerns about cost inflation, Snell explained that operational investments and restrained capacity growth were deliberate decisions intended to support reliability and profitability.
Management expects fourth-quarter nonfuel unit cost growth to improve sequentially by 1 to 2 percentage points. Snell reiterated expectations for low-single-digit growth in 2027 as operational efficiencies improve and earlier investments enter the comparison base.
DAL's Premium and Loyalty Businesses Support Growth
Esposito highlighted continued strength in premium travel, with premium revenues increasing 18% year over year. Diversified revenue streams represented 61% of total revenues.
Loyalty revenues also grew 18%, supported by stronger cardholder engagement and spending. American Express remuneration increased 15%, positioning full-year payments to exceed $9 billion.
During questioning from JPMorgan, Bastian expressed reluctance to partially monetize SkyMiles. He emphasized maintaining direct customer relationships and expanding loyalty through partnerships, including Hyatt, rather than introducing outside financial investors.
Delta Maintains Discipline on Capacity Expansion
Bastian reiterated that capacity decisions will prioritize margins rather than market-share growth, particularly while fuel prices remain elevated.
In response to a Citigroup analyst, he indicated that 2027 capacity plans would depend on fuel prices, economic conditions and demand. International markets could account for a greater proportion of expansion.
Esposito also described improving domestic competitive conditions as airlines reduce unprofitable capacity. He noted that domestic unit revenues increased 16%, while Main Cabin unit revenues continued their sequential improvement.
DAL Targets Cash Generation and Debt Reduction
Snell emphasized balance-sheet strengthening alongside continued investment in the airline's operations and customer experience.
Delta generated $463 million in third-quarter free cash flow and expects approximately $2.5 billion for 2026. Management plans to repay more than $2 billion in debt this year.
The company targets year-end gross leverage of approximately 2.2 times. Its longer-term framework includes mid-teens margins and returns, supported by fleet modernization, operational improvements and higher-value revenue streams.
Delta Focuses on Sustainable Profitability
Management's overarching message centered on preserving pricing gains while improving efficiency and operational reliability.
Bastian maintained that higher fares could remain sustainable after fuel prices moderate. However, he acknowledged that the timing and extent of fuel-price normalization remain critical to future margin expansion.
What DAL's Zacks Rank and Style Scores Indicate
DAL currently carries a Zacks Rank #5 (Strong Sell), indicating an unfavorable earnings-estimate revision outlook. Its Value and Growth Score of B each reflects relatively attractive characteristics in those categories. However, the Momentum Score of F indicates weak price momentum, while the VGM Score of C reflects a mixed overall style profile. Favorable individual scores do not override the caution associated with the current Zacks Rank.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Rank can change as analysts revise earnings estimates following the latest results, making subsequent estimate revisions important to monitor.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Delta Air Lines, Inc. (DAL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).