

Accenture plc ACN offers investors a clear trade-off. Enterprise AI demand, recurring services and cash generation support the growth case, while uneven discretionary spending, pricing pressure and a heavier acquisition program raise execution risk.
The valuation is lower than several key benchmarks, but fiscal 2026 organic growth was about 3%. The question is whether AI-led demand can lift underlying growth enough to justify a more aggressive stance.
Accenture’s Valuation Looks Discounted to Key Benchmarks
ACN trades at 14.4X forward 12-month earnings, below the Zacks sub-industry at 18.6X, the broader Zacks sector at 20.7X and the S&P 500 at 19.8X. The gap gives investors a valuation cushion if operating momentum improves.
Image Source: Zacks Investment Research
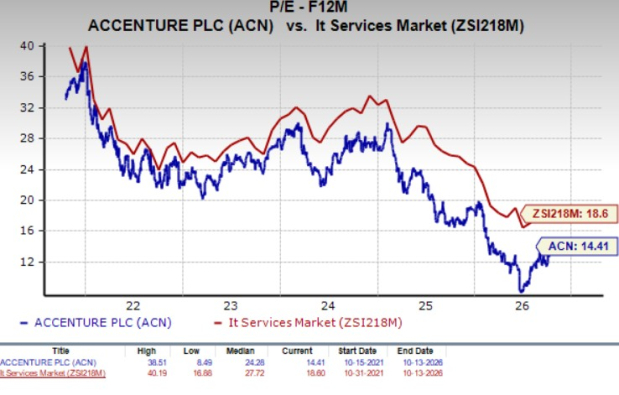
Image Source: Zacks Investment Research
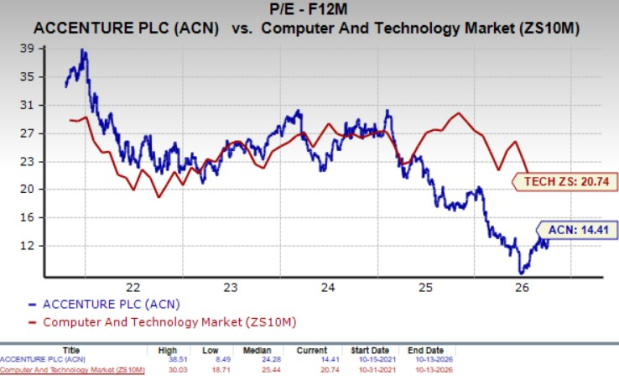
Image Source: Zacks Investment Research
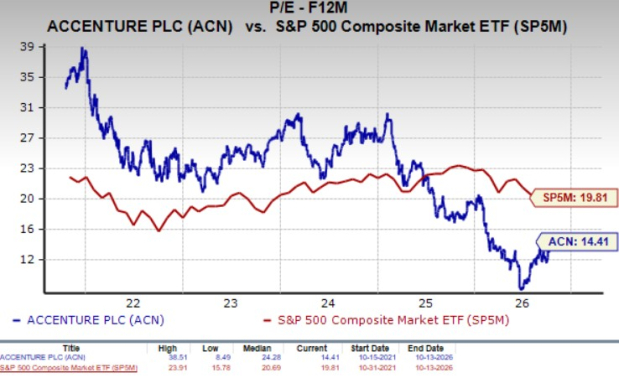
The stock also trades well below its five-year median of 24.3X. That discount is meaningful, but valuation alone does not resolve concerns around organic growth, pricing and the contribution required from acquisitions.
ACN’s AI Growth Supports the Bull Case
More than 400 clients initiated advanced AI work with Accenture in fiscal 2026, including nearly 100 in the fourth quarter. The company ended the year with nearly 110,000 AI and data professionals. Bookings from eight emerging AI and data partners more than tripled from fiscal 2025, while related revenues more than doubled.
International Business Machines Corporation IBM is also pushing enterprise AI deeper into consulting through large-scale deployment and modernization work. Cognizant Technology Solutions Corporation CTSH is expanding enterprise AI services around agentic systems and major cloud platforms. Their activity reinforces the competitive race to turn AI spending into consulting and managed-services revenue.
Accenture’s M&A Push Raises Execution Costs
Accenture deployed $4.9 billion across 17 acquisitions in fiscal 2026. For fiscal 2027, it expects about $8 billion of acquisition investment, including roughly $3 billion tied to Cyber OT transactions that shifted into the new fiscal year and approximately $5 billion of additional planned investment.
The financing burden is rising with that strategy. A $5 billion bond offering completed in July 2026 is expected to add roughly $250 million of interest expense in fiscal 2027, while lower average cash balances are expected to reduce interest income by about $100 million. Successful integration and stronger organic growth therefore matter more.
ACN’s Cash Flow Balances Growth and Shareholder Returns
Fiscal 2026 free cash flow reached $11.62 billion, up from $10.87 billion a year earlier. Accenture returned a record $11.5 billion to shareholders, including $7.5 billion in share repurchases and $4.0 billion in dividends.
Management expects fiscal 2027 free cash flow of $11.0-$11.8 billion and plans to return at least $9.5 billion to shareholders. That cash generation provides room to fund acquisitions while continuing dividends and repurchases, although the capital demands are substantial.
Accenture’s Signals Favor Patience Over Aggression
Accenture has attractive AI exposure, a discounted earnings multiple and substantial free cash flow. Still, fiscal 2027 revenue growth of 3%-6% in local currency includes an expected 2%-2.5% contribution from acquisitions, while management continues to plan for intense competition and uneven discretionary spending.
ACN currently carries a Zacks Rank #3 (Hold), which supports a wait-and-watch approach rather than an aggressive buy case. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
ACN’s VGM Score of A and Momentum Score of A are favorable, while its Value Score of B and Growth Score of B are also constructive. The Style Scores add useful context, but they are designed to complement the Zacks Rank rather than override it.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Accenture PLC (ACN): Free Stock Analysis Report
International Business Machines Corporation (IBM): Free Stock Analysis Report
Cognizant Technology Solutions Corporation (CTSH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).