

Philip Morris International Inc. PM is likely to register growth in both top and bottom lines when it reports third-quarter 2026 earnings on Oct. 21. The Zacks Consensus Estimate for revenues is pegged at $11.42 billion, implying a 5.3% increase from the prior-year quarter’s reported figure.
The consensus mark for quarterly earnings has moved up a penny in the past seven days to $2.31 per share, indicating an increase of 3.1% from the figure reported in the year-ago quarter. Philip Morris delivered a trailing four-quarter average earnings surprise of 6%.
Philip Morris International Inc. Price, Consensus and EPS Surprise
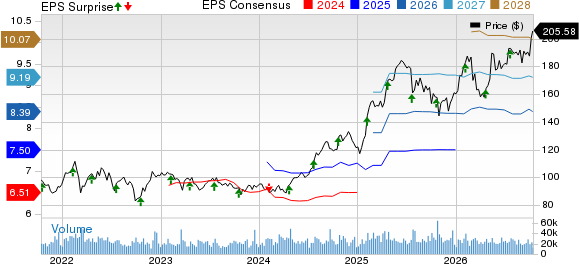
Philip Morris International Inc. price-consensus-eps-surprise-chart | Philip Morris International Inc. Quote
Things to Know About PM’s Upcoming Results
Philip Morris is likely to have benefited from continued momentum in its smoke-free business in the third quarter. Growing demand for IQOS heated tobacco products, supported by expanding consumer adoption and strong brand positioning across international markets, is likely to have driven performance. The company's focus on product innovation, portfolio expansion and effective commercial execution is also expected to have supported revenues.
Philip Morris’ smoke-free portfolio, comprising IQOS, ZYN and VEEV, is likely to have remained a key growth driver. Strong demand for VEEV e-vapor products across Europe and expanding international adoption of ZYN nicotine pouches might have supported category performance. In the United States, the rollout of ZYN ULTRA, additional nicotine strengths and flavors, alongside increased marketing and in-store initiatives, is likely to have strengthened consumer engagement.
Philip Morris' combustible tobacco business is likely to have benefited from strong pricing and resilient demand in certain international markets. The strength of Marlboro and disciplined pricing strategies might have supported revenues and profitability. Meanwhile, a favorable smoke-free product mix, manufacturing efficiencies and cost-saving initiatives are likely to have aided gross margins, although higher commercial investments and increased manufacturing costs might have partly offset these benefits.
Despite these positives, certain challenges might have weighed on quarterly performance. Excise-driven price increases in Japan and flavor restrictions in Europe likely affected IQOS volumes. Heightened U.S. nicotine pouch competition and tough ZYN shipment comparisons might have added pressure. Higher input costs, unfavorable geographic mix and currency headwinds might have constrained profitability.
Earnings Whispers for PM Stock
Our proven model does not conclusively predict an earnings beat for Philip Morris this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
Philip Morris has an Earnings ESP of 0.00% and a Zacks Rank #3. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Some Stocks With a Favorable Combination
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
Lamb Weston Holdings, Inc. LW currently has an Earnings ESP of +2.25% and a Zacks Rank of 1. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Lamb Weston’s upcoming quarter’s earnings per share is pegged at 85 cents, implying a 23.2% increase from the year-ago period. The consensus mark for Lamb Weston’s quarterly revenues is pegged at $1.63 billion, which indicates an increase of 1% from the prior-year quarter. LW delivered a trailing four-quarter earnings surprise of 22.1%, on average.
e.l.f. Beauty, Inc. ELF currently has an Earnings ESP of +6.10% and a Zacks Rank of 1. The Zacks Consensus Estimate for e.l.f. Beauty’s upcoming quarter’s EPS is pegged at 59 cents, which implies a 13.2% decrease year over year.
The consensus estimate for e.l.f. Beauty’s quarterly revenues is pegged at $469.2 million, which calls for 36.4% growth from the figure reported in the prior-year quarter. ELF delivered a trailing four-quarter earnings surprise of nearly 61.5%, on average.
Sysco Corporation SYY currently has an Earnings ESP of +2.89% and a Zacks Rank of 2. The Zacks Consensus Estimate for Sysco’s upcoming quarter’s EPS is pegged at $1.16, which implies a 0.9% increase year over year.
The consensus estimate for Sysco’s quarterly revenues is pegged at $22.2 billion, which indicates a surge of around 5% from the figure reported in the prior-year quarter. SYY delivered a trailing four-quarter earnings surprise of 1%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Philip Morris International Inc. (PM): Free Stock Analysis Report
Sysco Corporation (SYY): Free Stock Analysis Report
e.l.f. Beauty (ELF): Free Stock Analysis Report
Lamb Weston (LW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).