

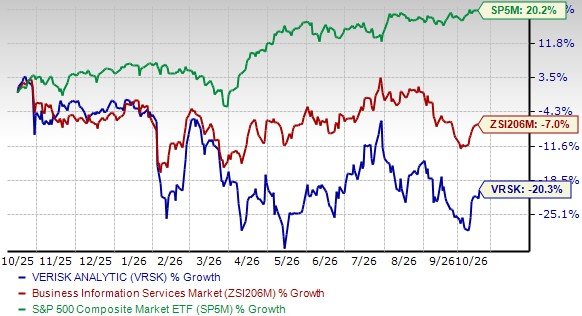
Verisk VRSK stock has declined 20.3% over the past year compared with the industry's 7% dip. The Zacks S&P 500 Composite has rallied 20.2% over the same period.
1-Year Share Price Performance
The Zacks Consensus Estimate for VRSK’s 2026 revenues is $3.2 billion, suggesting 5% year-over-year growth. For 2027, the metric is expected to gain 6.5% to $3.4 billion.
The consensus mark for 2026 earnings per share is pinned at $7.71, suggesting a 7.7% year-over-year jump. The bottom line is expected to increase 13.1% to $8.72 in 2027.
Factors That Augur Well for VRSK’s Success
Recurring Subscription Aids Growth Stability: VRSK’s subscription-backed business model improves revenue visibility and supports persistent growth. The company ended the second quarter of 2026 with subscription revenues rising 8% year over year on an organic constant currency (OCC) basis, subsequent to 9.3% growth in the year-ago quarter.
Verisk’s subscription revenues constituted 83% of the top line, lowering exposure to transactional volatility. The company’s growth across underwriting, catastrophe risk solutions and antifraud analytics is fueled by strong renewals, strong price realization and customer relationship enhancement. Recurring revenue growth trajectory should be sustained on the back of persistent product enhancement and client wins.
AI-Driven Growth Opportunities: Verisk’s AI investments strengthen its competitive position, creating monetization opportunities. XactAI, VRSK’s AI-driven claims automation solution, registered approximately 10X user growth, reaching nearly 7,000 licensees. Premium Audit AI gained momentum, supporting stronger subscription renewals through improved functionality.
VRSK’s Anthropic collaboration introduced AI-fuelled connectors for underwriting and claims, with a top-10 insurer adopting the technology. Customer engagement should improve as AI integration expands across insurance workflows, strengthening pricing power and creating opportunities for more subscriptions and licensing revenues.
Insurance Analytics’ Contribution to Organic Growth: Verisk ended the second quarter of 2026 with underwriting and claims revenues rising 5.6% and 6.1% year over year, respectively, on an OCC basis. The company onboarded eight Core Lines contributors and 10 excess and surplus data contributors during the first half of 2026. An expanding proprietary dataset and improved analytical skill set improve product differentiation, supporting customer wins and creating opportunities from cross-selling and top-line growth in the long run.
Risks Faced by Verisk
Sluggish Insurance Market: In the second quarter of 2026, Verisk’s transactional revenues declined 4.2% on an OCC basis, indicating lower property-related activity, fewer weather events and international travel disruptions. Transactional revenues contributed 17% of the top line during the aforementioned quarter. Management anticipates a soft commercial property market and weather-related transactional weakness to persist through the second half of 2026, disrupting revenue growth.
Rising Operating Costs & Interest Expenses: The company’s selling, general and administrative expenses gained 20.8% year over year during the second quarter of 2026, driven by acquisition, disposition and AccuLynx-related costs, alongside higher consulting and employee-related expenses. Net interest expenses climbed to $53 million from the year-ago quarter’s $36 million, while the effective tax rate increased to 24.6% from 22.7%. It subsequently hurt net income, which declined 10% year over year.
Uncertain AI Monetization: Verisk shoulders execution and monetization risks as insurers rapidly adopt AI and develop proprietary analytical capabilities. Despite rising demand for AI-driven solutions, management identifies incremental AI revenue contribution as tough to quantify. Customer adoption cycles drag out and changing monetization models could curb revenue visibility.
VRSK’s Zacks Rank & Stocks to Consider
The company currently carries a Zacks Rank #3 (Hold).
Better-ranked stocks in the broader Zacks Business Services sector include Figure Technology Solutions FIGR and Ralliant Corporation RAL. These two companies presently flaunt a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Figure Technology Solutions has a long-term earnings growth expectation of 56.6%. FIGR delivered a trailing four-quarter earnings surprise of 28.2%, on average.
Ralliant has a long-term earnings growth expectation of 9.4%. RAL delivered a trailing four-quarter earnings surprise of 7.1%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Verisk Analytics, Inc. (VRSK): Free Stock Analysis Report
Ralliant Corporation (RAL): Free Stock Analysis Report
Figure Technology Solutions, Inc. (FIGR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).