

Philip Morris International Inc. PM reported third-quarter 2026 results, wherein both top and bottom lines beat the Zacks Consensus Estimate and increased year over year.
PM posted quarterly adjusted earnings of $2.36 per share, which increased 5.4% year over year. Excluding currency effects, the adjusted earnings jumped 5.8% year over year. The bottom line beat the Zacks Consensus Estimate of $2.30.
Philip Morris International Inc. Price, Consensus and EPS Surprise
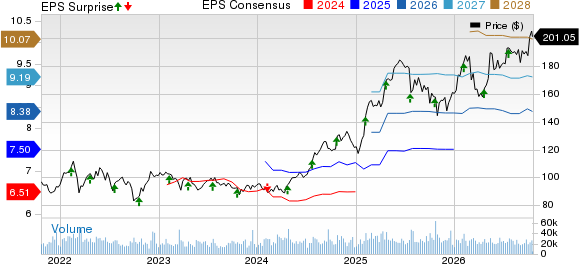
Philip Morris International Inc. price-consensus-eps-surprise-chart | Philip Morris International Inc. Quote
Net revenues of $11,438 million increased 5.5% on a reported basis and 7.1% organically year over year. Revenues beat the Zacks Consensus Estimate of $11,409 million. Growth was driven by favorable combustible pricing and smoke-free product demand. Total shipment volumes increased 0.6% to 206.2 billion units.
PM’s Quarterly Performance: Key Metrics and Insights
Adjusted gross profit increased 6.7% (up 8.3% organically) to $7,860 million. Adjusted gross profit margin expanded 80 basis points to 68.7%, supported by favorable combustible pricing, scale benefits and the smoke-free product mix.
Adjusted operating income rose 9.6% to $5,117 million, while adjusted operating margin expanded 160 basis points to 44.7%.
Decoding PM’s Segment Performance
Net revenues in the International Smoke-Free segment increased 0.7% (up 3.4% organically) to $3,867 million, reflecting favorable volume/mix from higher heated tobacco unit (“HTU”) and e-vapor volumes, alongside favorable HTU pricing. Adjusted gross profit increased 0.8% (up 3.3% organically) to $2,705 million. Shipment volumes grew 2.7% to 44.5 billion units, supported by growth in Taiwan, Global Travel Retail, Greece, Germany and Bulgaria. HTU shipments increased 1.5% to 41.5 billion units, while HTU adjusted in-market sales rose 7.1%. VEEV e-vapor shipments surged 61.6%, reflecting continued geographic expansion.
Net revenues in the International Combustibles segment increased 6.5% (up 7.8% organically) to $6,725 million. Growth reflected favorable pricing and the restructuring of distribution terms in certain markets, partly offset by an unfavorable geographic mix. Adjusted gross profit increased 8.6% (up 9.8% organically) to $4,610 million. Cigarette shipment volumes remained broadly flat at 158 billion units. Higher shipments in Turkey, Indonesia and Egypt offset declines in Russia, Poland and Japan. The segment benefited from 8.9% pricing growth, while elevated energy-related input costs remained a headwind. Marlboro's cigarette category share increased 50 basis points to a record 11.4%.
Net revenues in the U.S. segment jumped 22.7% to $845 million, driven by higher ZYN shipments, favorable pricing comparisons against prior-year promotions and contributions from the Wellness and cigar businesses. Adjusted gross profit increased 23.9% to $544 million, with organic growth of 23.8%. Total segment shipment volumes increased 2.3% to 3.7 billion equivalent units. ZYN shipments grew 4.2% to 3.2 billion pouches. Adjusted operating companies income increased 1.5% organically to $171 million, reflecting higher marketing investments. Management plans additional investments in the fourth quarter to support ZYN portfolio expansion and the transition to 20-pouch cans.
Philip Morris: Other Updates
The company ended the quarter with cash and cash equivalents of $6,683 million, long-term debt of $41,709 million and a total shareholder deficit of $5,945 million.
Philip Morris also raised its quarterly dividend 8.8% to $1.60 per share.
Sneak Peek Into PM’s Outlook
For 2026, Philip Morris now expects adjusted earnings of $8.29-$8.44 per share, indicating growth of 9.9-11.9%. Earlier, the metric was expected in the $8.26-$8.41 per share range, implying 9.5-11.5% growth. Excluding currency, adjusted earnings are projected at $8.11-$8.26 per share, implying an increase of 7.5-9.5%. Reported earnings per share are expected in the $7.11-$7.26 range. Earlier, the metric was expected in the $7.19-$7.34 per share range.
For 2026, PM still expects net revenues to increase 5-7% on an organic basis. The operating income on an organic basis is likely to rise 7-9%.
Management now expects total cigarette and smoke-free product shipment volumes to grow in 2026, compared with its previous forecast of broadly stable to slightly growing volumes. Smoke-free shipments are expected to increase at a high-single-digit rate, while cigarette volumes are projected to decline at a rate similar to the year-to-date trend.
Management still expects an operating cash flow of around $13.5 billion in 2026. Capital expenditures are likely to be in the band of $1.4 billion to $1.6 billion, primarily implying investments to support the smoke-free business.
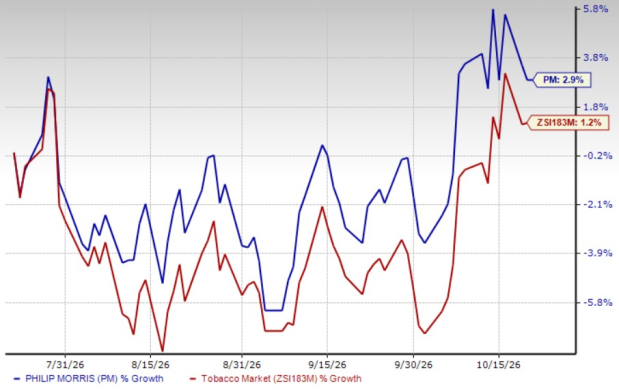
Shares of this Zacks Rank #3 (Hold) company have gained 2.9% in the past three months compared with the industry’s growth of 1.2%.
Image Source: Zacks Investment Research
Stocks to Consider
The Chefs' Warehouse, Inc. CHEF distributes specialty food and center-of-the-plate products in the United States, the Middle East and Canada. At present, CHEF carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The consensus estimate for Chefs' Warehouse’s current fiscal-year sales and earnings implies growth of 10.8% and 34.2%, respectively, from the year-ago reported figures. Chefs' Warehouse delivered a trailing four-quarter earnings surprise of 30.4%, on average.
Mama's Creations, Inc. MAMA manufactures and markets fresh deli-prepared foods in the United States. At present, MAMA holds a Zacks Rank of 2. Mama's Creations delivered a trailing four-quarter earnings surprise of 121.7%, on average.
The consensus estimate for Mama's Creations’ current fiscal-year sales and earnings implies growth of 30.3% and 66.7%, respectively, from the year-ago figures.
Lamb Weston Holdings, Inc. LW engages in the production, distribution and marketing of frozen potato products in the United States, Canada, Mexico and internationally. LW presently carries a Zacks Rank of 2. Lamb Weston delivered a trailing four-quarter earnings surprise of 22.1%, on average.
The Zacks Consensus Estimate for Lamb Weston’s current fiscal-year earnings indicates growth of 7.6% from the year-ago numbers.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Philip Morris International Inc. (PM): Free Stock Analysis Report
The Chefs' Warehouse, Inc. (CHEF): Free Stock Analysis Report
Lamb Weston (LW): Free Stock Analysis Report
Mama's Creations, Inc. (MAMA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).