

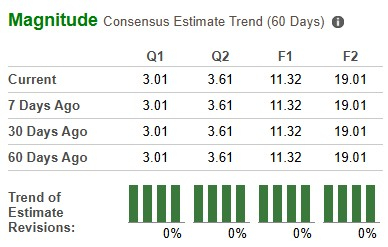
Celestica, Inc. CLS is scheduled to report third-quarter 2026 earnings on Oct 26. The Zacks Consensus Estimate for sales and earnings is pegged at $5.4 billion and $3.01 per share, respectively. Earnings estimates for CLS have remained unchanged over the past 60 days.
Image Source: Zacks Investment Research
Earnings Surprise History
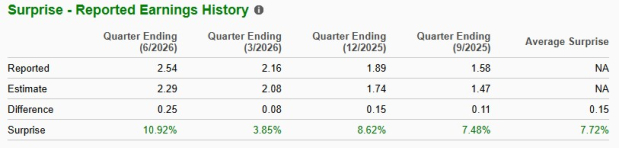
This leading electronics manufacturing services firm has had a solid earnings surprise history in the trailing four quarters, exceeding earnings expectations on most occasions. It delivered a four-quarter earnings surprise of 7.7%, on average.
Image Source: Zacks Investment Research
Earnings Whispers
Our proven model does not predict an earnings beat for Celestica for the third quarter. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the chances of an earnings beat. That is not the case here.
You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Celestica currently has an ESP of 0.00% and a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Shaping the Upcoming Results
Celestica is expected to benefit from continued investments in AI infrastructure, hyperscale customers expand data center capacity. The company’s Connectivity & Cloud Solutions (CCS) segment is likely to remain the primary growth driver, supported by demand for networking equipment, AI computing platforms, servers and storage systems.
Networking demand is expected to receive additional support from the continued ramp-up of 800G Ethernet switches and the beginning of mass production for 1.6-terabit (1.6T) networking programs with two hyperscaler customers. Celestica also expects its established 400G programs to maintain momentum. For the third quarter, management anticipates approximately 60% growth in communications revenue, reflecting sustained investments in high-performance data center connectivity.
The enterprise business is another important contributor. Continued growth in hyperscaler AI and machine-learning computing programs, alongside improving demand for storage solutions is set to drive growth.
However, the Electronics - Manufacturing Services industry is highly competitive. Celestica faces stiff competition from industry giants like Foxconn, Jabil, Flex Ltd. and Sanmina Corporation. Several smaller companies operating at a regional level also intensify competition. The highly cyclical nature of several sub sectors also remain a concern.
Price Performance
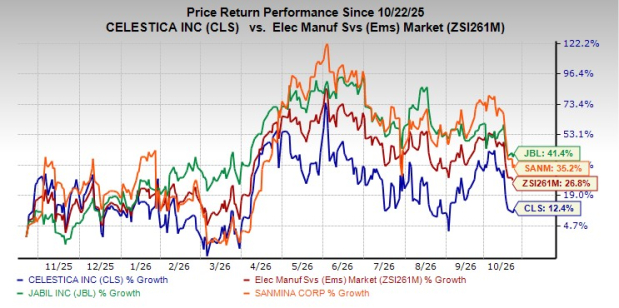
Over the past year, CLS has gained 12.4% compared with the industry’s growth of 26.8%. It has underperformed its peers like Jabil Inc. JBL and Sanmina Corporation SANM over this period. Sanmina has gained 35.2%, and Jabil is up 41.4% over this period.
Image Source: Zacks Investment Research
Key Valuation Metric
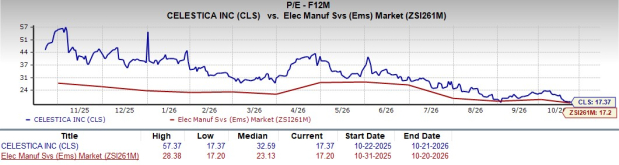
From a valuation standpoint, Celestica appears to be trading at a premium relative to the industry and is trading above its mean. Going by the price/earnings ratio, the company’s shares currently trade at 17.37 forward earnings, higher than 17.2 for the industry but lower than the stock’s mean of 32.59.
Image Source: Zacks Investment Research
Investment Considerations
The ongoing expansion of AI infrastructure provides Celestica with a significant growth opportunity. Its exposure to high-speed networking, AI computing and storage platforms positions the company to benefit from rising data center investment. The transition toward higher-speed networking, including 800G and 1.6T solutions, could provide additional avenues for growth as hyperscalers upgrade their infrastructure.
However, investors should also consider the execution challenges associated with this rapid expansion. Celestica is investing heavily in additional capacity, with full-year 2026 capital expenditures expected to be approximately $1 billion. Its ability to manage component availability, production schedules and working capital will be crucial to maintaining profitability and generating cash flow. Customer concentration is another consideration: three customers each accounted for at least 10% of total revenue in the second quarter, making results sensitive to spending decisions by major customers.
End Note
Celestica's third-quarter results are expected to reflect continued demand for AI infrastructure, expanding high-speed networking programs and improving contributions from ATS. The company's raised full-year outlook and expectations for accelerated revenue growth in 2027 provide a positive longer-term backdrop. Nevertheless, investors should assess whether strong sales growth is accompanied by sustained margin expansion and healthy cash generation. CLS maintains a balanced outlook, with existing investors advised to hold their positions while prospective investors may consider waiting for a more attractive entry point.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Celestica, Inc. (CLS): Free Stock Analysis Report
Jabil, Inc. (JBL): Free Stock Analysis Report
Sanmina Corporation (SANM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).