

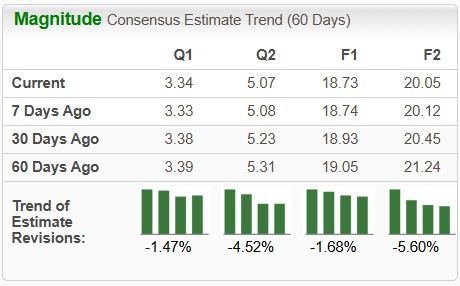
Leading global insurer Aon plc AON is set to report third-quarter 2026 results on Oct. 28, before the opening bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at $3.34 per share on revenues of $4.08 billion.
The third-quarter earnings estimate has witnessed two upward revisions and six downward movements over the past 60 days. The bottom-line projection indicates a year-over-year increase of 9.5%. The Zacks Consensus Estimate for revenues suggests year-over-year growth of 2%.
Image Source: Zacks Investment Research
AON beat the consensus estimate for earnings in each of the last four quarters, with the average surprise being 2.7%.
Aon plc Price and EPS Surprise
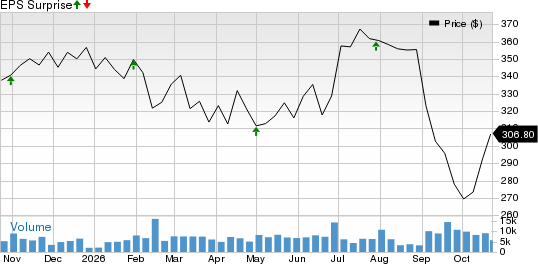
Aon plc price-eps-surprise | Aon plc Quote
Q3 Earnings Whispers for AON
Our proven model does not conclusively predict an earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the odds of an earnings beat. That’s not the case here.
AON currently has an Earnings ESP of -0.80% and a Zacks Rank #4 (Sell). You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
You can see the complete list of today’s Zacks #1 Rank stocks here.
What’s Shaping AON’s Q3 Results?
The Zacks Consensus Estimate for the Commercial Risk Solutions’ revenues indicates 4.9% growth from $2 billion a year ago, whereas our model predicts a 3% increase. We expect the unit to have witnessed 5% organic revenue growth in the quarter.
The consensus mark for the Health Solutions’ third-quarter revenues suggests nearly 4.5% growth from the year-ago level, while our model estimate indicates an 8% increase. The segment is likely to have been supported by new business growth, strong retention rates and positive market impact.
The Zacks Consensus Estimate for Reinsurance Solutions' revenues indicates growth of 3.8% from $537 million recorded a year ago, while our model estimate suggests a 5% increase. Favorable retention rates, new business generation and facultative placement growth are expected to have benefited the unit.
The aforementioned factors might have contributed to the company's year-over-year growth, positioning it for an earnings beat. However, the positives are likely to have been partially offset by high expenses due to significant investments in priority areas for long-term growth.
Our model projects total operating expenses to exceed $3.2 billion in the third quarter, driven by higher information technology and other general expenses. Other general expenses are estimated at approximately $435 million.
The consensus estimate for third-quarter revenues in the Wealth Solutions segment suggests a 16.1% decrease from the previous year’s $540 million, whereas our model indicates an 18% decline. The unit is likely to have been affected by weaker advisory demand in the United States.
Stocks That Warrant a Look
While an earnings beat looks uncertain for AON, here are some companies from the broader Finance space that you may want to consider, as our model shows that these have the right combination of elements to post an earnings beat this time around:
Cincinnati Financial Corporation CINF has an Earnings ESP of +2.51% and a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Cincinnati Financial’s third-quarter 2026 earnings is pegged at $1.99 per share. Its earnings beat estimates in three of the past four quarters and missed once, delivering an average surprise of 11.8%. The Zacks Consensus Estimate for CINF's revenues is pegged at $3.03 billion, indicating a 5.5% increase from the year-ago reported figure.
Skyward Specialty Insurance Group, Inc. SKWD has an Earnings ESP of +7.55% and a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Skyward Specialty Insurance Group’s earnings for the to-be-reported quarter is pegged at $1.22 per share, indicating 16.2% year-over-year growth. The consensus estimate for revenues is pinned at $507.3 million. SKWD beat earnings estimates in each of the past four quarters, with the average surprise being 19.4%.
Palomar Holdings, Inc. PLMR has an Earnings ESP of +1.89% and a Zacks Rank #3 at present.
The Zacks Consensus Estimate for Palomar Holdings’ bottom line for the to-be-reported quarter is pegged at $2.64 per share, indicating 31.3% year-over-year growth. It beat earnings estimates in each of the past four quarters, with the average surprise being 13%. The consensus estimate for PLMR’s revenues is pegged at $376.5 million.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Aon plc (AON): Free Stock Analysis Report
Cincinnati Financial Corporation (CINF): Free Stock Analysis Report
Palomar Holdings, Inc. (PLMR): Free Stock Analysis Report
Skyward Specialty Insurance Group, Inc. (SKWD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).