

Planet Labs PBC PL shares have fallen 25.8% in the past month, sharpening the debate over whether the pullback is mostly volatility or reflects risks that could persist. The company still has meaningful demand support, particularly from defense and sovereign customers.
Image Source: Zacks Investment Research
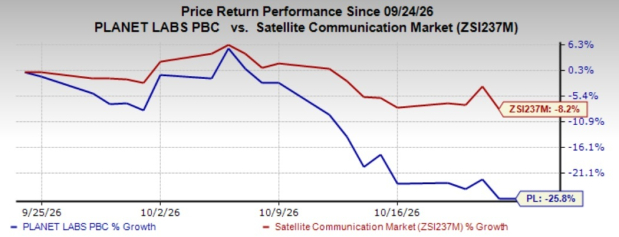
The near-term setup is less straightforward. Milestone-driven revenue timing, rising investment needs and a premium valuation leave less room for execution misses, even as Planet Labs continues to post rapid growth.
Planet Labs’ Growth Story Remains Intact
Defense and Intelligence revenues rose 93.3% year over year to nearly $81 million in second-quarter fiscal 2027. Backlog reached about $815 million, up roughly 11%, with around 50% applicable to the next 12 months. Management estimated that existing backlog could generate more than $400 million in revenues over the next four quarters, excluding new business and renewals.
Planet Labs is not alone in pursuing rising demand for space-based intelligence. BlackSky Technology Inc. BKSY recently won a pilot contract with a new international intelligence customer for its Gen-3 imagery services, while Satellogic Inc. SATL secured a one-year defense contract valued at more than $18 million for persistent Earth observation imagery. Those wins underscore an active market for sovereign and defense-focused geospatial capabilities.
PL Faces a Near-Term Revenue Step-Down
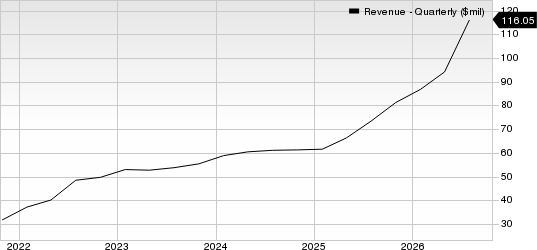
Planet Labs’ record second-quarter revenues of $116.1 million benefited from the handover of a satellite to the Swedish Armed Forces. That milestone moved revenues into the second quarter from the third quarter, making sequential comparisons unusually sensitive to delivery timing.
Planet Labs PBC Revenue (Quarterly)
Planet Labs PBC revenue-quarterly | Planet Labs PBC Quote
For third-quarter fiscal 2027, Planet Labs expects revenues of $101-$105 million. The midpoint implies a sequential decline from the second quarter, while adjusted EBITDA is expected to range from a loss of $6 million to a loss of $1 million. The timing effect does not erase demand, but it can make quarterly results uneven.
Planet Labs Is Spending Heavily to Scale
Planet Labs expects fiscal 2027 capital expenditures of $100-$115 million after spending about $29 million in the second quarter. Management plans to direct investment toward manufacturing expansion, supply-chain resiliency and next-generation satellite fleets.
Non-GAAP gross margin slipped to 59% from 61% a year earlier as the company invested in satellite services and AI-enabled partner solutions. First-half free cash flow also fell to $21.3 million from $54.3 million, showing how a heavier investment cycle can pressure cash generation even as revenues expand.
PL’s Valuation Leaves Less Room for Missteps
PL trades at 8.8X forward 12-month sales, compared with 2.6X for the Zacks sub-industry. The premium reflects substantial growth expectations and makes execution particularly important when revenue recognition depends on satellite milestones.
Image Source: Zacks Investment Research
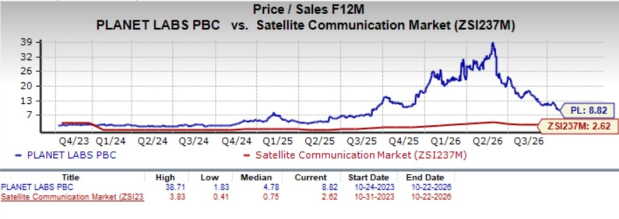
Planet Labs has a sizable growth opportunity, but a premium multiple gives investors less cushion if operating progress falls short of expectations.
PL’s Signals Point to Patience After the Selloff
Defense demand, backlog and recurring contracts support the longer-term story, while quarterly revenue timing, investment intensity and valuation remain near-term considerations.
PL currently carries a Zacks Rank #3 (Hold), with a Momentum Score of A, Growth Score of B, Value Score of F and VGM Score of C. The favorable Momentum and Growth Scores point to strengths in those styles, while the weak Value Score highlights valuation concerns. With the Zacks Rank at #3, the combined signals support a measured stance rather than treating the pullback alone as an obvious entry point.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Planet Labs PBC (PL): Free Stock Analysis Report
BlackSky Technology Inc. (BKSY): Free Stock Analysis Report
Satellogic Inc. (SATL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).