

UiPath PATH and AppLovin Corporation APP are two prominent players leveraging artificial intelligence to transform digital operations. UiPath leads the robotic process automation sector, applying AI to streamline enterprise workflows.AppLovin, on the other hand, operates in the mobile ad tech space, using AI to optimize app monetization and user acquisition.
As AI becomes an integral part of modern business software, the key question is: Which of these AI-driven tech stocks presents a more compelling investment opportunity today? Let’s examine their fundamentals, growth drivers and valuations.
The Case for UiPath
UiPath's transition from traditional robotic process automation to intelligent enterprise automation is creating additional revenue opportunities. Its Maestro orchestration platform integrates AI agents, software robots, business applications and human intervention, enabling organizations to manage complex workflows efficiently.
The company's growing AI adoption is evident from its second-quarter fiscal 2027 performance, when 18 of its 20 largest deals incorporated AI-related solutions. This development highlights increasing enterprise demand for integrated automation platforms capable of handling sophisticated business processes.
UiPath is also expanding its presence across financial services, healthcare, manufacturing and government organizations. Its automation solutions address financial compliance, invoice processing, healthcare claims and software testing, broadening its addressable market.
The integration of WorkFusion's specialized AI solutions and an expanded partnership with Cognizant further enhance its capabilities. These initiatives should support customer acquisition, deeper enterprise penetration and long-term revenue growth.
UiPath's improving financial performance strengthens confidence in its growth strategy. Second-quarter fiscal 2027 revenues increased 13% year over year to $410 million, while annual recurring revenues climbed 12% to $1.94 billion.
Non-GAAP operating income reached $89 million, representing a 22% margin, reflecting better expense management and operational efficiency. The company also recorded its fourth consecutive quarter of GAAP profitability.
Its balance sheet remains healthy, with approximately $1.4 billion in cash, cash equivalents and marketable securities and no debt. This financial flexibility supports investments in innovation, strategic initiatives and shareholder returns.
Additionally, increasing adoption among larger enterprises and improving customer retention should support recurring revenues and greater operating leverage.
The Case for APP
AppLovin's substantial presence in mobile gaming advertising has historically supported its expansion. However, its dominant market position could limit opportunities for additional market-share gains as the segment matures.
The company's second-quarter 2026 results highlight this emerging challenge. Although revenues surged 53% year over year to $1.92 billion, the number of advertising-driven installations declined 2%. Meanwhile, net revenue per installation increased 58%, reflecting improved monetization rather than higher installation volumes.
This divergence raises concerns about the sustainability of revenue growth if advertiser demand weakens. Rising customer acquisition costs could further pressure advertising budgets, particularly if gaming developers experience deteriorating returns on their marketing investments.
While enhanced monetization continues to support revenues, prolonged weakness in installation activity could eventually constrain expansion.
AppLovin's advertising platform relies heavily on improvements in its AI-powered recommendation models to enhance campaign effectiveness and attract higher advertiser spending.
However, the timing of these improvements remains unpredictable. During the second quarter, fewer significant model upgrades limited opportunities for additional growth. Although subsequent enhancements improved advertising performance, their delayed implementation highlights the company's dependence on technological execution.
This uneven development cycle could introduce greater volatility into quarterly results and complicate revenue forecasting.
Additionally, increasingly sophisticated AI models require substantial computing resources. Higher training and infrastructure expenses are expected to weigh on profitability, with the third-quarter adjusted EBITDA margin projected at approximately 83%.
Although this represents exceptional profitability, continued expense growth without corresponding advertising gains could restrict further margin expansion.
How Do Zacks Estimates Compare for PATH & APP?
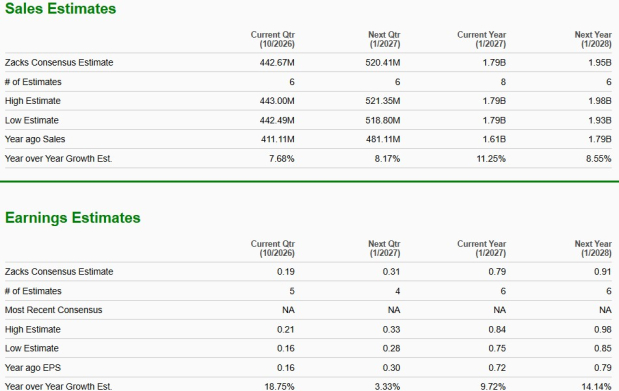
The Zacks Consensus Estimate for UiPath’s fiscal 2027 sales and EPS indicates year-over-year growth of 11.3% and 9.7%, respectively. EPS estimates have been trending flat over the past 60 days.
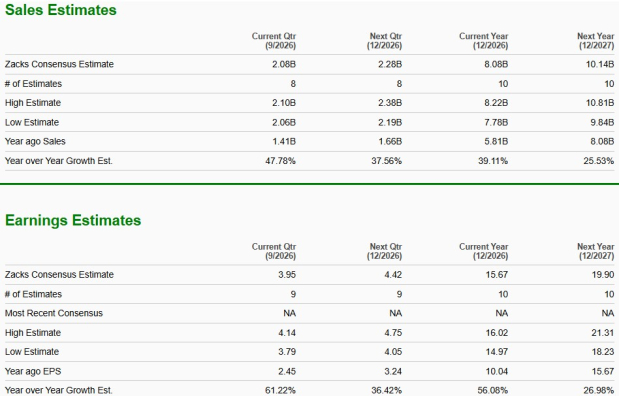
The Zacks Consensus Estimate for AppLovin’s 2026 sales and EPS indicates year-over-year growth of 39.1% and 56.1%, respectively. There have been two downward EPS revisions over the past 30 days with no upward revisions.
UiPath’s Valuation More Attractive Than AppLovin
UiPath is trading at a forward sales multiple of 3.67X, below its 12-month median of 5.47X. AppLovin’s forward sales multiple stands at 8.93X, below its median of 17.58X.
Why UiPath Appears to Be the Pick
UiPath appears to be the better investment choice, supported by its expanding AI-driven automation capabilities, growing enterprise adoption and improving profitability. Its Maestro platform, strategic partnerships and strong financial flexibility position it well to capitalize on rising demand for intelligent automation. Although AppLovin offers stronger growth prospects, concerns surrounding installation volumes, unpredictable AI model improvements and rising infrastructure costs could constrain its upside potential. Moreover, UiPath’s relatively attractive valuation provides an additional advantage.
While PATH carries a Zacks Rank #2 (Buy), APP has a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
UiPath, Inc. (PATH): Free Stock Analysis Report
AppLovin Corporation (APP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).