

PBF Energy Inc. PBF emphasized balance-sheet strengthening, operational reliability and margin-enhancing investments during its third-quarter 2026 earnings call. Tight global refined-product supplies supported elevated refining margins, while management outlined plans to improve profitability across market cycles.
The company reported earnings and revenues above the Zacks Consensus Estimate. Management also highlighted higher fourth-quarter throughput expectations, cost-reduction initiatives and increased financial flexibility following substantial debt repayments.
PBF Beat Q3 Earnings & Revenue Estimates
PBF reported third-quarter 2026 earnings of $12.38 per share, exceeding the Zacks Consensus Estimate of $11.34 per share. Quarterly revenues reached $12.13 billion, surpassing the Zacks Consensus Estimate of $10.8 billion.
PBF Energy Inc. Price, Consensus and EPS Surprise
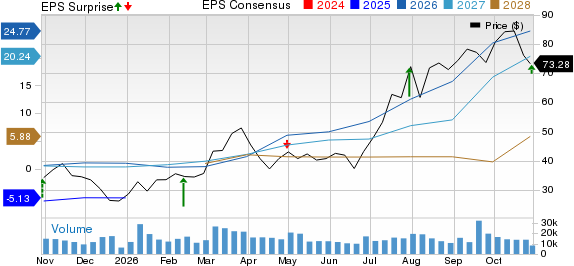
PBF Energy Inc. price-consensus-eps-surprise-chart | PBF Energy Inc. Quote
The results reflected favorable refining conditions amid constrained global product supplies. CFO Joseph Marino separately reported adjusted earnings of $12.78 per share, excluding special items, alongside adjusted EBITDA of approximately $2.3 billion.
PBF Energy Sees Sustained Refining Market Tightness
President and CEO Matthew Lucey emphasized that global refined-product shortages remain a major driver of refining margins. More than 5 million barrels per day of global refining capacity remains offline, while inventories are approximately 500 million barrels below pre-war levels.
Lucey noted that crude shipments through the Strait of Hormuz have recovered to roughly three-quarters of pre-war levels, although refined-product flows remain significantly constrained.
Management expects continued volatility and wider crude differentials. Lucey also emphasized that normalization of crude flows would not immediately restore damaged refining capacity or depleted inventories.
PBF Targets Higher Fourth-Quarter Throughput
Senior vice president and head of refining Michael Bukowski reported third-quarter throughput averaging approximately 924,000 barrels per day (bpd), consistent with management's expectations.
PBF anticipates fourth-quarter throughput of 925,000-985,000 bpd, supported by the completion of maintenance activities at Martinez and Paulsboro in October.
Bukowski also confirmed that previously idled processing units at Chalmette have returned to service. Management expects an uninterrupted operational schedule through year-end, enabling stronger production amid favorable product-market conditions.
PBF Energy Advances Cost & Yield Improvements
Bukowski highlighted progress under the Refining Business Improvement program, which has delivered more than $230 million in run-rate improvements included in 2026 plans. Management targets more than $350 million by year-end.
Capital savings are tracking approximately $88 million against the original $70 million commitment. Systemwide natural gas intensity has declined approximately 11% year-to-date.
At Chalmette, a project enables approximately 10,000 barrels per day of jet fuel production from higher-sulfur diesel. Management plans to double that capability in 2027 while pursuing additional gasoline-yield improvements at Paulsboro.
PBF Strengthens Its Balance Sheet
Marino reported approximately $2.5 billion in cash and $2.1 billion in total debt at quarter-end, leaving PBF with $426 million in net cash.
Following quarter-end, the company redeemed $800 million of senior notes, reducing gross debt to approximately $1.4 billion. Management expects refinancing and debt repayments to reduce annual interest expense by at least $130 million in 2027.
During questioning from Wolfe Research, Lucey defended maintaining permanent financing despite the stronger balance sheet. He emphasized preserving access to capital markets while reducing fixed interest obligations.
PBF Energy Highlights Crude Sourcing Advantages
During the analyst discussion, UBS questioned how widening heavy-crude discounts could benefit PBF's refining operations.
Lucey explained that the company's complex refining system can capitalize on discounted heavy feedstocks, particularly along the Gulf and East coasts. California operations also benefit from access to local crude through proprietary infrastructure.
Goldman Sachs questioned freight exposure. Lucey noted that approximately half the company's fleet operates under time charters, helping mitigate elevated shipping costs. Shorter transportation distances provide another advantage.
PBF Maintains Disciplined Capital Allocation
Management maintained 2026 capital expenditure guidance of $825 million-$875 million, excluding Martinez reconstruction spending.
Lucey emphasized smaller, higher-return investments rather than major refinery expansions. Management also acknowledged that 2027 will involve a heavier turnaround schedule, while 2028 is expected to be lighter.
PBF announced an 18% quarterly dividend increase. Management's priorities remain operational reliability, sustainable shareholder distributions and financial resilience across refining cycles.
PBF Energy's Zacks Rank & Style Scores
PBF currently sports a Zacks Rank #1 (Strong Buy), indicating favorable earnings estimate revisions and stronger near-term performance potential under the Zacks ranking methodology. You can see the complete list of today’s Zacks #1 Rank stocks here.
The company's Value Score of A indicates attractive valuation characteristics, while its Growth Score of A reflects favorable growth attributes. However, its Momentum Score of D indicates weaker price-momentum characteristics.
PBF also holds a VGM Score of A, reflecting a favorable combined assessment of Value, Growth and Momentum factors. The combination of a top Zacks Rank and a VGM Score of A aligns with the methodology's preferred screening characteristics. However, the Zacks Rank may change as analysts revise earnings estimates following the latest quarterly results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
PBF Energy Inc. (PBF): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).