

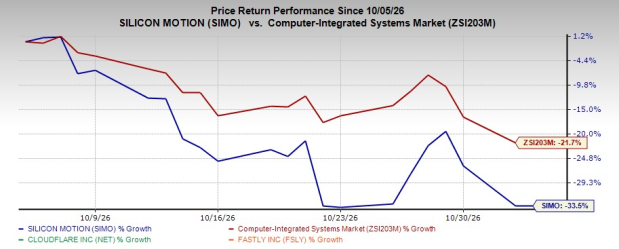
Silicon Motion Technology Corporation SIMO shares have fallen 33.5% over the past four weeks, a sharp reversal despite record revenues and expanding exposure to enterprise and AI storage. The drop raises the question of whether valuation now better reflects the company’s growth prospects.
Image Source: Zacks Investment Research
The answer is not straightforward. Enterprise diversification, automotive demand and higher-value storage products support the outlook, but consumer weakness, qualification requirements and supply-chain constraints leave execution risk elevated.
SIMO’s Record Growth Contrasts With the Sell-Off
Third-quarter 2026 revenues surged 131% year over year to about $560 million, marking a fourth consecutive quarter of record revenues. Non-GAAP earnings per ADS rose 335% to $4.35, while operating margin expanded to 32.1%.
The quarter also exceeded the Zacks Consensus Estimate on both the top and bottom lines. Management expects fourth-quarter revenues of $588-$616 million, with non-GAAP operating margin rising to 36%-37%.
Silicon Motion’s Enterprise Mix Is Expanding
Ferri automotive and enterprise boot-drive solutions grew more than 75% sequentially and represented more than 40% of third-quarter revenues. Management indicated that the solutions business could reach roughly half of revenues in 2027.
That shift increases exposure to longer-duration programs and higher-value storage opportunities. Micron Technology, Inc. MU, which offers DRAM, NAND and data-center SSDs, illustrates the broader memory and storage ecosystem in which enterprise demand is expanding.
SIMO Faces Persistent Consumer Pressure
Elevated NAND and DRAM prices are pressuring smartphone and PC affordability. eMMC and UFS controller revenues declined modestly sequentially in the third quarter, and management expects near-term revenues in that business to remain relatively flat.
SSD controller revenues are also expected to be flat to slightly lower sequentially in the fourth quarter. These trends show that enterprise growth is offsetting, rather than eliminating, weakness in established consumer-facing markets.
Silicon Motion Must Execute on Enterprise Ramps
Enterprise expansion depends on customer qualifications, production ramps and component availability. MonTitan is scaling across seven announced customers, while Silicon Motion’s 4-nanometer PCIe Gen6 MonTitan controller is scheduled to begin sampling in the first quarter of 2027.
Near-CPU boot-drive opportunities add another execution layer because customized firmware and customer-specific features are required. Seagate Technology Holdings PLC STX, whose portfolio includes cloud, edge and data-center storage products, provides another reference point for the scale and complexity of enterprise storage markets.
SIMO’s Valuation Adds Context to the Decline
SIMO trades at 12.1X forward 12-month earnings, below its five-year median of 19.4X but above the Zacks sub-industry’s 9.4X. The lower multiple versus its own history reflects a materially different valuation backdrop after the recent share-price pullback.
The discount to SIMO’s historical median may look more attractive if enterprise ramps progress as planned. Still, the premium to the sub-industry means investors are not being offered a uniformly cheap valuation relative to peers.
SIMO’s Signals Still Favor a Cautious View
SIMO’s growth and valuation setup remains mixed. Record operating performance and enterprise diversification support the longer-term case, while consumer pressure and execution requirements argue against treating the 33.5% decline alone as a buy signal.
The stock currently carries a Zacks Rank #3 (Hold). It has a Value Score of D and Momentum Score of D, along with a Growth Score of F and VGM Score of F. Since the Style Scores are designed to complement the Zacks Rank, these weaker grades support a measured stance despite the company’s strong recent fundamental growth. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Silicon Motion Technology Corporation (SIMO): Free Stock Analysis Report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
Micron Technology, Inc. (MU): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).