

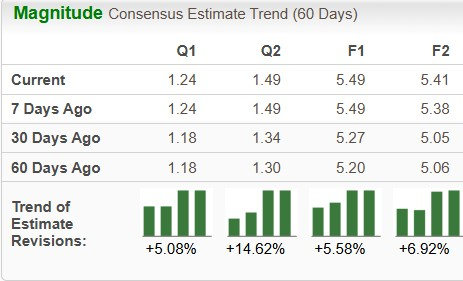
Devon Energy Corporation DVN is scheduled to release its third-quarter 2026 results on Nov. 5, after market close. The Zacks Consensus Estimate for earnings is currently pegged at $1.24 per share on revenues of $7.33 billion.
Third-quarter earnings estimates have increased 5.08% over the past 60 days. The Zacks Consensus Estimate for quarterly revenues indicates a year-over-year increase of 69.2%.
Image Source: Zacks Investment Research
DVN Stock’s Earnings Surprise History
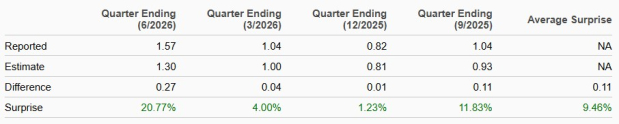
Devon Energy’s earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, the average surprise being 9.46%.
Image Source: Zacks Investment Research
Estimates for Q3 Earnings 2026
Devon Energy expects total production in the range of 1.66-1.69 million barrels of oil equivalent per day (BOE/d), with oil production projected in the range of 550,000-560,000 barrels per day. Natural gas production is anticipated to range from 4,450 million to 4,500 million cubic feet per day, while natural gas liquids production is expected between 375,000 barrels and 385,000 barrels per day.
What Our Quantitative Model Predicts for DVN
Our proven model predicts an earnings beat for Devon Energy this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is exactly the case here, as you will see below.
Earnings ESP: The company’s Earnings ESP is +5.07%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Zacks Rank: Currently, Devon Energy carries a Zacks Rank #2. You can see the complete list of today’s Zacks #1 Rank stocks here.
Some other companies in the same sector with the right combination of the two factors for an earnings beat this season are EOG Resources EOG, Evolution Petroleum EPM and Occidental Petroleum Corporation OXY. EOG, EPM and OXY currently have an Earnings ESP of +0.79%, +200.00% and +4.14%, respectively. Currently, all three companies carry a Zacks Rank #2.
Factors That Might Have Influenced DVN's Q3 Earnings
Devon Energy is well-positioned to deliver strong production growth in the third quarter of 2026, supported by a full quarter of contributions from its merger with Coterra Energy and continued operational momentum across the diversified asset portfolio. Strong well productivity in the Delaware Basin, combined with contributions from the Marcellus and Anadarko assets, is likely to have strengthened Devon Energy's production profile and support revenues and operating cash flows in the to-be-reported quarter.
Devon Energy's third-quarter performance is also expected to have benefited from operational efficiencies, disciplined cost management and ongoing integration of Coterra Energy's assets. The company anticipates lease operating expenses of $4.60-$4.90 per BOE and gathering, processing and transportation expenses of $3.40-$3.50 during the quarter. Its growing use of artificial intelligence for well optimization, improved drilling and completion techniques and shared infrastructure across the combined portfolio might have enhanced productivity and operating margins.
Moreover, Devon Energy has identified more than 350 synergy initiatives aimed at reducing operating expenses, optimizing capital allocation and improving overall efficiency. These initiatives are likely to support profitability in the third quarter, although anticipated capital expenditures of $1.4-$1.5 billion might have weighed on near-term free cash flow.
Devon Energy's strong financial position and shareholder-friendly initiatives are expected to have provided additional support in the third quarter of 2026. The company retired $750 million of outstanding term debt in July, strengthening its balance sheet and financial flexibility. Devon Energy continued share repurchases under the $8 billion authorization, underscoring management's commitment to shareholder returns. The company's disciplined reinvestment strategy and improving capital efficiency are also expected to have supported free cash flow generation.
However, volatility in crude oil and natural gas prices, weaker natural gas realizations due to regional pipeline constraints and higher financing costs might have partially offset these benefits in the to-be-reported quarter.
DVN Stock's Valuation
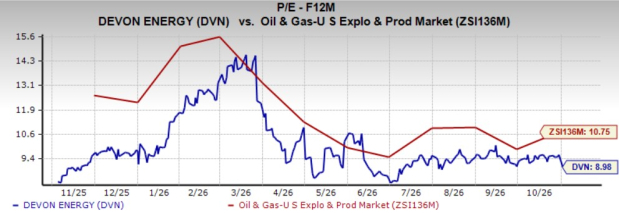
Devon Energy is currently trading at a discount relative to its industry based on the forward 12-month earnings per share. DVN’s current valuation of 8.98X is lower than the industry average of 10.75X and the five-year median of 9.56X.
Image Source: Zacks Investment Research
DVN's Debt to Capital
The oil and Energy business is capital-intensive and the companies operating in this industry generally borrow from the market to successfully run their operations.
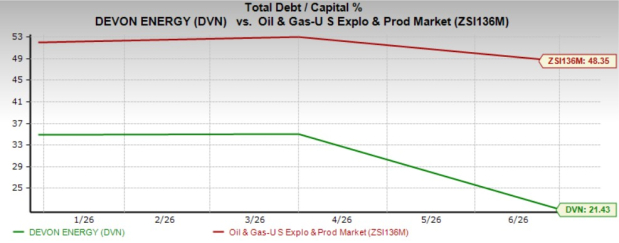
The total debt to capital of Devon Energy is 21.43% compared with its industry level of 48.35%. This indicates that the company is using much less debt than its peers in the industry to successfully run operations.
Image Source: Zacks Investment Research
Devon’s Price Performance
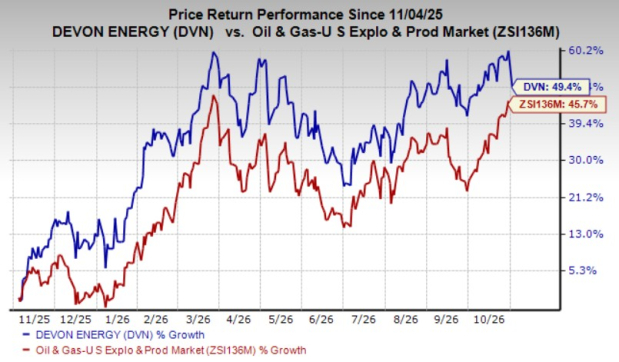
Devon Energy’s shares have gained 49.4% in the past year, outperforming the Zacks Oil & Gas- Exploration and Production-United States industry’s return of 45.7%.
Image Source: Zacks Investment Research
Investment Thesis
Devon Energy’s expanded multi-basin portfolio strengthens its production profile and provides exposure to oil, natural gas and NGL markets. A diversified asset base and stable full-year production outlook support the company’s long-term growth prospects.
Devon Energy’s focus on cost efficiency and merger synergies could strengthen profitability and cash flow generation. The company targets at least $1 billion in annual pre-tax synergies by year-end 2027. Its disciplined capital spending, combined with planned debt reduction to approximately $9 billion, could enhance financial flexibility and support returns across commodity cycles.
Shareholder-friendly initiatives remain an important investment consideration for Devon Energy. Strong adjusted free cash flow, strategic Permian investments and ongoing portfolio optimization could support sustainable shareholder distributions and long-term value creation.
Summing Up
Devon Energy’s third-quarter earnings are likely to come above estimates, and its long-term outlook remains solid. Ongoing investments and strong production from the company’s multi-basin assets will continue to boost production and support its operations.
Given the company's positive developments and increasing production volumes across multiple basins, investors may consider adding the stock to their portfolios ahead of third-quarter earnings.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Devon Energy Corporation (DVN): Free Stock Analysis Report
Occidental Petroleum Corporation (OXY): Free Stock Analysis Report
EOG Resources, Inc. (EOG): Free Stock Analysis Report
Evolution Petroleum Corporation, Inc. (EPM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).