

Howard Hughes Holdings HHH is set to report its third-quarter 2026 results on Nov. 5, after the market close.
The Zacks Consensus Estimate for third-quarter revenues is pegged at $642.8 billion, indicating an increase of 64.7% from the year-ago quarter’s reported figure.
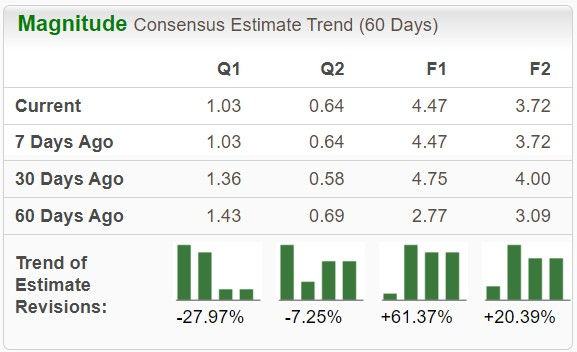
The consensus mark for earnings per share (EPS) is pinned at $1.03 and declined 33 cents over the past month. It also indicates a decline of 49% from the figure reported in the year-ago quarter.
Image Source: Zacks Investment Research
The company’s EPS beat the Zacks Consensus Estimate in three of the trailing four quarters and missed once, with the average surprise being 120.9%. The graph below depicts this surprising history:
Howard Hughes Holdings Inc. Price and EPS Surprise
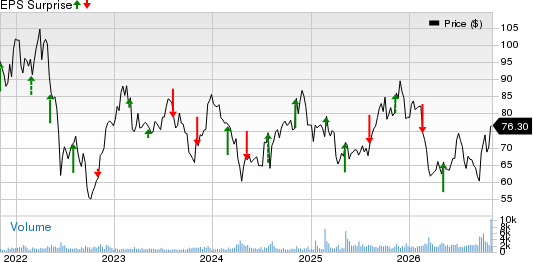
Howard Hughes Holdings Inc. price-eps-surprise | Howard Hughes Holdings Inc. Quote
Q3 Earnings Whispers for HHH
However, our proprietary model does not conclusively predict an earnings beat for Howard Hughes this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here. You can see the complete list of today’s Zacks #1 Rank stocks here.
Howard Hughes has an Earnings ESP of -32.68% and a Zacks Rank #1. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Factors Likely to Shape HHH’s Q3 Results
Howard Hughes is expected to have benefited from continued housing demand across its master-planned communities despite broader housing market challenges. Favorable land pricing and sustained homebuyer interest across its communities are likely to have supported the company’s real estate operations in the third quarter of 2026.
The company's Operating Assets segment is expected to have benefited from healthy leasing momentum and the expiration of rent abatements across its portfolio. These factors are likely to have supported rental revenues and net operating income during the quarter.
Moreover, the Vantage acquisition is expected to have bolstered HHH's quarterly revenues through its first full-quarter contribution. The company's focus on disciplined underwriting and the ongoing repositioning of Vantage’s investment portfolio may have improved its insurance operations.
Q3 Projections for HHH
The Zacks Consensus Estimate for Howard Hughes’ condominium rights and unit sales revenues is currently pegged at $11.5 million, which indicates an increase from $0.1 million in the year-ago quarter.
The consensus mark for rental revenues is pegged at $115.1 million, up from the $111.4 million reported in the year-ago period.
However, the consensus mark for Master Planned Communities land sales revenues is pinned at $137.9 million, down from $248.5 million in the year-ago period.
The Zacks Consensus Estimate for builder price participation revenues is currently pinned at $6.9 million, down from $16 million in the prior-year period.
The consensus mark for other revenues is pegged at $12 million, down from the $14.2 million reported in the year-ago period.
HHH’s Price Performance & Valuation
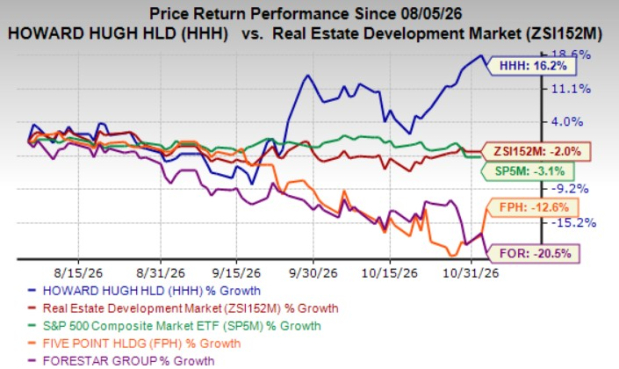
Howard Hughes’ shares have gained 16.2% in the past three months, outperforming the Zacks Real Estate - Development’s 2% decrease and the S&P 500 Index’s 3.1% decline over the same period. The stock also outperformed industry peers Forestar Group Inc. FOR and Five Point Holdings, LLC FPH, whose shares declined 20.5% and 12.6%, respectively.
FOR and FPH compete with HHH in residential land development and master-planned communities. Forestar primarily develops finished residential lots for homebuilders, while Five Point focuses on large-scale, mixed-use communities in California. HHH offers broader residential, commercial and income-producing real estate operations.
Image Source: Zacks Investment Research
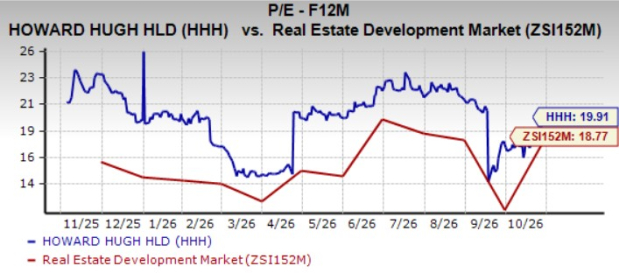
From a valuation standpoint, Howard Hughes’ shares are trading at a premium. In terms of forward 12-month P/E, HHH stock is trading at 19.91X compared with the Zacks Real Estate- Development industry’s 18.77X.
Shares of FOR and FPH are currently trading at P/E ratios of 7.64X and 18.94X, respectively.
Image Source: Zacks Investment Research
What Should Investors Do?
Howard Hughes’ resilient housing demand, favorable land pricing and steady leasing activity are expected to have supported its third-quarter performance. The first full-quarter contribution from Vantage is likely to have boosted revenues significantly while strengthening the company’s diversified business model.
Although HHH trades at a premium to the industry, its solid real estate fundamentals and long-term growth opportunities justify the higher valuation.
Given these positives, investors may consider buying HHH stock ahead of its third-quarter earnings release to capitalize on its growth prospects.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Howard Hughes Holdings Inc. (HHH): Free Stock Analysis Report
Forestar Group Inc (FOR): Free Stock Analysis Report
Five Point Holdings, LLC (FPH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).