

Humana Inc. HUM is set to report third-quarter 2026 results on Nov. 6, before the opening bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at a loss of $1.03 per shareon revenues of $40.46 billion.
The third-quarter earnings estimate has witnessed one upward revision and two movements in the opposite direction over the past 60 days. The bottom-line projection indicates a year-over-year decrease of 131.8%. Yet, the Zacks Consensus Estimate for quarterly revenues implies year-over-year growth of 23.9%.
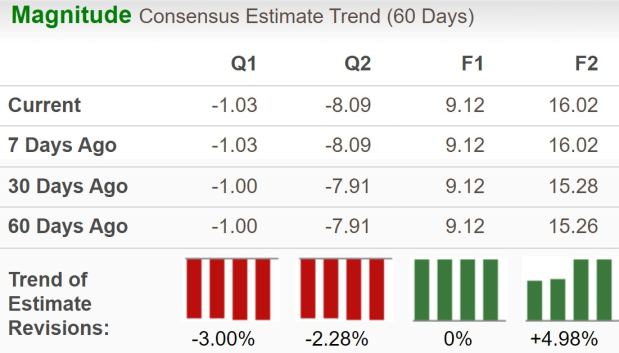
For full-year 2026, the Zacks Consensus Estimate for Humana’s revenues is pegged at $161.28 billion, implying a rise of 24.3% year over year. However, the consensus mark for current-year EPS is pegged at $9.12, implying a plunge of around 46.8% on a year-over-year basis.
HUM’s earnings beat the consensus estimate in each of the trailing four quarters, with the average surprise being 9.6%.
Humana Price and EPS Surprise
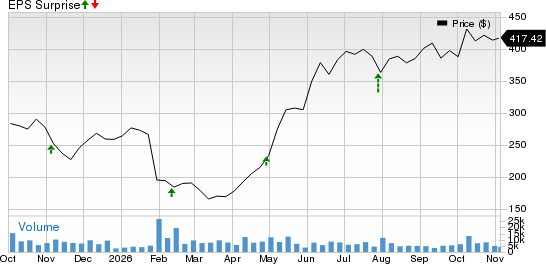
Humana Inc. price-eps-surprise | Humana Inc. Quote
Q3 Earnings Whispers for HUM
Our proven model predicts a likely earnings beat for the company this time around as well. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That is precisely the case here.
Humana has an Earnings ESP of +3.33% and a Zacks Rank #2. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
You can see the complete list of today’s Zacks #1 Rank stocks here.
What’s Shaping HUM’s Q3 Results?
The Zacks Consensus Estimate for HUM’s third-quarter premiums indicates a 26% increase from the prior-year quarter’s reported figure, whereas our model predicts 25.3% growth. Total Medicare is expected to witness 30.1% growth in the quarter under review. Similarly, the consensus mark for service revenues signals a 13.4% increase from a year ago.
The Zacks Consensus Estimate for insurance membership suggests 19.3% year-over-year growth, whereas specialty membership is expected to rise 3.5%. The Zacks Consensus Estimate for operating income from the CenterWell unit indicates 56.2% growth from the year-ago level. The above-mentioned factors are expected to have positioned the company for an earnings beat in the third quarter.
However, the consensus estimate indicates that Humana’s investment income will see a 30.4% drop from the year-ago level. We expect total operating costs to increase 25.4% in the third quarter, bringing the figure to $40.4 billion. This is likely to have led to a year-over-year decline in the bottom line.
The consensus mark for insurance benefits expense ratio is pegged at 94.3% for the to-be-reported quarter, deteriorating from 91.1% a year ago. The Zacks Consensus Estimate for operating income from the Insurance unit indicates a 295.6% plunge from a year ago. These are likely to have partially offset the positives.
How Did Peers Perform?
Several healthcare companies, including UnitedHealth Group Incorporated UNH, Centene Corporation CNC and Elevance Health, Inc. ELV, have already reported their financial results for the September quarter of 2026. Here’s how they performed:
UnitedHealth reported third-quarter 2026 adjusted EPS of $4.69, which beat the Zacks Consensus Estimate of $4.12 and rose 60.6% year over year. UNH’s quarterly results were aided by the strength witnessed in Optum Insight and Optum Rx. Medical cost management, pricing discipline and benefit design changes also contributed to the upside. However, weakness in Optum Health and declining memberships partially offset the positives.
Centene reported third-quarter 2026 adjusted EPS of 58 cents, which beat the Zacks Consensus Estimate of 7 cents and jumped 16% from 50 cents a year ago.Centene’s results benefited from higher premium and service revenues, supported by increased premium yield, growth in PDP membership, rate increases in Marketplace and Medicaid, and state-directed payments. These gains were partly offset by lower Medicaid and Marketplace membership.
Elevance reported third-quarter 2026 adjusted EPS of $6.99, which surpassed the Zacks Consensus Estimate by 50% and increased 15.9% year over year. The quarterly results benefited from higher premium yields in the Health Benefits segment and increased CarelonRx product revenues. However, ELV’s lower medical membership and elevated operating expenses partly offset the gains.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Humana Inc. (HUM): Free Stock Analysis Report
UnitedHealth Group Incorporated (UNH): Free Stock Analysis Report
Centene Corporation (CNC): Free Stock Analysis Report
Elevance Health, Inc. (ELV): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).