

Generac Holdings Inc. GNRC has a powerful growth setup built around data centers, recovering residential demand and faster earnings growth. The investment case now turns on whether that growth can outweigh margin pressure and a demanding production ramp.
Generac Holdings Inc. Price, Consensus and EPS Surprise
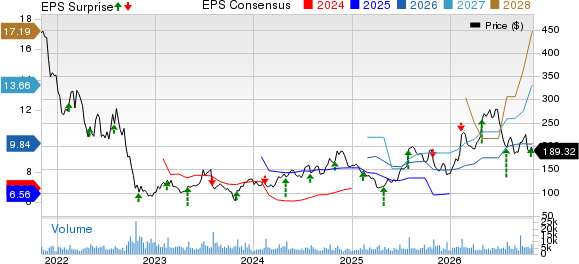
Generac Holdings Inc. price-consensus-eps-surprise-chart | Generac Holdings Inc. Quote
Valuation offers some support, but the stock is not uniformly cheap. Investors also need to account for supply constraints and the capital required to convert a large backlog into revenue.
GNRC’s Data Center Growth Strengthens the Bull Case
Commercial & Industrial revenues rose about 28% year over year to $553 million in the third quarter of 2026. Management sees a path to roughly doubling segment revenues in 2027 as data center, rental and industrial distributor demand expands.
Generac Holdings Inc. Revenue (Quarterly)
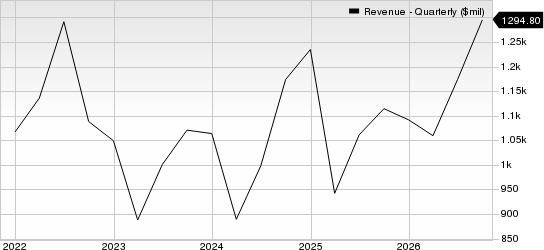
Generac Holdings Inc. revenue-quarterly | Generac Holdings Inc. Quote
Data center backlog reached about $4.5 billion, while nearly $600 million of non-hyperscale orders broadened the customer base. Cummins Inc. CMI is also expanding its data center power business, including generator and battery-storage projects, reinforcing the depth of demand across the power infrastructure market.
Generac’s Valuation Offers Some Room for Upside
GNRC trades at 14.6X forward 12-month earnings, below the Zacks sub-industry’s 20.8X and its own five-year median of 18.9X. That discount provides valuation support if earnings growth continues.
Image Source: Zacks Investment Research
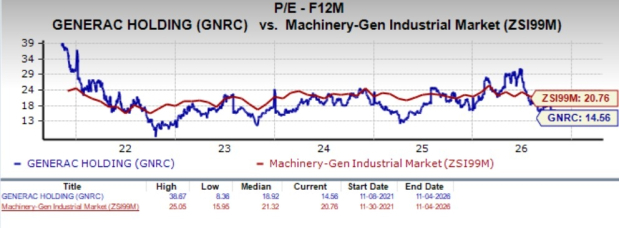
The picture is less compelling on other measures. GNRC’s enterprise value-to-EBITDA multiple is 25.7X and its price-to-cash-flow multiple is 19.4X, making the valuation case more balanced than the forward earnings multiple alone suggests.
GNRC’s Revenue Mix Could Weigh on Profitability
Generac’s consolidated gross margin reached 39.9% in the third quarter, up from 38.3% a year earlier. Faster C&I growth nevertheless created an unfavorable mix effect.
Management expects fourth-quarter gross margin to fall sequentially to 37-38% as data center sales become a larger portion of revenue and inflationary pressures persist. That trade-off matters because the fastest-growing business currently carries lower profitability than the residential segment.
Generac’s Capacity Build Raises the Execution Bar
Initial production at the Sussex, WI, facility began near the end of the third quarter, with a substantial ramp planned for the fourth quarter. The Belvidere, IL, packaging facility is expected to become operational in early 2027.
The added capacity can support backlog conversion, but tight high-horsepower diesel engine supply, production inefficiencies and cost overruns remain risks. Eaton Corporation plc ETN is also adding data center-related manufacturing capacity, showing that industry growth is being matched by a broad capital buildout.
GNRC’s Style Profile Favors Selective Optimism
Generac combines unusually strong data center visibility with a recovering residential business, but the margin and execution risks make selectivity important. The stock’s earnings multiple is attractive relative to key benchmarks, though the broader valuation picture is mixed.
GNRC currently carries a Zacks Rank #2 (Buy). It also has a Growth Score of B, Momentum Score of A and VGM Score of B, a combination that supports favorable near-term growth and momentum characteristics.
The Value Score of C tempers that signal. Investors have some valuation support, but the stock is not uniformly inexpensive across measures. The current profile therefore favors a constructive stance while keeping production execution and margin conversion in focus.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Generac Holdings Inc. (GNRC): Free Stock Analysis Report
Eaton Corporation, PLC (ETN): Free Stock Analysis Report
Cummins Inc. (CMI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).