

IREN Limited IREN is trying to turn its power and data-center portfolio into a large AI computing business. Customer commitments are expanding, but building the infrastructure and installing the hardware are only part of the challenge. The company must still bring capacity online and turn contracted demand into dependable earnings.
This transition has encountered a timing setback. IREN has shifted its goal of more than $4 billion in operating annualized run-rate revenues (ARR) from year-end 2026 to January 2027, potentially February. A customer-requested design change and supplier delays explain the revision despite the company saying the initial program is fully contracted and funded.
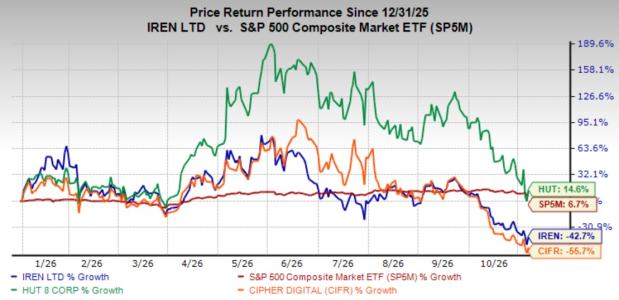
The shares rebounded after the Nov. 5 results, rising 20% to $21.64 on Nov. 6, the latest completed session. Hut 8 Corp. HUT and Cipher Digital CIFR gained 14.6% and 17.9%, respectively, that day. Still, IREN has fallen roughly 43% year to date. Cipher Digital, too, has declined more than 55%, though Hut 8 has appreciated more than 14% over the same time frame.
Image Source: Zacks Investment Research
A Full Order Book Does Not Eliminate Timing Risks for IREN
IREN's revenue backlog climbed 22% sequentially to $20.3 billion, with around two-thirds investment grade. The Horizon 1 facility is serving Microsoft, and the company expanded a major AI lab contract. Operating ARR reached $1 billion at September-end, suggesting the business is moving beyond its Bitcoin mining roots.
However, the jump to more than $4 billion depends on commissioning additional capacity, completing network upgrades and securing customer acceptance. Management expects January delivery but acknowledges that supplier delays could push the milestone to late February. ARR represents annualized contracted operating capacity, not GAAP revenues already earned. Any slippage would delay the conversion of the backlog into reported sales and raise concerns about IREN's ability to meet future construction timelines.
Iren’s Cloud Sales Are Rising Faster Than Profits
Fiscal first-quarter 2027 AI cloud revenues increased 182% sequentially to $200 million, lifting total revenues 66% to $228 million. The segment's gross margin before depreciation and amortization was 86%, while adjusted EBITDA improved to $66 million from $19 million in the previous quarter. These figures show improving scale.
Yet IREN still reported a $263 million net loss. Depreciation and amortization reached $148 million, and stock-based compensation was $106 million. The company also expects cash operating expenses to rise another $50 million-$60 million sequentially in the December quarter before new capacity contributes revenues. This mismatch threatens profitability and raises hardware replacement risks.
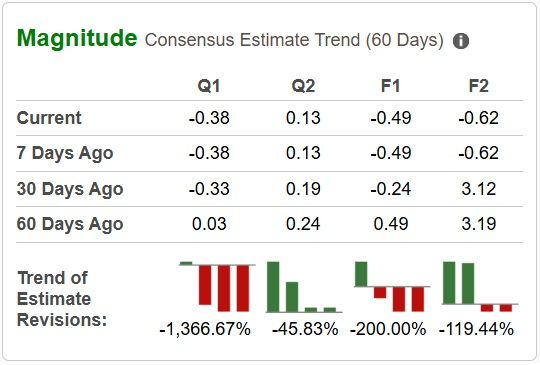
Estimates for IREN’s fiscal 2027 and 2028 earnings have also been revised downward in the past 30 days.
Image Source: Zacks Investment Research
Financing Is the Bigger Question at IREN
IREN held $5.8 billion in cash and restricted cash at September-end, but about $2.3 billion was restricted, and total debt stood near $10.2 billion. Management plans roughly $15 billion of additional fiscal 2027 capital spending, with $9 billion covered by cash and committed financing or customer prepayments. The remaining $6 billion still needs funding, subject to market conditions. This gap relates to expansion beyond the funded $4 billion ARR program, not that initial milestone.
The company has valuable unencumbered data centers and expects asset-backed financing to help bridge the gap. Still, reliance on borrowings, prepayments or equity leaves shareholders exposed to financing costs and potential dilution. Funding conditions could also slow the company's targeted expansion to 0.8 gigawatts by the end of 2027.
IREN's Discounted Valuation Still Warrants Caution
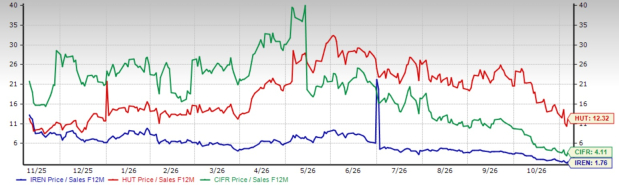
On a forward 12-month price-to-sales (P/S) basis, IREN trades at 1.76X, significantly below Hut 8 at 12.32X and Cipher Digital (CIFR) at 4.11X. This discount suggests that IREN is relatively inexpensive compared with its industry peers despite its growing AI cloud business and substantial contracted revenue backlog.
However, the lower multiple does not necessarily indicate an attractive investment opportunity. IREN's delayed $4 billion ARR target, continued net losses and substantial funding requirements raise concerns about its ability to convert projected sales into sustainable profits. Until IREN demonstrates stronger execution and improved earnings visibility, its valuation discount may reflect underlying risks rather than meaningful upside potential.
Valuation: Forward 12-month Price-to-Sales (P/S) Basis
Image Source: Zacks Investment Research
What Should Investors Do With IREN Stock Now?
IREN's contracted backlog, major customers and growing cloud revenues establish a real opportunity, but the delayed ARR milestone shows how vulnerable its plans remain to supplier timing and complex commissioning. Losses, rising operating costs and an additional $6 billion financing requirement add pressure, while its valuation still assumes substantial progress.
The strong Nov. 6 rebound does not erase these issues, especially when HUT and CIFR also rallied during a broader recovery in AI-related stocks. Until IREN demonstrates timely delivery, sustained profitability and a clearer funding path, reducing exposure appears more prudent than continuing to carry the shares.
At present, IREN carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
IREN Limited (IREN): Free Stock Analysis Report
Hut 8 Corp. (HUT): Free Stock Analysis Report
Cipher Digital Inc. (CIFR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).