

Qualcomm Incorporated QCOM is entering fiscal 2027 with a broader revenue mix, but the transition is arriving alongside weaker earnings expectations and lower near-term margins. That combination makes the stock less a simple diversification story than a test of whether newer businesses can scale fast enough to offset mobile pressure.
The valuation is mixed rather than clearly cheap, while estimate revisions and Style Scores argue against aggressive near-term positioning.
Qualcomm’s Diversification Case is Getting Stronger
Qualcomm expects non-handset QCT revenues, including automotive, IoT and data center, to grow more than 60% in fiscal 2027 and represent more than half of QCT revenues. Automotive exited fiscal 2026 at an annualized revenue run rate of about $8 billion, after fourth-quarter automotive revenues rose 89% year over year to roughly $2 billion.
Data center adds another growth leg, with management targeting $5 billion of fiscal 2027 revenues and an approximately $7 billion annualized exit rate. The competitive bar is high. Advanced Micro Devices AMD reported third-quarter 2026 data center revenues of $8.5 billion, up 97% year over year, while NVIDIA Corporation NVDA generated $89 billion of data center revenues in its fiscal second quarter of 2027.
QCOM’s Valuation Leaves Room for Debate
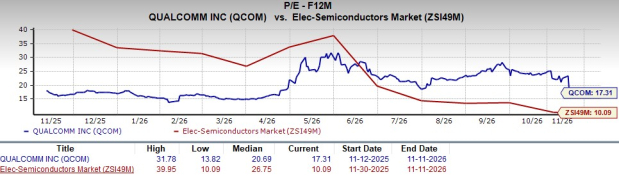
QCOM trades at 17.3X forward 12-month earnings compared with 10.09X for the Zacks sub-industry, 17.1X for the Zacks sector and 18.6X for the S&P 500. That leaves the stock close to the broader sector and market, but well above its sub-industry.
Image Source: Zacks Investment Research
The trailing 12-month EV-to-sales multiple tells a different story. Qualcomm’s 4.49X multiple is below the 8.44X sub-industry, 7.59X sector and 5.25X S&P 500 levels. Its Value Score of D reinforces that valuation is not uniformly attractive despite the EV-to-sales discount.
Qualcomm’s Earnings Outlook Still Warrants Caution
The Zacks Consensus Estimate for fiscal 2027 earnings is $9.71 per share, down from $10.54 reported in fiscal 2026. The current-year estimate has also fallen 5.8% over the past four weeks.
Handset conditions remain a key restraint. Qualcomm expects global handset units to remain flat to slightly down in calendar 2027, while Apple’s modem transition continues to reduce product revenues. First-quarter fiscal 2027 handset revenues are expected to decline by a mid-single-digit percentage sequentially.
QCOM’s Margin Recovery Depends on Execution
QCT earnings before taxes margin fell to 24% in the fiscal fourth quarter from 26% in the preceding quarter. For the first quarter of fiscal 2027, management expects QCT EBT margin of 20%-22%.
Higher semiconductor input costs are one pressure point. Qualcomm is raising product prices, with the full benefit expected in the second half of fiscal 2027. Data center custom silicon should be accretive to QCT operating margins but dilutive to gross margins, adding another mix challenge during the ramp.
Qualcomm’s Signals Favor Patience Over Conviction
The investment case is becoming more balanced as automotive and data center scale, but earnings revisions and margin pressure still limit near-term visibility. The stock’s valuation does not provide a uniformly wide margin of safety across measures.
Qualcomm currently carries a Zacks Rank #3 (Hold). Its VGM Score of F, Value Score of D, Growth Score of F and Momentum Score of F point to a weak near-term Style Score profile. With the Zacks Rank signaling a hold stance and the Style Scores offering little additional support, patience looks more consistent with the current setup than a high-conviction entry. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
QUALCOMM Incorporated (QCOM): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).