

Norwegian Cruise Line Holdings Ltd. NCLH has identified approximately $325 million in annualized savings and cash benefits during 2026 as part of its efforts to improve profitability. The total includes $100 million announced in third-quarter 2026, following approximately $225 million identified over the preceding two quarters.
Recent cost performance demonstrates progress. Third-quarter adjusted net cruise cost excluding fuel per capacity day declined 2.3% year over year in constant currency, approximately 140 basis points better than guidance. Despite certain expenses shifting into the fourth quarter, most of the outperformance carried into the full-year outlook. The company expects this unit-cost measure to decline approximately 0.4% in 2026, compared with an approximately 1% increase anticipated at the start of the year.
The additional $100 million in annualized benefits is expected to come from guest and crew air-travel optimization and adjustments to promotional offerings. Revised guest airfare promotions are expected to improve revenue economics as passengers booked under earlier offers complete their sailings, while crew-air initiatives target lower transportation and logistics costs. Benefits are expected to phase in through 2028.
Revenue performance is expected to improve gradually. First-half 2027 booked occupancy remains below the comparable prior-year level, although pricing is higher. The company does not expect marketing and revenue-management changes to meaningfully benefit that period. Second-half booked occupancy is in line with the prior year at higher prices. These trends and initial turnaround benefits underpin projected constant-currency net yield growth of 1%-2% year over year in 2027, with a meaningful acceleration in the second half.
Norwegian Cruise’s savings program and expected yield recovery provide a foundation for margin improvement in 2027. The pace of recovery will likely depend on realizing the identified efficiencies while strengthening revenue performance, particularly in the second half. The phased implementation of savings and lower first-half booked occupancy remain key considerations.
Key Peers Pair Yield Growth With Cost Discipline
Royal Caribbean Cruises Ltd. RCL is benefiting from yield growth and operating efficiencies that support profitability. Third-quarter 2026 net cruise costs excluding fuel per available passenger cruise day declined 1.8% year over year, partly reflecting expenses shifting into the fourth quarter. Royal Caribbean expects full-year 2026 constant-currency net yield growth of approximately 2.1%, with unit costs excluding fuel remaining approximately flat. Continued efficiency improvements are helping the company control expenses while investing in the guest experience.
Carnival Corporation Ltd. CCL is supporting profitability through stronger revenue performance and disciplined expense management. Third-quarter constant-currency yields increased nearly 2.5% year over year, while cruise costs excluding fuel per available lower berth day rose 1.8%, approximately 100 basis points better than guidance. Nearly all the quarterly cost savings relative to guidance carried into the full-year outlook. Carnival expects approximately 2.3% constant-currency yield growth and 2.2% growth in unit costs excluding fuel in 2026, with sourcing savings and operating efficiencies expected to support cost control in 2027.
NCLH’s Price Performance, Valuation & Estimates
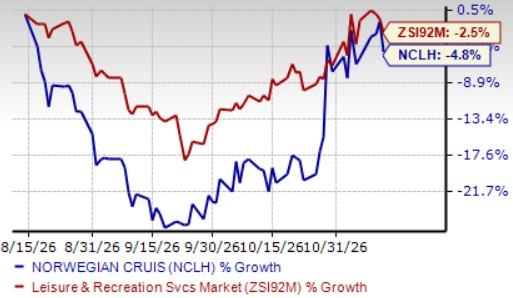
Shares of Norwegian Cruise have declined 4.8% over the past three months compared with the industry’s fall of 2.5%.
NCLH Stock’s Three-Month Price Performance
Image Source: Zacks Investment Research
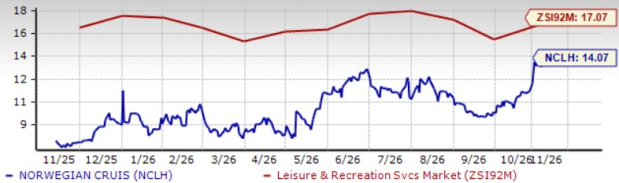
From a valuation standpoint, NCLH trades at a forward price-to-earnings ratio of 14.07, significantly below the industry’s average of 17.07.
CCL’s P/E Ratio (Forward 12-Month) vs. Industry
Image Source: Zacks Investment Research
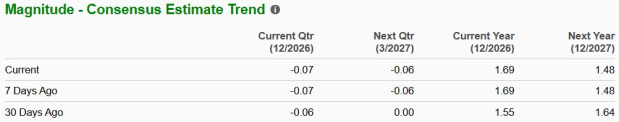
The Zacks Consensus Estimate for NCLH’s 2027 earnings implies a year-over-year decline of 12.6%. The EPS estimates for 2027 have decreased in the past 30 days.
EPS Trend of NCLH Stock
Image Source: Zacks Investment Research
NCLH stock currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Norwegian Cruise Line Holdings Ltd. (NCLH): Free Stock Analysis Report
Carnival Corporation (CCL): Free Stock Analysis Report
Royal Caribbean Cruises Ltd. (RCL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).