

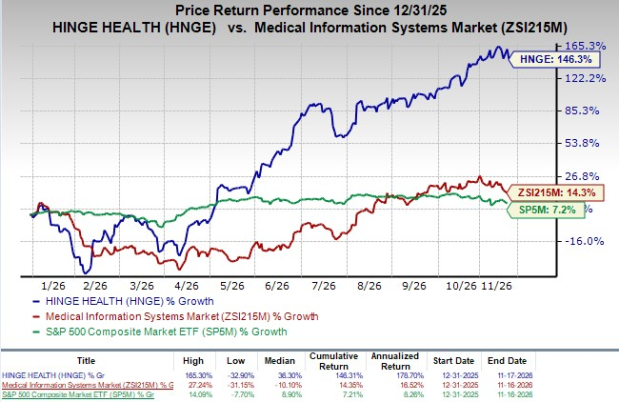
Hinge Health HNGE stock has surged 146.3% so far this year, significantly outperforming the industry’s 14.3% gain and the S&P 500’s 7.2% rise. The sharp rally reflects growing investor confidence in the company’s strong revenue growth, improving profitability and expanding digital healthcare platform.
Hinge Health’s third-quarter performance reinforced this momentum, with revenues jumping 52% year over year to $235 million. Last 12-month calculated billings increased 54% to $960 million, while operating margin expanded 1,300 basis points to 33%. The company raised 2026 revenue guidance to $879-$881 million, representing 50% growth at the midpoint. Improving member engagement, strong client additions and expansion into migraine and gastrointestinal care are further strengthening its long-term growth prospects.
Image Source: Zacks Investment Research
What’s Fueling HNGE’s Growth?
Higher Member Engagement Fuels Revenue Growth: Hinge Health's improving member yield and strong client additions are driving growth. For the first nine months of 2026, Hinge Health's revenues jumped 51% year over year to $630.1 million compared with $417.1 million in the prior-year period. Targeted enrollment campaigns increased nearly 75%, while member renewals grew 25%. Contracted clients reached 3,270, up 28% year over year. Reflecting these trends, management raised 2026 yield expectations to 4.6% from 4.45%.
AI-Driven Efficiencies Support Margin Expansion: Hinge Health's investments in AI, automation and lower hardware costs are strengthening profitability. Third-quarter gross margin expanded 480 basis points year over year to 88%, while operating margin increased 1,300 basis points to 33%. Operating expenses declined to 55% of revenues from 63% a year ago, reflecting improved operating leverage and spending discipline. Management raised 2026 operating income guidance to $266-$268 million.
Migraine Care Opens New Growth Opportunities: Hinge Health's Migraine Care Program is expanding its addressable market beyond musculoskeletal care. More than 800 clients covering approximately 9 million lives now have access to the program. Initial results showed a 23% reduction in monthly migraine days and a 28% decline in attack duration. Management expects the bulk of covered lives to launch in early 2027, contributing 10-20 basis points to overall yield that year.
GI Expansion Strengthens Multi-Product Strategy: Hinge Health's Cylinder Health acquisition is expanding its presence in gastrointestinal care. Since announcing the deal, the company has grown Cylinder's GI client base by approximately 40%. The integrated GI Care Program, combining AI-powered tools with access to specialists and therapists, is targeted for launch in summer 2027. Management expects a more meaningful revenue contribution in 2028, creating another long-term growth opportunity.
HNGE’s Estimates
The Zacks Consensus Estimate for HNGE’s 2026 and 2027 earnings per share (EPS) implies a year-over-year decline of 4.2% and growth of 26.5%, respectively, to $2.51 and $3.18. In the past 60 days, the consensus mark for the company's 2026 EPS has improved by 20 cents.
Revenues for 2026 are projected to grow 49.9% to $881.3 million and 27.9% to $1.13 billion for 2027.
Risks and Challenges
HNGE’s expansion into new care categories brings execution risks, as the integration of Cylinder Health and scaling of Migraine Care will require continued investments and successful client adoption. Management expects gross margin to moderate toward 85% in 2027 as it invests in care teams and member experience.
Moreover, growth will remain dependent on member yield and eligible lives, while average selling prices are expected to remain flat in 2027. Any slowdown in enrollment, renewals or client additions could weigh on revenue growth and profitability.
Conclusion
HNGE’s third-quarter 2026 performance highlights its ability to sustain strong growth while expanding profitability. Robust revenue growth, improving member yield, AI-driven efficiencies and strong cash generation support its business model. Expanding adoption of Migraine Care and GI solutions also offers additional long-term growth opportunities beyond its core MSK business. Management’s higher 2026 revenue and operating income guidance further reflects confidence in its growth trajectory. However, sustaining member engagement and executing its multi-product expansion will remain key.
With a Zacks Rank #1 (Strong Buy), HNGE presents an attractive growth opportunity, supported by strong operating momentum and expanding market opportunities.
Other Stocks to Consider
Some other top-ranked stocks from the broader medical space are OPKO Health OPK, Globus Medical GMED and Merit Medical Systems MMSI.
OPKO Health, currently carrying a Zacks Rank #2 (Buy), reported a second-quarter 2026 adjusted loss of 1 cent per share, which surpassed the Zacks Consensus Estimate by 87.5%. Revenues of $163.6 million beat the Zacks Consensus Estimate by 24.7%. You can see the complete list of today’s Zacks #1 Rank stocks here.
OPK has an estimated earnings growth rate of 23.3% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 95.1%.
Globus Medical, currently carrying a Zacks Rank #2, reported a second-quarter 2026 adjusted earnings per share (EPS) of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Merit Medical Systems, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $1.19, which beat the Zacks Consensus Estimate by 23.9%. Revenues of $418.8 million surpassed the Zacks Consensus Estimate by 3.5%.
MMSI has an estimated long-term earnings growth rate of 10.4%. Merit Medical Systems’ earnings surpassed estimates in the trailing four quarters, with the average surprise being 14.1%.
Discover the Stocks Our Experts Want to Own This Quarter
Each quarter, four Zacks editors compile their favorite stocks into one report. As a sign of the times, three of this quarter's picks can potentially cash in on the massive AI boom. One grew its commercial revenue more than 140% last quarter.
The fourth stock is an online retailer posting its most significant growth since the pandemic. Its shares jumped more than 25% after its last earnings report, then pulled back, giving investors a chance to capitalize on what could be a longer-term bullish trend.
Get Your Free Ultimate Four Report >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Hinge Health Inc. (HNGE): Free Stock Analysis Report
Merit Medical Systems, Inc. (MMSI): Free Stock Analysis Report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).