

AI data centers are facing growing power constraints, and the issue is becoming increasingly urgent. New utility capacity can take years to develop and bring online, but hyperscalers cannot afford to wait that long to support their growing computing needs. That gap between supply and demand creates an opportunity for Bloom Energy (BE), which is focused on delivering power where and when hyperscalers like Microsoft (MSFT), Amazon (AMZN), and Alphabet (GOOG) (GOOGL) require it. The fundamentals are now starting to provide support for the growing optimism around its opportunity.
Bloom Energy’s technology stands out because it can address the AI power challenge on a much shorter timeline. The company’s solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy’s systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
The company is also building strategic relationships that could support the next phase of growth. Its relationship with Brookfield’s AI infrastructure arm continues to grow, while its large capacity agreement with Oracle (ORCL) gives it exposure to some of the biggest AI infrastructure projects underway. Bloom Energy’s financial profile also remains supportive. Margins are improving as the business scales, while a healthy cash position allows the company the flexibility to increase manufacturing capacity without relying on equity issuance.
About Bloom Energy Stock
Bloom Energy generates and distributes renewable energy, which has become especially critical since the emergence of data center demand and power infrastructure. It is headquartered in San Jose, California.
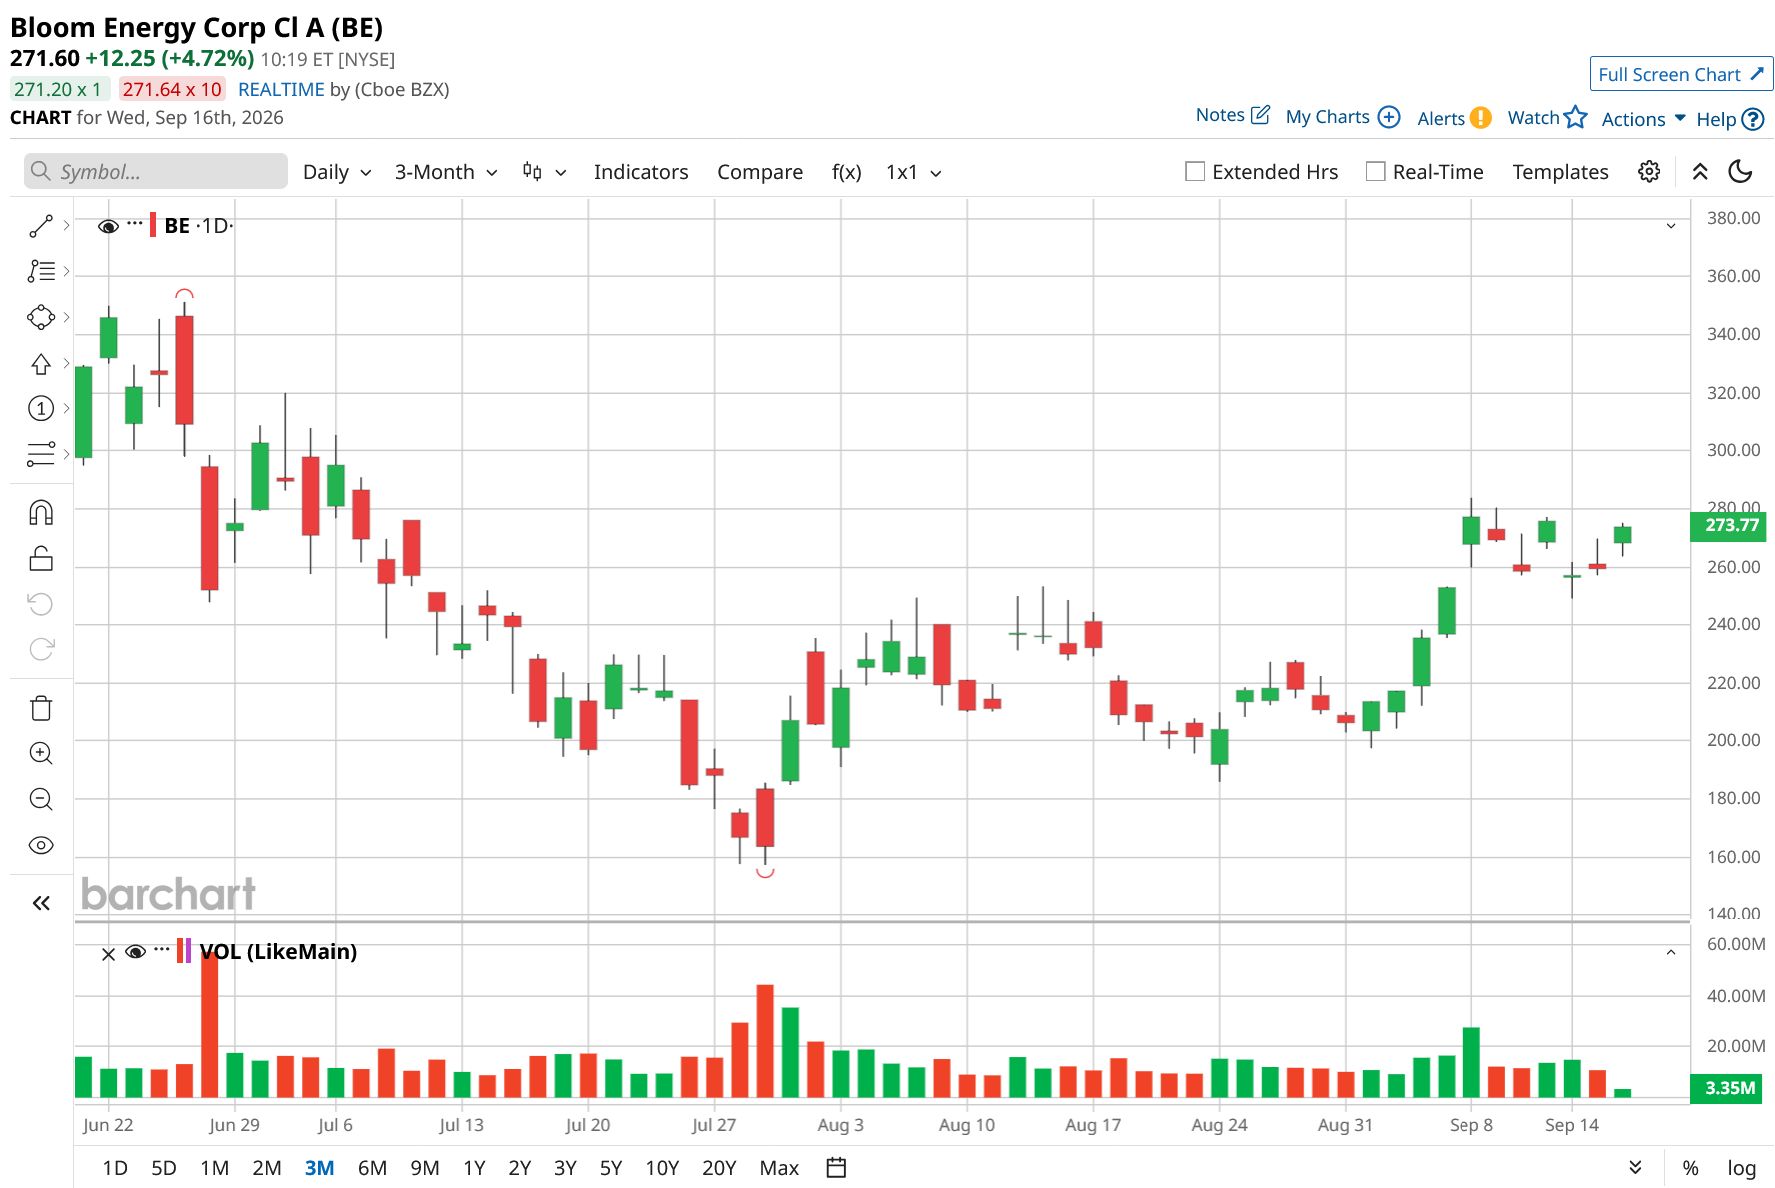
BE stock was in the news again when Nancy Pelosi disclosed her husband had just bought some stock and options on the company’s shares and was bullish. Bloom Energy's stock rallied as a result and is up 19% in the past month.
 www.barchart.com
The scale of the demand is now showing up in Bloom Energy’s financial performance. The company generated more than $1 billion in revenue during the second quarter of fiscal 2026. It was the first quarter in its history to exceed that revenue level. Revenue was up 166% year-over-year (YoY), and management raised its full-year 2026 revenue guidance to $3.9 billion to $4.2 billion. That implies roughly 100% growth for the year. That indicates recent performance is more than just a one-quarter boost. The important point is that management continues to raise its expectations as the demand for Bloom Energy’s systems grows.
The Second-Half Bar Just Got Higher
The company’s raised guidance is encouraging, but it also sets a high bar for the second half of 2026. Bloom Energy generated $1.82 billion in revenue in the first half of 2026. To reach its $3.9 billion to $4.2 billion full-year outlook, it needs to generate about $1.04 billion to $1.19 billion per quarter. That would represent a significant increase from the same period last year. However, the comparison looks different when measured against its latest record quarter. At the lower end of the guidance range, Bloom Energy could post quarterly revenue slightly below its second-quarter level to meet its annual target. The key requirement is maintaining the current pace of growth. There is also customer concentration risk to consider, as a meaningful share of the company’s revenue is connected to related-party sales through Brookfield joint ventures.
The key test for Bloom Energy now is whether it can continue converting its backlog and expanding margins faster than Wall Street expects. That outperformance has helped drive the stock’s re-rating this year, making continued momentum in both areas important to the bull case. If that continues, buying the stock even after the Pelosi rally would make sense.
Why Analysts See More Room to Run?
Bloom Energy’s latest earnings beat and raised outlook led to a sharp move in the stock. However, the analyst reaction that followed provides a more profound look at the strength of the underlying business. Mizuho upgraded the stock from “Neutral” to “Outperform” while lowering its price target from $285 to $242, following a revision to quarterly service revenue. That combination is significant because it shows the firm is becoming more constructive on the business even while taking a more cautious view of the short-term valuation. The upgrade, therefore, seems to reflect confidence in the company’s underlying fundamentals rather than simply reacting to a stronger quarter.
Mizuho analyst Maheep Mandloi identified several reasons for the more positive stance. Bloom Energy now has more than $27 billion in financing capacity, while its backlog continues to grow faster than revenue. The company has also made incremental progress on permitting in New Mexico. Collectively, these developments support different parts of the investment case. The financing capacity gives Bloom Energy more room to support its continued expansions. Faster backlog growth also suggests that demand is building ahead of recognized revenue. Meanwhile, progress on permitting indicates that the company is moving forward with the infrastructure needed to support that growth.
Increasing prices for gas turbines and other traditional power options are also creating a favorable environment for Bloom Energy’s faster deployment model. Mizuho expects the company’s adjusted EBITDA margin to expand 920 basis points through 2030, ahead of Wall Street’s forecast of 830 basis points.
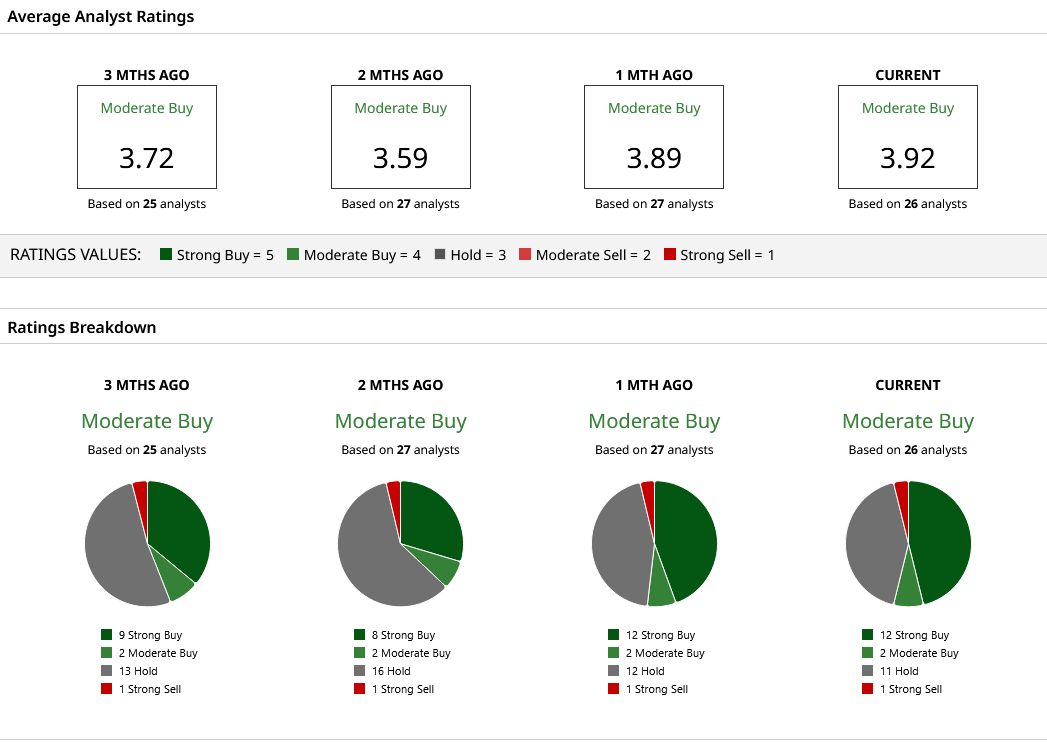
The broader analyst community is also fairly bullish with a “Moderate Buy” consensus and $282.77 price target, which sits 6% above its current price. The high target of $354 leaves room for a 33% increase still as well.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Tesla Stock Fans, Mark Your Calendars for October 1 How I’m Using This Great Barchart Stock Screener to Feel Like the ‘Dr. J’ of Trading If You Missed the Nancy Pelosi Rally, Here’s the Case for Buying Bloom Energy Stock Now ’AI Not Worth Pursuing’ If It’s Not ‘Helping Humanity.’ Microsoft’s Satya Nadella Pushes Back on Anthropic’s Control Framing and Offers a Practical Way Out.