

Crowdstrike (CRWD) used its biggest event of the year — Fal.Con 2026 — to reinforce the strength of its growth story. Record attendance, prominent artificial intelligence (AI) partners appearing on stage, and forward guidance beating consensus estimates all highlighted management’s confidence in the business. Analysts responded positively to the event, helping push CRWD stock higher. But that optimism only comes weeks after the company suffered one of its sharpest single-day declines in recent memory following guidance concerns from a sector peer.
With shares of Crowdstrike already trading at a premium, even indirect changes in expectations around industry growth can trigger large price swings. That contrast between strong company-specific momentum and sensitivity to broader sector signals is worth watching closely.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Record Attendance and Guidance That Beat Expectations
Held from Aug. 31 to Sept. 3, Fal.Con 2026 attracted more than 10,000 attendees, setting a new record compared with the 8,000-plus who attended the event in 2025. The conference also featured Intel (INTC), Nvidia (NVDA), and both leading frontier AI labs, which Jefferies analyst Joseph Gallo viewed as evidence of an expanding ecosystem around the company.
Nvidia provided particularly strong validation by calling Crowdstrike its most important security partner. Management also set an aggressive outlook for fiscal 2028, forecasting net new annual recurring revenue (ARR) growth of more than 20%, well above the consensus estimate. Based on that outlook, total ARR growth would reach 24.6% compared with the 22.8% consensus.
Is Crowdstrike Stock Overvalued?
Crowdstrike’s premium valuation makes the stock particularly sensitive to changes in growth expectations. Just weeks before Fal.Con 2026, shares of CRWD stock fell roughly 7% in their worst single-day decline in recent memory after SentinelOne (S) cut its EPS guidance despite beating revenue expectations. Jefferies analyst Joseph Gallo has also cautioned that the fiscal 2028 outlook will face “a larger base/tougher comp” compared with the setup behind the fiscal 2027 guidance increase. CRWD stock’s reaction to sector-wide guidance changes shows that investors have little tolerance for disappointment, as the recent selloff made clear.
Crowdstrike’s expanding ecosystem and Nvidia’s endorsement provide genuine evidence of its leadership in the category. But the stock’s premium multiple changes the risk-reward equation. A recent sympathy selloff following a guidance cut from a sector peer showed how quickly sentiment can shift. It also suggests that the optimism coming out of Fal.Con 2026 leaves the company with relatively little room for disappointment.
About Crowdstrike Stock
Crowdstrike is a cybersecurity company that helps businesses protect their computers, cloud systems, identities, data, and applications from cyber threats. Its main product is the Falcon platform, a cloud-based security system that customers access through subscriptions. Moreover, the company offers a wide range of security services and tools that help organizations detect, investigate, and respond to cyberattacks. With the AI tailwind, Crowdstrike has made a strategic alliance with Cognizant (CTSH) to help enterprises secure AI across its lifecycle. Founded in 2011, Crowdstrike is headquartered in Austin, Texas.
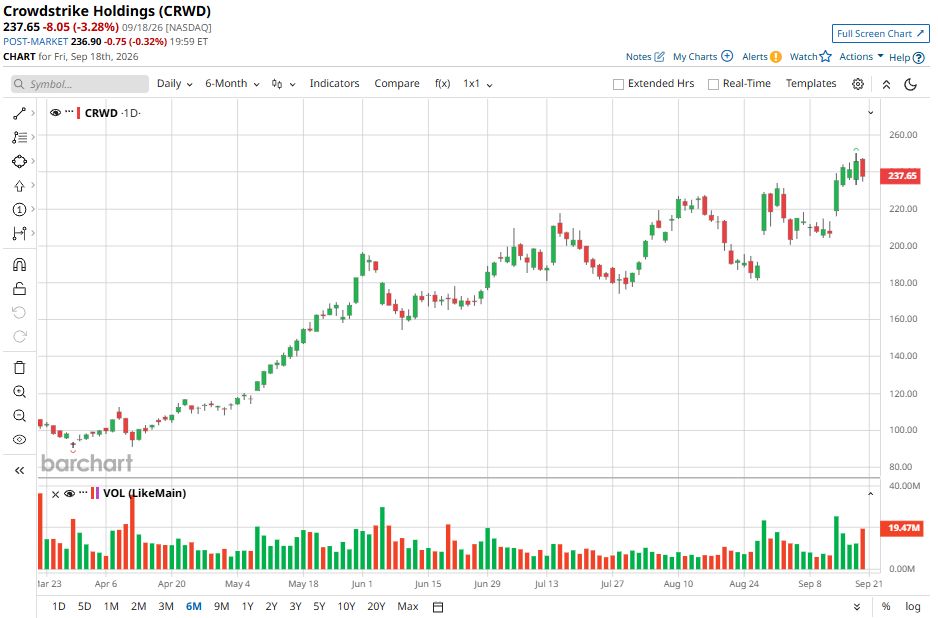
Over the last 12 months, CRWD stock has surged 99%, significantly outperforming the iShares Cybersecurity and Tech ETF’s (IHAK) 27% gain during the same period. The rise has been primarily driven by accelerating AI-driven cybersecurity demand, record recurring revenue, and customer adoption of the Falcon platform. Moreover, the company has consistently delivered strong earnings, with ARR reaching $5.84 billion in its latest quarter, up 25% year-over-year (YOY). These factors have strengthened investor confidence in the company’s long-term growth prospects.
 www.barchart.com
Falcon Flex Adoption Strengthens Crowdstrike's Path to Higher ARR
Crowdstrike reported its second-quarter fiscal 2027 earnings on Aug. 26. The company reported revenue of $1.47 billion, up 26% YOY. Subscription revenue for the quarter was $1.4 billion, up 27% YOY, while professional services revenue was a record $71 million. Net new ARR was $333 million, a company record and up 51% YOY. CFO Burt Podbere said the company generated record cash flow from operations of $530 million and record free cash flow of $377 million. The quarter also showed stronger profitability. Non-GAAP operating income reached a record $372 million. The company is benefiting from operating leverage as it grows.
Looking forward, Crowdstrike expects ARR to be in the range of $6.184 billion to $6.188 billion for Q3 fiscal 2027. Total revenue is expected to be in the range of $1.523 billion to $1.529 billion. The company also expects a free cash flow margin of 27.5% in the quarter.
Crowdstrike also raised its full-year fiscal 2027 guidance. It expects revenue of $5.991 billion to $6.011 billion. Net new ARR is expected to be about $1.355 billion. Management pointed to a record pipeline, continued Falcon Flex momentum, and rising demand tied to AI security.
What Do Analysts Expect for CRWD Stock?
On Sept. 4, William Blair analyst Jonathan Ho reiterated a “Buy” rating on CRWD stock. The analyst believes the accelerating adoption of AI across businesses will create significant long-term opportunity for cybersecurity companies. Ho sees security becoming an essential part of AI deployment rather than a barrier to it. Crowdstrike is well-positioned to benefit from this trend due to its strong cybersecurity platform, large data set, and industry leadership position. Similarly, Scotiabank analyst Patrick Colville reiterated a “Buy” rating on CRWD stock and assigned a price target of $265.
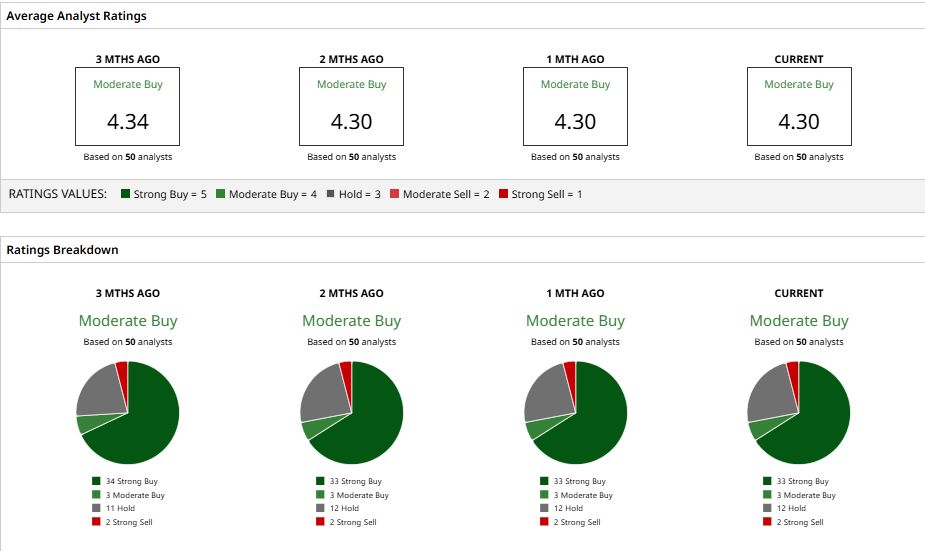
Based on 50 Wall Street analysts with coverage, Crowdstrike stock holds a consensus “Moderate Buy” rating. Out of those analysts, 33 have a “Strong Buy” rating, three have a “Moderate Buy” rating, 12 have a “Hold” rating, and two have a “Strong Sell” rating. The mean price of $238.27 sits just below the current share price. However, the high price target of $425 reflects potential upside of 70% from current levels.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play CrowdStrike Stock at All-Time Highs AMD Stock Alert: Advanced Micro Devices Joins the Trillion-Dollar Club Evercore Just Upgraded Ciena Stock. Here's Why. Jefferies Just Upgraded Arhaus Stock. Here's Why.