

Insulet Corporation (PODD), headquartered in Acton, Massachusetts, operates as an innovative medical device company. Valued at $9.7 billion by market cap, the company develops, manufactures, and sells insulin delivery systems for people with insulin-dependent diabetes.
Companies worth $2 billion or more are generally described as “mid-cap stocks,” and PODD fits right into that category with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical devices industry. PODD drives innovation through heavy investment in R&D, focusing on user-friendly diabetes solutions. With a customer-centric approach, the company provides comprehensive support services and engages with the diabetes community. PODD is expanding globally, entering new markets and establishing distribution channels to increase its international presence.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
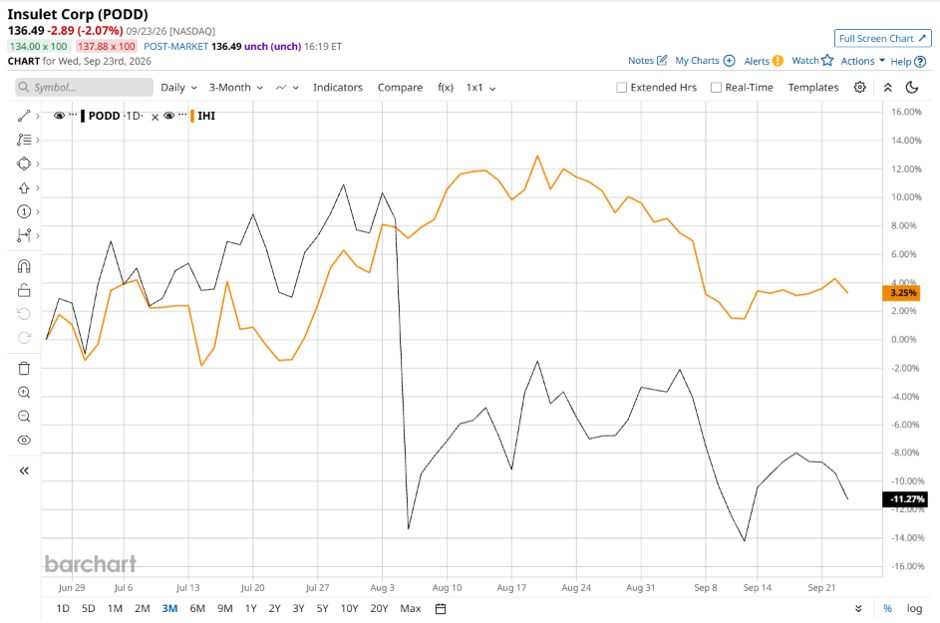
Despite its notable strength, PODD slipped 61.5% from its 52-week high of $354.88, achieved on Nov. 20, 2025. Over the past three months, PODD stock has declined 5.2%, underperforming the iShares U.S. Medical Devices ETF’s (IHI) 5.4% gains during the same time frame.
 www.barchart.com
In the longer term, shares of PODD fell 52% on a YTD basis and dipped 58.4% over the past 52 weeks, notably underperforming IHI’s YTD losses of 16.7% and 14.4% during the same time frame.
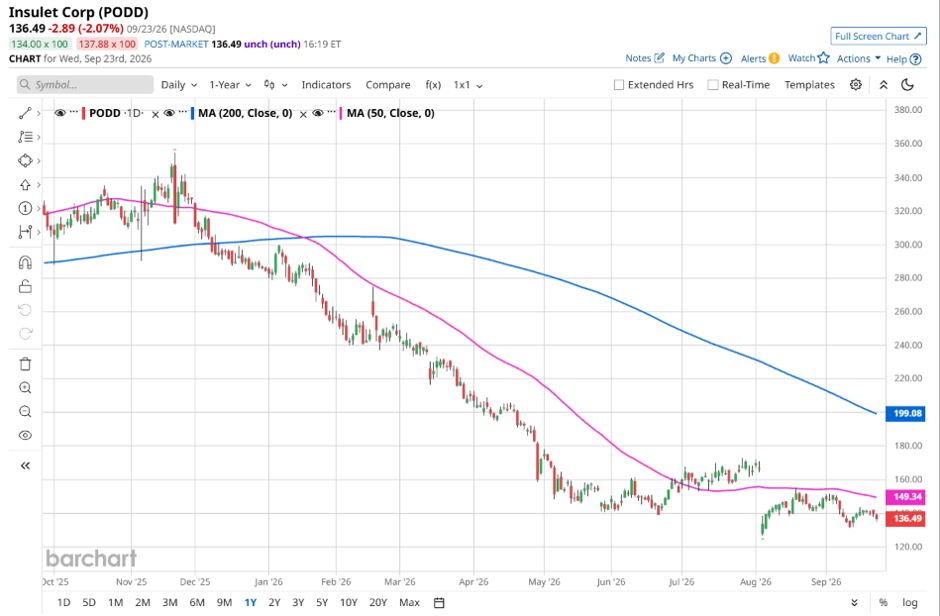
To confirm the bearish trend, PODD has been trading below its 200-day moving average since early December, 2025. The stock is trading below its 50-day moving average over the past year, with some fluctuations.
 www.barchart.com
PODD underperformed as market sentiment was weighed down by commercial friction in its Type 2 diabetes segment, key adoption concerns, and intensifying competition. While top-line growth remained solid via its Omnipod 5 system, investors reacted sharply to lower-than-expected retention rates among new Type 2 users during their first 90 days of therapy, forcing a reevaluation of patient onboarding and commercial support models. Compounding these retention hiccups, broader macro anxiety over GLP-1 adoption dampening long-term insulin demand and aggressive pressure from rival automated insulin delivery providers dampened investor enthusiasm, offsetting management's progress in expanding U.S. insurance coverage and stabilizing pricing.
On Aug. 5, PODD shares nosedived over 20% after reporting its Q2 results. Its adjusted EPS of $1.66 beat Wall Street expectations of $1.44. The company’s revenue was $801.7 million, topping Wall Street forecasts of $786.8 million.
PODD’s rival, DexCom, Inc. (DXCM) shares have taken the lead over the stock, gaining 32.2% on a YTD basis and 28.6% over the past 52 weeks.
Wall Street analysts are reasonably bullish on PODD’s prospects. The stock has a consensus “Moderate Buy” rating from the 27 analysts covering it, and the mean price target of $171.58 suggests a potential upside of 25.7% from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
McDonald’s Increased Its Dividend by Nearly 4%. How to Play MCD Stock Here. Billionaire Mark Cuban Said He’d Trust a Seeing-Eye Dog Over a Self-Driving Car, ‘A Dog Will Recognize Adversarial Situations Better Than AI Can’ CoreWeave Priced an Upsized $3.7 Billion Convertible Note as Capex Spending Spikes. What That Means for CRWV Stock Fans. A $1 Billion Reason to Buy On Holdings Stock