

Pennsylvania-based Universal Health Services, Inc. (UHS) is a major U.S. healthcare provider. With a market cap of 10.6 billion, Universal Health operates through Acute Care Hospital Services and Behavioral Health Care Services segments.
Companies worth between $10 billion and $200 billion are generally described as "large-cap stocks." Universal Health fits right into that category, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical care facilities industry.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
UHS has a strong competitive position in healthcare, supported by its large network of acute-care and behavioral-health facilities, established regional presence, and scale. Its significant behavioral-health footprint provides diversification beyond traditional hospital operations, while its size helps it benefit from operating efficiencies and broad payer and provider relationships.
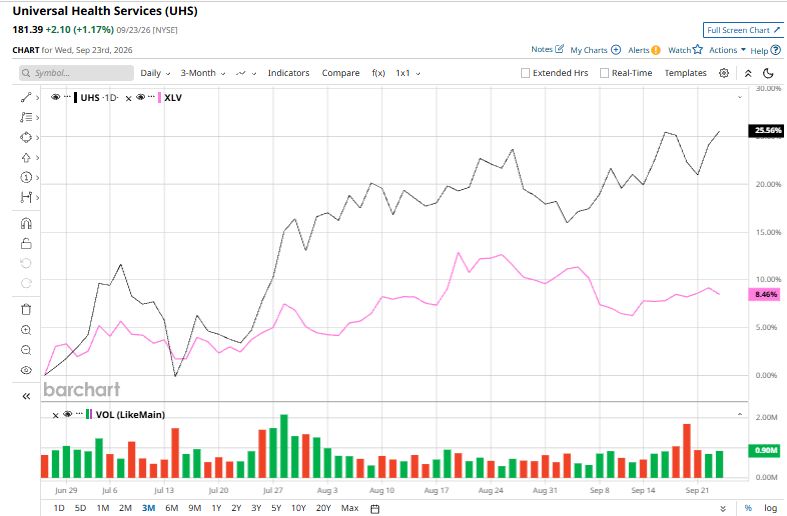
UHS has been on a roller-coaster ride. After hitting its 52-week high of $246.32 on Nov. 26, the stock remains 26.4% below that peak but has staged a strong 24.4% rebound over the past three months. In contrast, the Health Care Select Sector SPDR Fund (XLV) has declined 10.9% during the same time frame.
 www.barchart.com
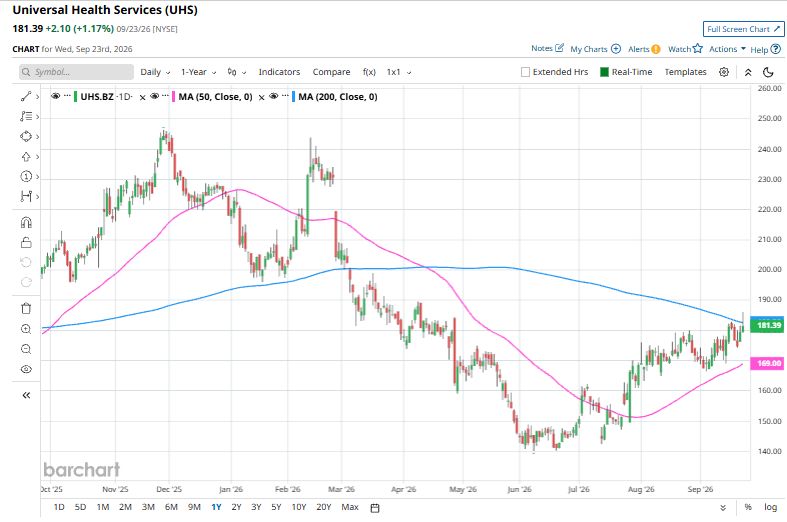
That momentum, however, comes against a weaker longer-term picture. UHS is down 16.8% in 2026 and 6.9% over the past year, trailing the XLV’s 9% rise in 2026 and 23.3% rise over the past year.
UHS is showing a mixed technical picture. The stock has remained below its 200-day moving average since early March, signaling persistent longer-term pressure, but its sustained move above the 50-day moving average since late July points to improving near-term momentum.
 www.barchart.com
UHS has underperformed the broader market as slower underlying growth and modest cash generation have weighed on investor sentiment. Same-store sales growth has averaged 4.2% over the past two years, slightly trailing peers, while revenue growth is expected to slow to 4.8% over the next 12 months from 8.2% historically. Meanwhile, its average free cash flow margin of 4.6% has limited financial flexibility and reinvestment capacity, adding to concerns around the stock’s growth outlook.
On Aug. 17, UHS completed its acquisition of Talkspace, combining its extensive behavioral-health network with Talkspace’s nationwide virtual mental-health platform. The deal is designed to create a more integrated care model spanning virtual therapy and psychiatry, outpatient services, crisis intervention, and inpatient treatment. UHS shares rose 1.5% in the following session.
UHS’ underperformance stands out even more against healthcare heavyweight HCA Healthcare, Inc. (HCA). While HCA has gained 6.6% over the past year and slipped 6.5% year to date, UHS has suffered steeper declines over both periods.
Among the 20 analysts covering the UHS stock, the consensus rating is a “Moderate Buy.” Its mean price target of $192.76 suggests a 6.3% upside potential from current price levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Get Paid to Wait: Buy HOOD at a Discount or Earn Options Income Peloton’s New Folding Treadmill Might Not Be a Magical Fix for PTON Stock Nasdaq Futures Plunge as Rising Bond Yields Deepen Chip Selloff, Trump-Xi Summit in Focus How to Play AAPL Stock as New Fitness+ Layoffs Hit Apple