

On Sept. 22, GE HealthCare Technologies (GEHC) raised its quarterly dividend to $0.04 per share. That’s a more than 14% increase from the $0.035 it paid in each of the first two quarters of 2026. Shareholders of record on Oct. 23 will receive the new dividend payment on Nov. 13.
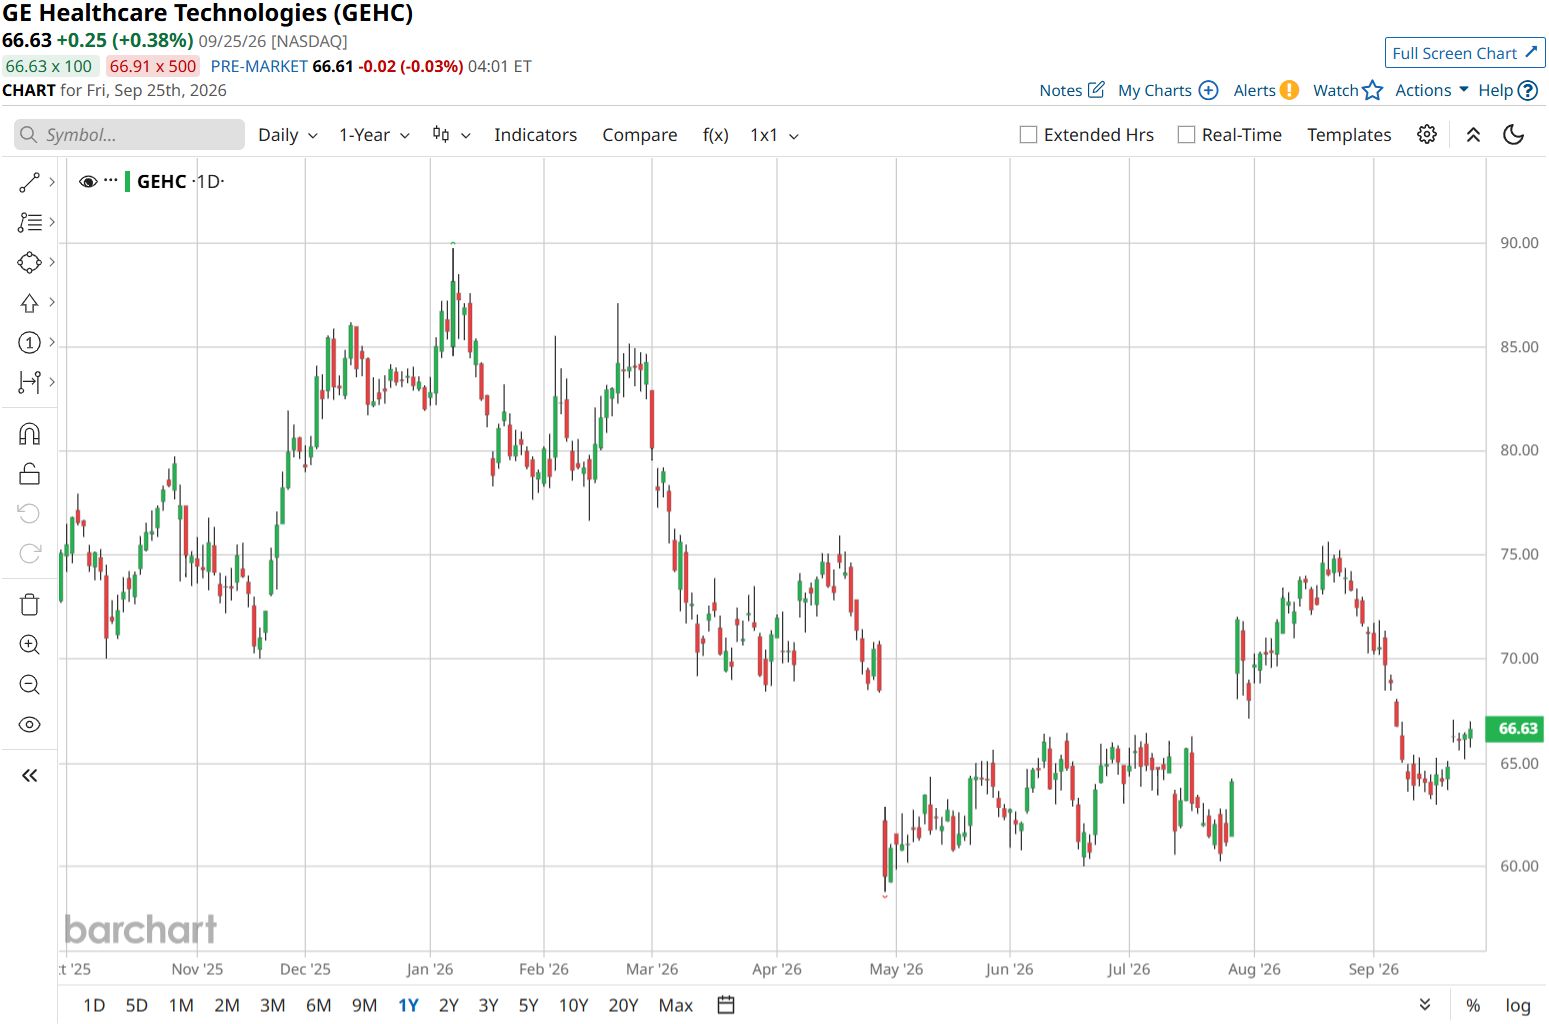
This raise comes after a rough stretch for the stock. GEHC stock is down 20% year-to-date (YTD), while the S&P 500 ($SPX) is up 12% over the same period. But GE HealthCare Technologies’ latest results were better than what that share price performance suggests. In the second quarter of fiscal 2026, revenue rose 5.7% to $5.3 billion, adjusted EPS grew 6.6% to $1.13, and GEHC stock jumped more than 12% after the report.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
Does the bigger dividend mean GE HealthCare Technologies is turning a corner? Let’s find out.
Do the Numbers Support the Raise?
GE HealthCare Technologies sells medical imaging equipment, pharmaceutical diagnostics, and healthcare software. GEHC stock is down 12% over the past 52 weeks and down roughly 20% so far this year.
 www.barchart.com
The stock trades at 13.5 times forward earnings, which is below the sector’s multiple of about 18.8 times, although that does not automatically make GE HealthCare Technologies stock a bargain.
The quarterly dividend rose from $0.035 to $0.04 per share, an increase of about 14%. That takes the annual payout from $0.14 to $0.16 per share. Before the dividend raise, the yield was roughly 0.21%, and the forward payout ratio was 3.01%. The new payout yields about 0.24% at current share prices. This is the third year of dividend increases, but the yield remains small.
The second-quarter results help explain why GE HealthCare could raise the payout. Revenue grew 5.7% to $5.3 billion, or 3.5% excluding acquisitions and currency effects. Organic orders rose 11.1%, compared with 3.4% a year earlier. Orders also exceeded revenue, putting the book-to-bill ratio at 1.15 and lifting backlog to a record $23.9 billion. That is work in the pipeline, not cash in the bank.
Net income rose to $561 million from $486 million, and net margin improved to 10.6% from 9.7%. Diluted EPS increased to $1.24 from $1.06, while adjusted earnings rose to $1.13 from $1.06. Still, adjusted EBIT margin fell 40 basis points to 14.2%, even as adjusted EBIT grew to $750 million from $729 million.
Tariff refunds helped profits and cash flow. Operating cash flow was $168 million, while free cash flow was $68 million, including $107 million in refunds. GE HealthCare Technologies also bought back $200 million in shares and ended the period with $2.1 billion in cash and $10.1 billion in debt. The dividend is affordable at its current size, but cash flow needs to improve without the help of refunds.
What Could Drive Growth From Here?
GE HealthCare Technologies’ CareIntellect for Operations helps hospitals spot possible bed, staffing, and wait-time problems up to 72 hours ahead. It uses patient and hospital data to suggest ways to ease those problems and keep patients moving through care. The Queen’s Health Systems and Duke Health will be the first to use the software application. GE HealthCare Technologies has not said how much revenue it expects from the software.
The company’s StarGuide GX 4D SPECT/CT scanner has also received a CE Mark but is still awaiting U.S. Food and Drug Administration (FDA) 510(k) clearance. It is designed for a range of nuclear medicine uses and tracers. Clearance would allow GE HealthCare to bring it to the U.S. market, but that has not happened yet.
Finally, GE HealthCare Technologies has added Explorer 1, Advanced 1, and Focus 1 to its Vivid cardiovascular ultrasound range. They join the higher-end Vivid Pioneer, giving hospitals and care teams more options for different heart-imaging needs.
What Do Analysts Expect From GEHC Stock?
GE HealthCare Technologies is expected to report earnings on Nov. 4. Analysts expect Q3 earnings of $1.21 per share, up 13% from $1.07 a year ago. For the full year, analysts expect earnings of $4.93 per share, up 7% from $4.59 in fiscal 2025.
Analysts differ on how much upside is in store for the stock. On July 31, UBS analyst Graham Doyle kept a “Hold” rating on GEHC stock but raised his price target from $67 to $73. On Sept. 17, BTIG analyst Ryan Zimmerman maintained his “Buy” rating and a $79 price target. Needham analyst David Saxon also recently initiated coverage with a "Buy" rating and a $93 price target. His view is that the share price already reflects a gloomy outlook, leaving room for gains if the business performs better than feared.
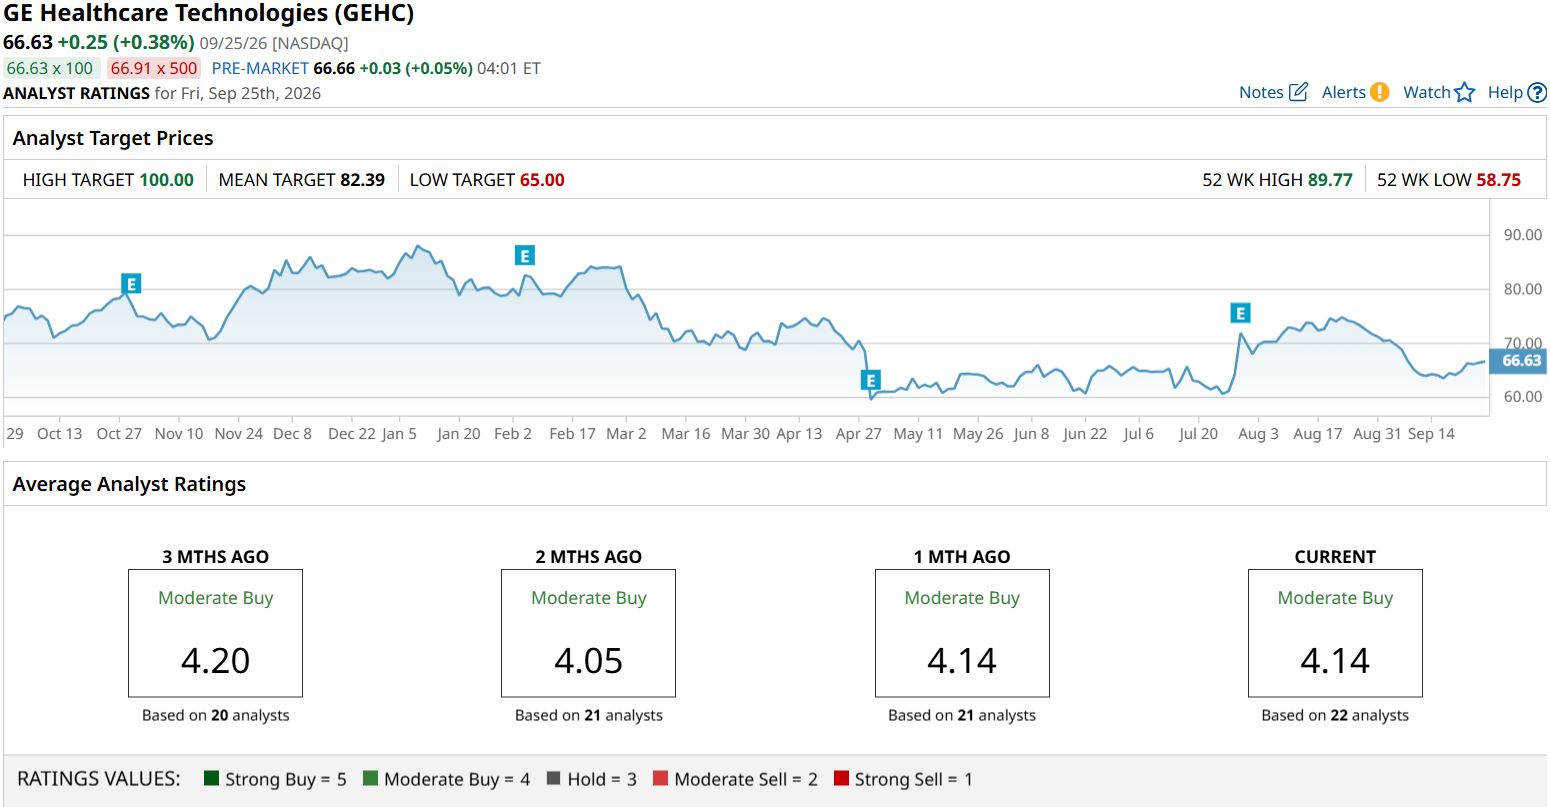
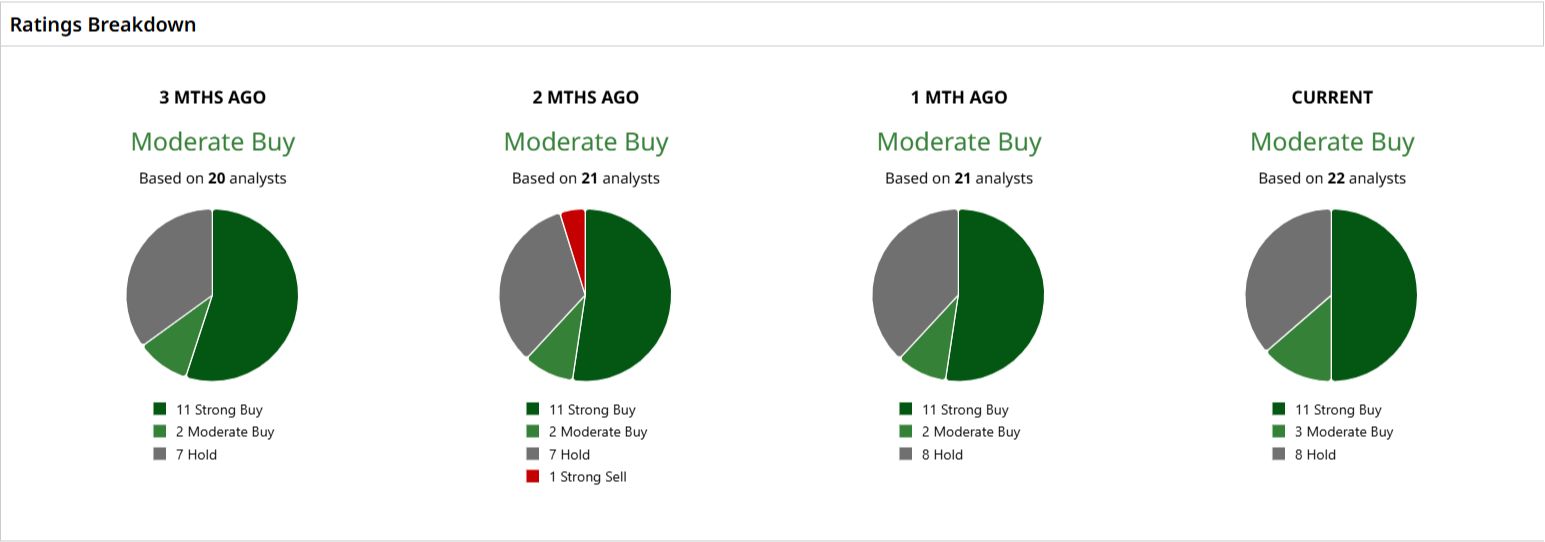
Overall, based on 22 analysts with coverage, GEHC stock has a consensus “Moderate Buy” rating on Wall Street. The average price target of $82.39 points to potential upside of about 26% from current levels.
 www.barchart.com
 www.barchart.com
Conclusion
GE HealthCare’s dividend raise looks supported by a stronger order book and a payout that remains small relative to earnings, but I would not call the turnaround proven yet. Cash flow was weak in the latest quarter, and tariff refunds helped the results. At roughly 13.5 times forward earnings, and with analysts expecting earnings growth, I think shares of GEHC stock are more likely to recover than keep falling if GE HealthCare converts its backlog into sales and improves cash generation. The next earnings report should offer a clearer test. For now, the dividend hike is an encouraging sign, not the whole reason to buy the stock.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Healthcare Stock Just Raised Its Dividend by Nearly 15%. How Daily Dividends Could Shake Up the MicroStrategy Stock Story This Telecom Stock Just Raised Its Dividend by Nearly 15%. Constellation Energy vs. Vistra: Nuclear's Two Biggest AI Bets, and why I'm Picking One.