

Apple’s (AAPL) first foldable iPhone is nearing its commercial debut, giving investors a new test of whether the company can create a meaningful new premium-hardware growth driver. Counterpoint Research expects Apple to sell about 6 million iPhone Duo units this year, providing an early demand benchmark for a device that is expected to become the company’s most expensive iPhone.
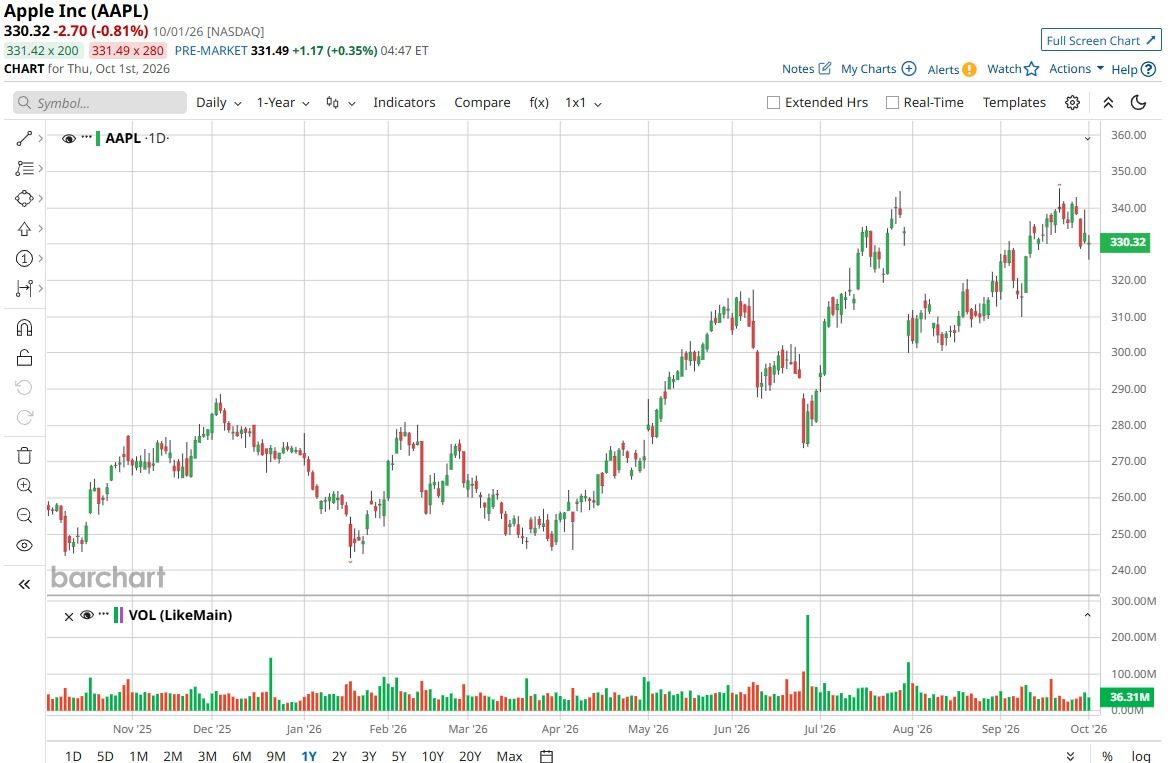
The forecast arrives after Apple shares closed at $330.32 on Oct. 1, up 21.50% year to date and 29.31% over the past 52 weeks.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
That strong run has raised the bar for Apple’s next product cycle, with investors also watching how newly appointed CEO John Ternus executes his first major product push, led by the iPhone Duo and the broader iPhone 18 lineup.
Can projected sales of 6 million iPhone Duo units generate enough incremental revenue and higher-end iPhone demand to push Apple stock further? Let’s break it down.
What 6 Million Duo Sales Mean for AAPL
Counterpoint Research's forecast that Apple could sell 6 million iPhone Duo units this year offers an early benchmark for demand for the company’s debut foldable. The forecast is especially notable because the Duo is scheduled to arrive in stores on Oct. 23, after preorders begin Oct. 16, following its unveiling alongside the iPhone 18 family in September. This gives Apple only a short selling window before the year ends.
The Duo starts at $1,999 and unfolds into a 7.6-inch display, placing it above Apple’s existing Pro models as the company’s most expensive iPhone. At that entry-level price, 6 million units would equal at least $12 billion in potential hardware revenue, excluding customers who opt for larger storage configurations.
That is a meaningful launch contribution, but it is unlikely to transform Apple’s financial outlook by itself. Apple reported quarterly revenue of $109.4 billion in its most recently reported quarter, meaning even $12 billion in gross Duo sales would be modest relative to the company’s overall revenue base.
The forecast matters because it could signal a new source of premium iPhone growth at a time when UBS sees broadly flat year-over-year wait times for the iPhone 18 Pro lineup. If the Duo attracts incremental upgrades, Apple could benefit from higher average selling prices and a stronger high-end product mix. If buyers merely shift from Pro and Pro Max models, the immediate financial benefit would be narrower.
Apple investors may view 6 million Duo sales as supportive of the company’s next product-cycle narrative, but the forecast alone is unlikely to drive a lasting rerating in AAPL stock. The market will need evidence that the Duo expands total iPhone demand, lifts average selling prices, and develops into a multi-year growth engine before treating it as a material stock catalyst.
Apple’s Strong Base Raises the Bar
Apple enters the Duo launch from a position of financial strength, which also explains why projected sales of 6 million units may not automatically move the stock. In its latest reported quarter, the company generated $109.4 billion in revenue, up 16.4% year over year and 1.1% above analysts’ $108.2 billion forecast. GAAP earnings per share reached $2.02, topping the $1.89 consensus estimate by 6.7%.
Apple’s profit engine improved as well. Gross margin rose to 50.1% from 46.5% a year earlier, operating margin expanded to 32.6% from 30.0%, and free-cash-flow margin increased to 29.2% from 26.0%. Services revenue totaled $30.7 billion, although it missed Wall Street’s $31.2 billion estimate by 1.5%.
Apple has started to broaden the Duo’s potential appeal beyond consumer upgrades. In September, Anterix (ATEX) said the iPhone 18 Pro and iPhone Duo were the first iPhone models able to operate on dedicated private LTE networks using Anterix’s 900 MHz spectrum. That enterprise capability broadens the Duo’s potential appeal beyond consumer upgrades, though its effect on Apple’s near-term unit sales remains uncertain.
What Wall Street Expects Next
Apple reports fiscal fourth-quarter results on Oct. 29. The consensus from Wall Street calls for $1.98 in earnings per share, up 7.03% from $1.85 a year earlier.
Morgan Stanley sees the product cycle as a positive development. Analyst Erik Woodring reiterated an “Overweight” rating and a $360 price target. That target implies 9.0% upside from Apple’s Oct. 1 closing price.
Woodring said Apple’s hardware and software innovation has become more compelling. He also described the latest lineup as “more exciting” and sees above-trend growth extending into fiscal 2027.
UBS presents the other side of the debate. Analyst David Vogt maintained a “Neutral” rating and a $296 price target, 10.4% downside from the Oct. 1 closing price.
He said the persistent decline in China's iPhone 18 Pro Max wait times could indicate that some buyers are waiting for the Duo. That supports the foldable’s early demand case, but it also raises the risk that Duo sales will replace Pro Max purchases rather than expand Apple’s total iPhone market.
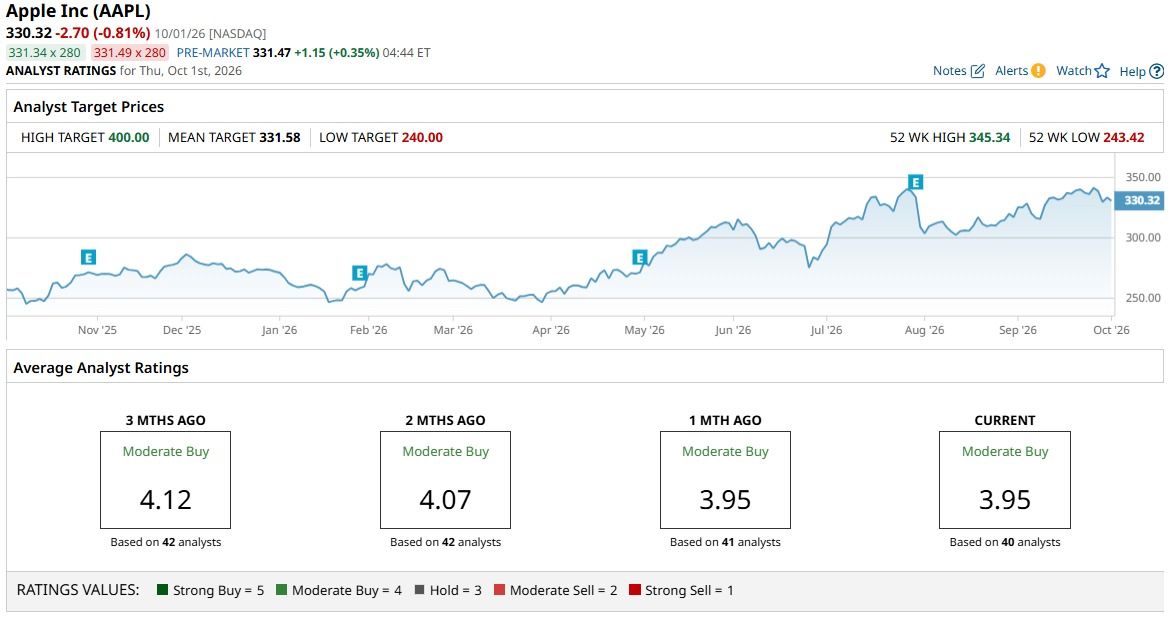
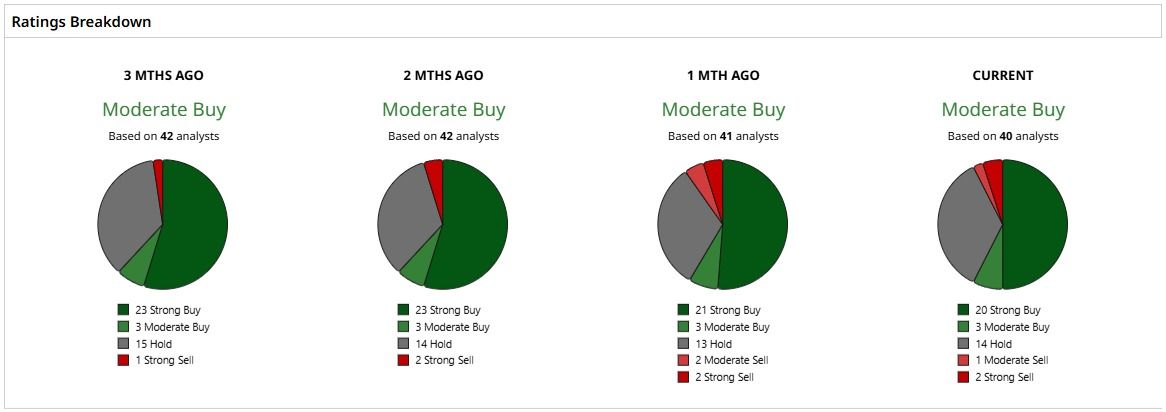
The consensus view is positive but less aggressive. Apple holds a “Moderate Buy” consensus rating from 40 analyst opinions. The average $331.58 price target implies only 0.4% upside. That small gap suggests investors have already priced in much of the expected good news.
 www.barchart.com
 www.barchart.com
Conclusion
Six million iPhone Duo sales would be a solid opening for Apple’s foldable strategy, but probably not enough to move AAPL stock meaningfully by itself. The device can lift iPhone pricing and give customers another reason to upgrade. Still, Apple needs clear evidence that Duo demand expands its premium customer base rather than shifts sales from Pro models. Shares are more likely to rise gradually if iPhone demand, Services growth, and Apple’s fiscal 2027 outlook remain strong.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Carnival Corp Generates Strong Free Cash Flow - What's the Best CCL Play Analyst Sees 6 Million iPhone Duo Sales This Year. Why That’s Not Enough to Move AAPL Stock. Netflix’s Own Co-CEO Just Warned of Slowing Growth Meta vs. Microsoft: One AI Agent Has a Problem the Other Doesn’t.