

Tractor Supply Company (TSCO), headquartered in Brentwood, Tennessee, operates as a rural lifestyle retailer. Valued at $16.3 billion by market cap, the company provides farm maintenance, animal, general maintenance, lawn and garden, light truck equipment, work clothing, and other products. The largest rural lifestyle retailer is expected to announce its fiscal third-quarter earnings for 2026 in the near term.
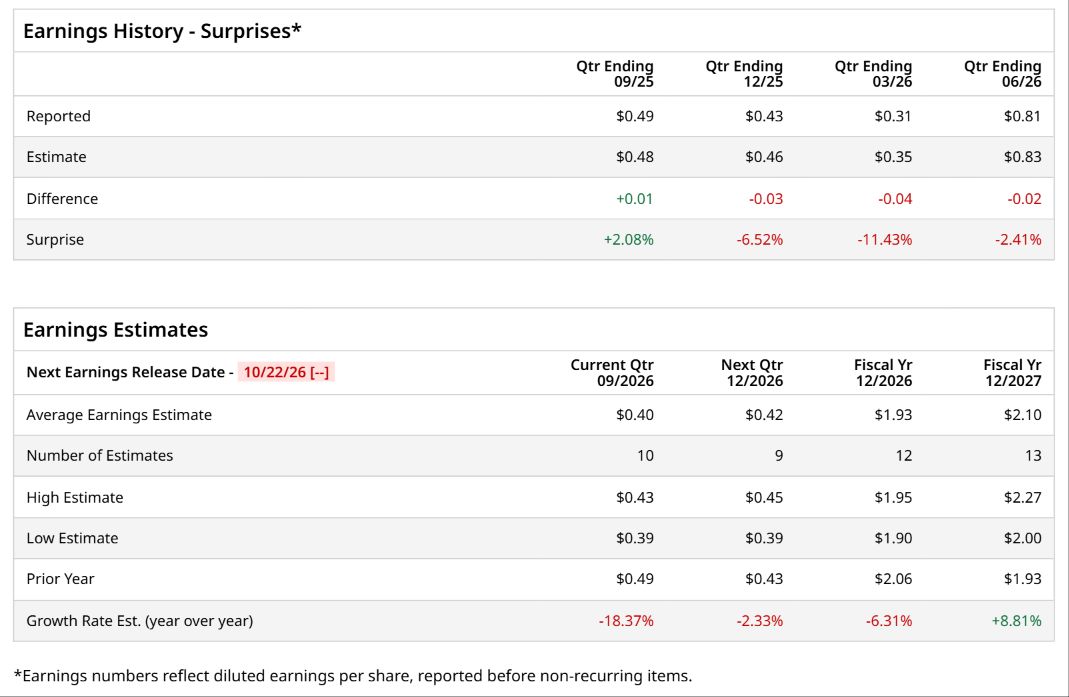
Ahead of the event, analysts expect Tractor Supply to report a profit of $0.40 per share on a diluted basis, down 18.4% from $0.49 per share in the year-ago quarter. The company missed the consensus estimates in three of the last four quarters while surpassing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Tractor Supply to report EPS of $1.93, down 6.3% from $2.06 in fiscal 2025. However, its EPS is expected to rise 8.8% year over year to $2.10 in fiscal 2027.
 www.barchart.com
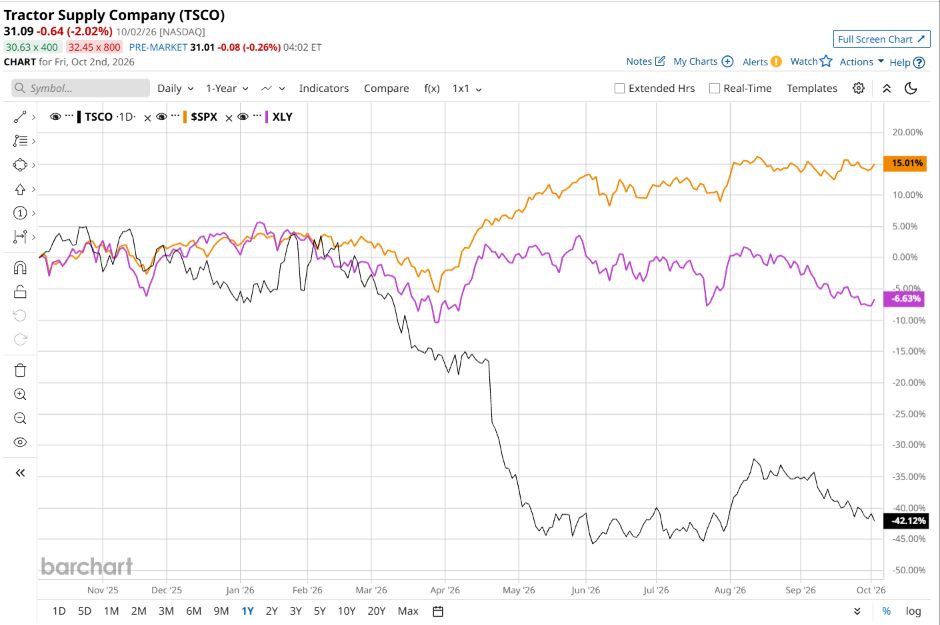
TSCO stock has considerably underperformed the S&P 500 Index’s ($SPX) 15% gains over the past 52 weeks, with shares down 44.7% during this period. Similarly, it notably underperformed the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) 8.1% losses over the same time frame.
 www.barchart.com
TSCO underperformed on weakness in discretionary and big-ticket categories, which CEO Hal Lawton blamed on higher fuel prices, drought in key regions, and an unusually soft May. That created a two-point comp drag despite resilient CUE categories like feed and staples. Looking ahead, guidance is cautious given rural spending pressure and pet/home improvement softness. Management is acting with 75 Petsense closures, a Freshpet rollout to 700+ stores, and the VIP Petcare acquisition to deepen its pet ecosystem.
On Jul. 23, TSCO shares closed up by 3.3% after reporting its Q2 results. Its adjusted EPS of $0.81 fell short of Wall Street expectations of $0.83. The company’s revenue was $4.5 billion, missing Wall Street forecasts of $4.6 billion. TSCO expects full-year adjusted EPS in the range of $1.90 to $2.
Analysts’ consensus opinion on TSCO stock is moderately bullish, with a “Moderate Buy” rating overall. Out of 29 analysts covering the stock, 13 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” 14 give a “Hold,” and one indicates a “Strong Sell.” TSCO’s average analyst price target is $36, indicating a potential upside of 15.8% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Nvidia Bull Put Spread Could Return 16% U.S. Stock Futures Slip as Europe’s Turmoil Weighs on Sentiment; Fed Minutes Awaited As Starship Finally Reaches Orbit, Here’s How You Should Place SpaceX Stock Chinese AI Chips Could Flood the Market. Alibaba’s New Chip Is 3X Better Than Its Predecessor.