

American Express Company (AXP), headquartered in New York, operates as an integrated payments company. With a market cap of $204.5 billion, the company’s principal products and services are charge and credit payment card products and travel-related services offered to consumers and businesses around the world. The credit card and banking giant is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Friday, Oct. 23.
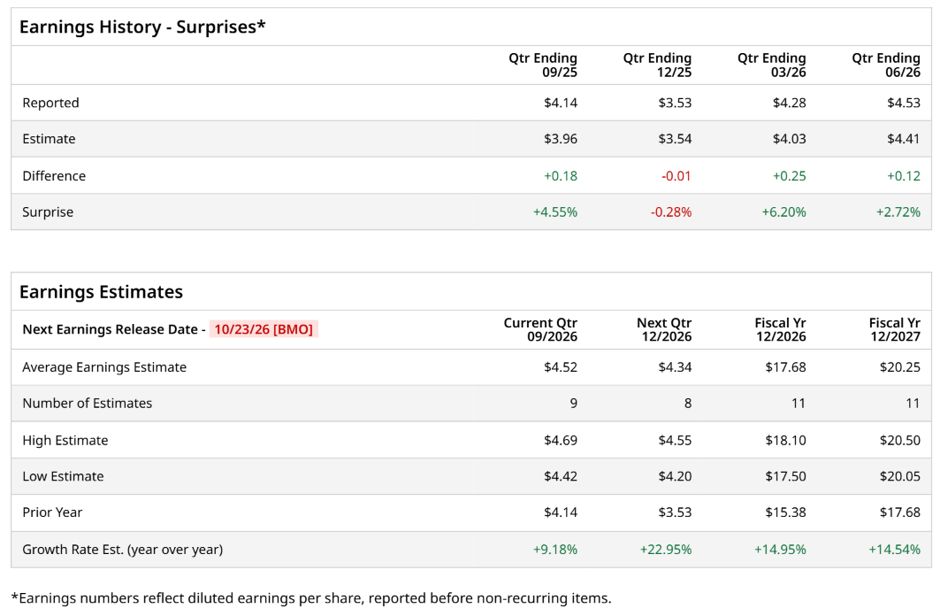
Ahead of the event, analysts expect American Express to report a profit of $4.52 per share on a diluted basis, up 9.2% from $4.14 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect American Express to report EPS of $17.68, up 15% from $15.38 in fiscal 2025. Its EPS is expected to rise 14.5% year over year to $20.25 in fiscal 2027.
 www.barchart.com
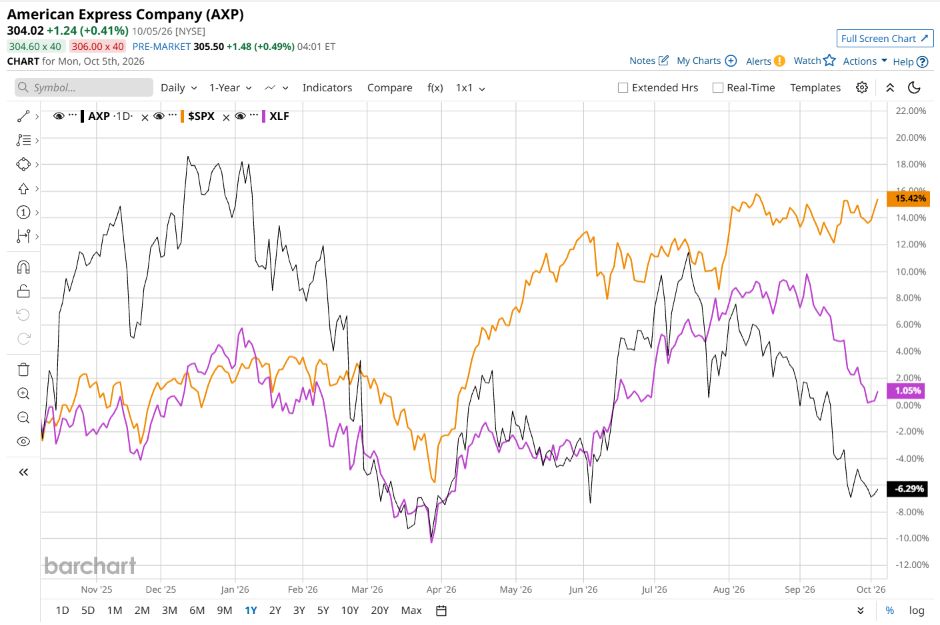
AXP stock has underperformed the S&P 500 Index’s ($SPX) 15.8% gains over the past 52 weeks, with shares down 7.9% during this period. Similarly, it underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) marginal returns over the same time frame.
 www.barchart.com
AXP underperformed primarily due to valuation compression and shifting macroeconomic expectations. While top-line fundamentals remained solid with double-digit revenue expansion and record card-fee growth, investors taking profits after a multi-year rally grew increasingly cautious over persistent inflation, elevated interest rates, and softening discretionary consumer spending. Furthermore, sentiment was tempered as management opted to aggressively reinvest operating upside into new cardholder acquisition, technology, and marketing initiatives, weighing on operating margin expansion, while maintaining a largely unchanged full-year earnings outlook rather than raising guidance.
Analysts’ consensus opinion on AXP stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 30 analysts covering the stock, 14 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” and 14 give a “Hold.” AXP’s average analyst price target is $375.50, indicating a notable potential upside of 23.5% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This High-Yield Shipping Stock Just Raised Its Dividend by More Than 11% Elon Musk Just Gave TSMC Stock a Big Boost A $22.6 Billion Reason Why Autodesk Stock Is Up Today Trump Looks Set to Give Vistra Stock a $4 Billion Boost