

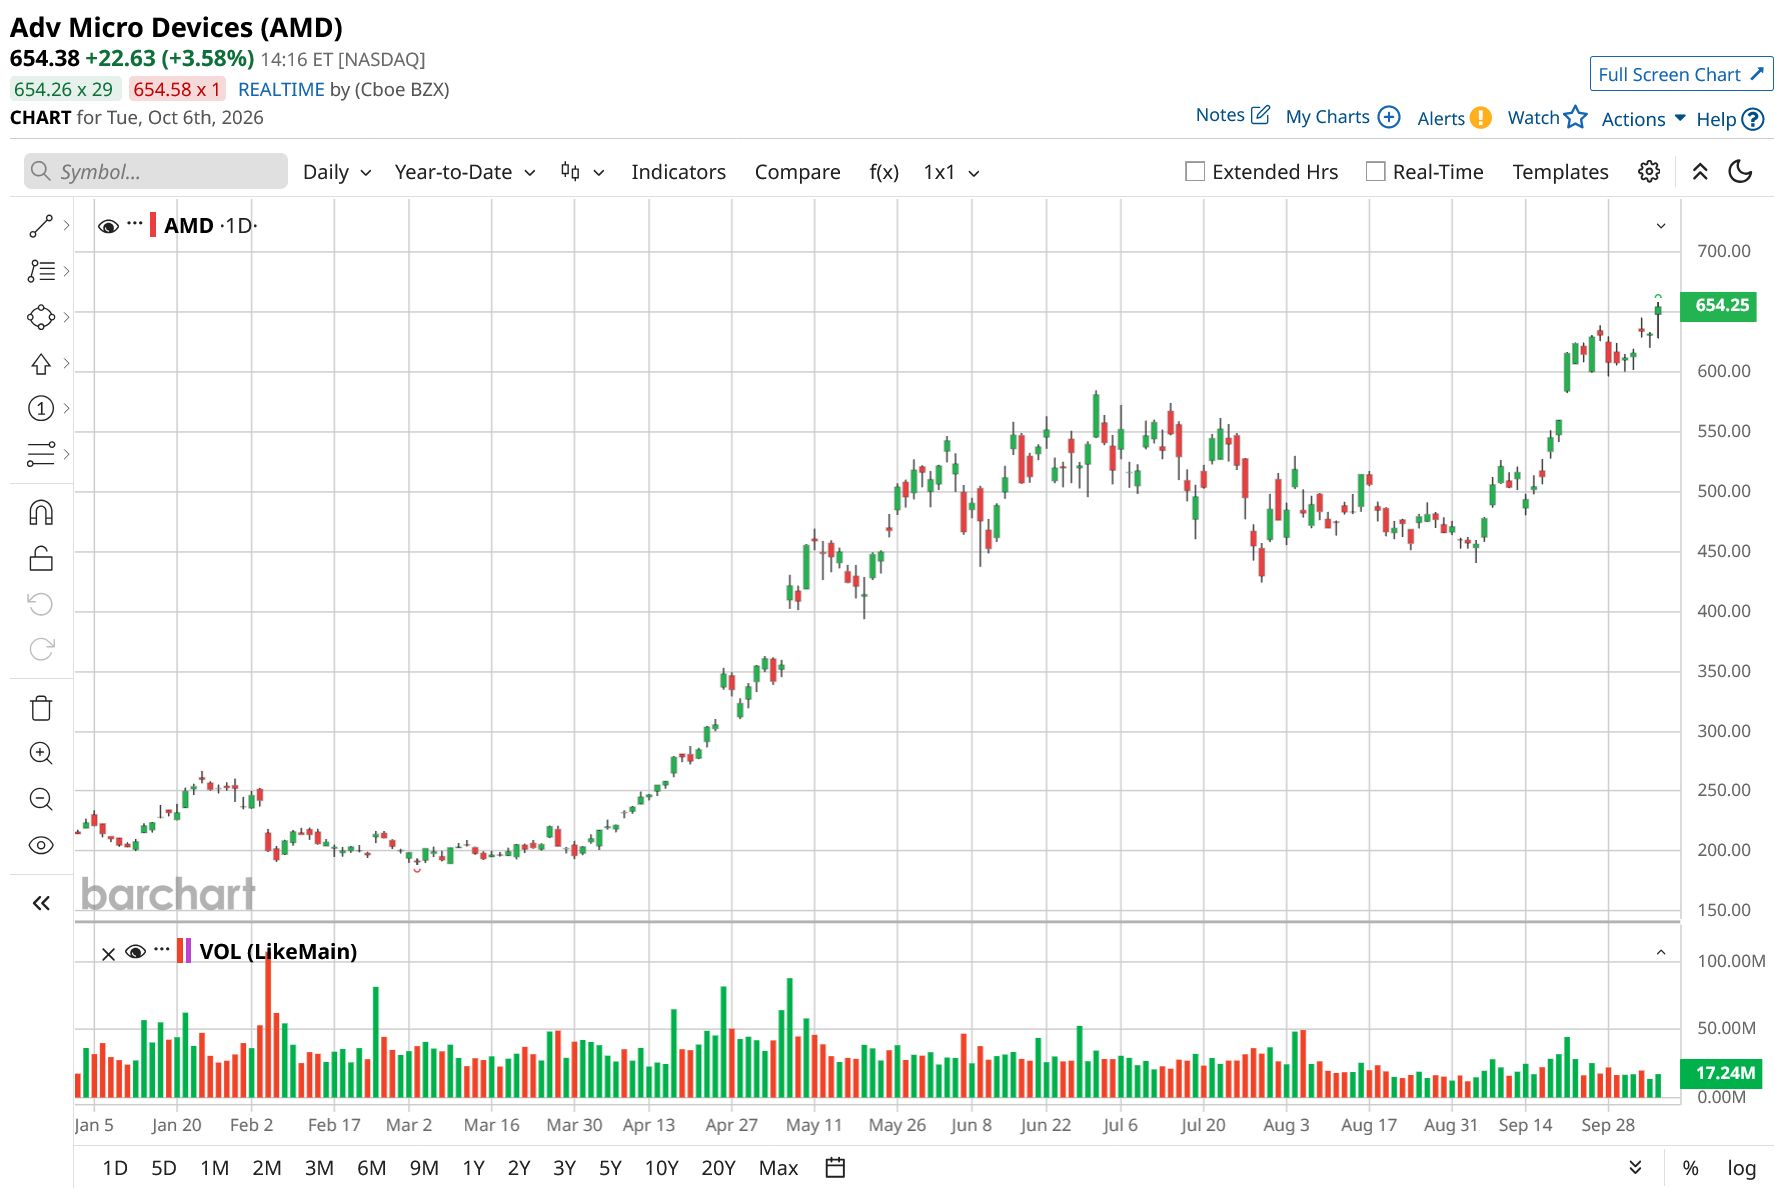
Advanced Micro Devices' (AMD) stock has rallied about 37% over the past month, hitting an all-time high of $658.52 during today's trading. Its market value topped $1 trillion for the first time on Sept. 21, when shares jumped about 10% in one session. The stock is now up more than 206% this year. Two developments drove the latest surge. Meta’s (META) new Muse AI agent became a hit, raising hopes for server CPU demand. Earlier in the month, CFO Jean Hu also said AMD expects its data center business to double in 2027 to about $70 billion. After a run like this, the question everyone’s asking is whether anything is left. I think there is, for three reasons, but let's first look at how AMD got here.
About AMD Stock
Advanced Micro Devices is a semiconductor company that designs high-performance chips for data centers, PCs, and gaming. Its product portfolio includes EPYC server CPUs and Instinct AI GPUs, which drive its data center growth, along with Ryzen processors. Founded in 1969, the company is headquartered in Santa Clara, California, and is led by CEO Lisa Su.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Year-to-date (YTD), AMD’s stock has climbed 206%, comfortably outperforming the VanEck Semiconductor ETF’s (SMH) 85% gain during the same period. Surging data center sales and rising AI-driven CPU demand pushed it to an all-time high of $658.52 today, Oct. 6.
 www.barchart.com
AMD Beats Estimates as AI Demand Runs Ahead of Expectations
AMD reported its second-quarter 2026 earnings on Aug. 4. Revenue rose 50% year-over-year (YoY) to a record $11.54 billion, beating the $11.28 billion consensus. Non-GAAP EPS of $1.66 also topped the $1.62 estimate. Non-GAAP gross margin expanded to 56%. CEO Lisa Su said demand for both AI accelerators and CPUs is growing well above prior expectations.
For the third quarter, AMD guided revenue to about $13 billion, plus or minus $300 million, above the $12.52 billion analysts expected. The midpoint implies 41% YoY growth. Su also said server revenue should grow more than 80% in the second half of 2026. Management now expects long-term revenue growth well above its prior target of over 35%. It also expects to comfortably beat its long-term $20 EPS target.
Management certainly seems confident in AMD's future growth despite already hitting the $1 trillion milestone, but here are my three reasons why I also see more room in the tank for AMD stock:
Reason 1: The 2027 Growth Is Already Mapped Out
Data center revenue more than doubled to $6.7 billion last quarter, making up 58% of total sales. Management expects the segment to more than double again in 2027. The MI450 GPU and Helios racks began shipping in the third quarter, with a much bigger step-up expected in the fourth. To me, that matters more than any long-term market forecast because it shows what AMD expects to actually sell.
Reason 2: AI Agents Are Turning CPUs Into an AI Business
I think the market is still underestimating this part. AI agents lean heavily on CPUs to run tasks and coordinate workflows. Muse gives each user a dedicated virtual machine, reportedly hosted on AMD EPYC servers. AMD now sees the server CPU market reaching $220 billion by 2030, up from the $60 billion it projected last November. It also expects its own server CPU revenue to grow over 70% in 2027. Nebius (NBIS) is even raising rental rates on some AMD EPYC CPUs by 25%, a clear sign of pricing power.
Reason 3: Earnings Growth Brings the Valuation Down Fast
At first glance, AMD’s valuation looks stretched. The forward GAAP price-to-earnings (P/E) of 110.59x sits about 14% above its 5-year average of 97.40x. The forward price-to-sales (P/S) ratio of 20.31x is even steeper, sitting more than double its average of 8.63x. But the reason investors are willing to pay up is the growth outlook. Analysts expect earnings to grow about 82% in 2026, 106% in 2027, 44% in 2028, and 40% in 2029. That is an exceptional trajectory for a company worth over $1 trillion. Based on 2027 earnings, the P/E drops to roughly 54x and to about 37x by 2028. AMD also holds about $8.8 billion more cash than debt. Overall, I think the price is justified if AMD delivers the way analysts expect it to.
AMD is obviously not cheap anymore. Still, with demand mapped out through 2027 and CPUs becoming a new AI driver, I see room for the stock to keep climbing.
What Do Analysts Expect for AMD Stock?
On Oct. 5, Stifel raised its price target on AMD stock from $635 to $700 and kept a “Buy” rating, arguing that AI demand is outpacing the industry's ability to supply chips. That lines up with AMD's own view that demand is running ahead of expectations. On the same day, Mizuho Securities also raised its price target from $580 to $705 and kept a “Buy” rating.
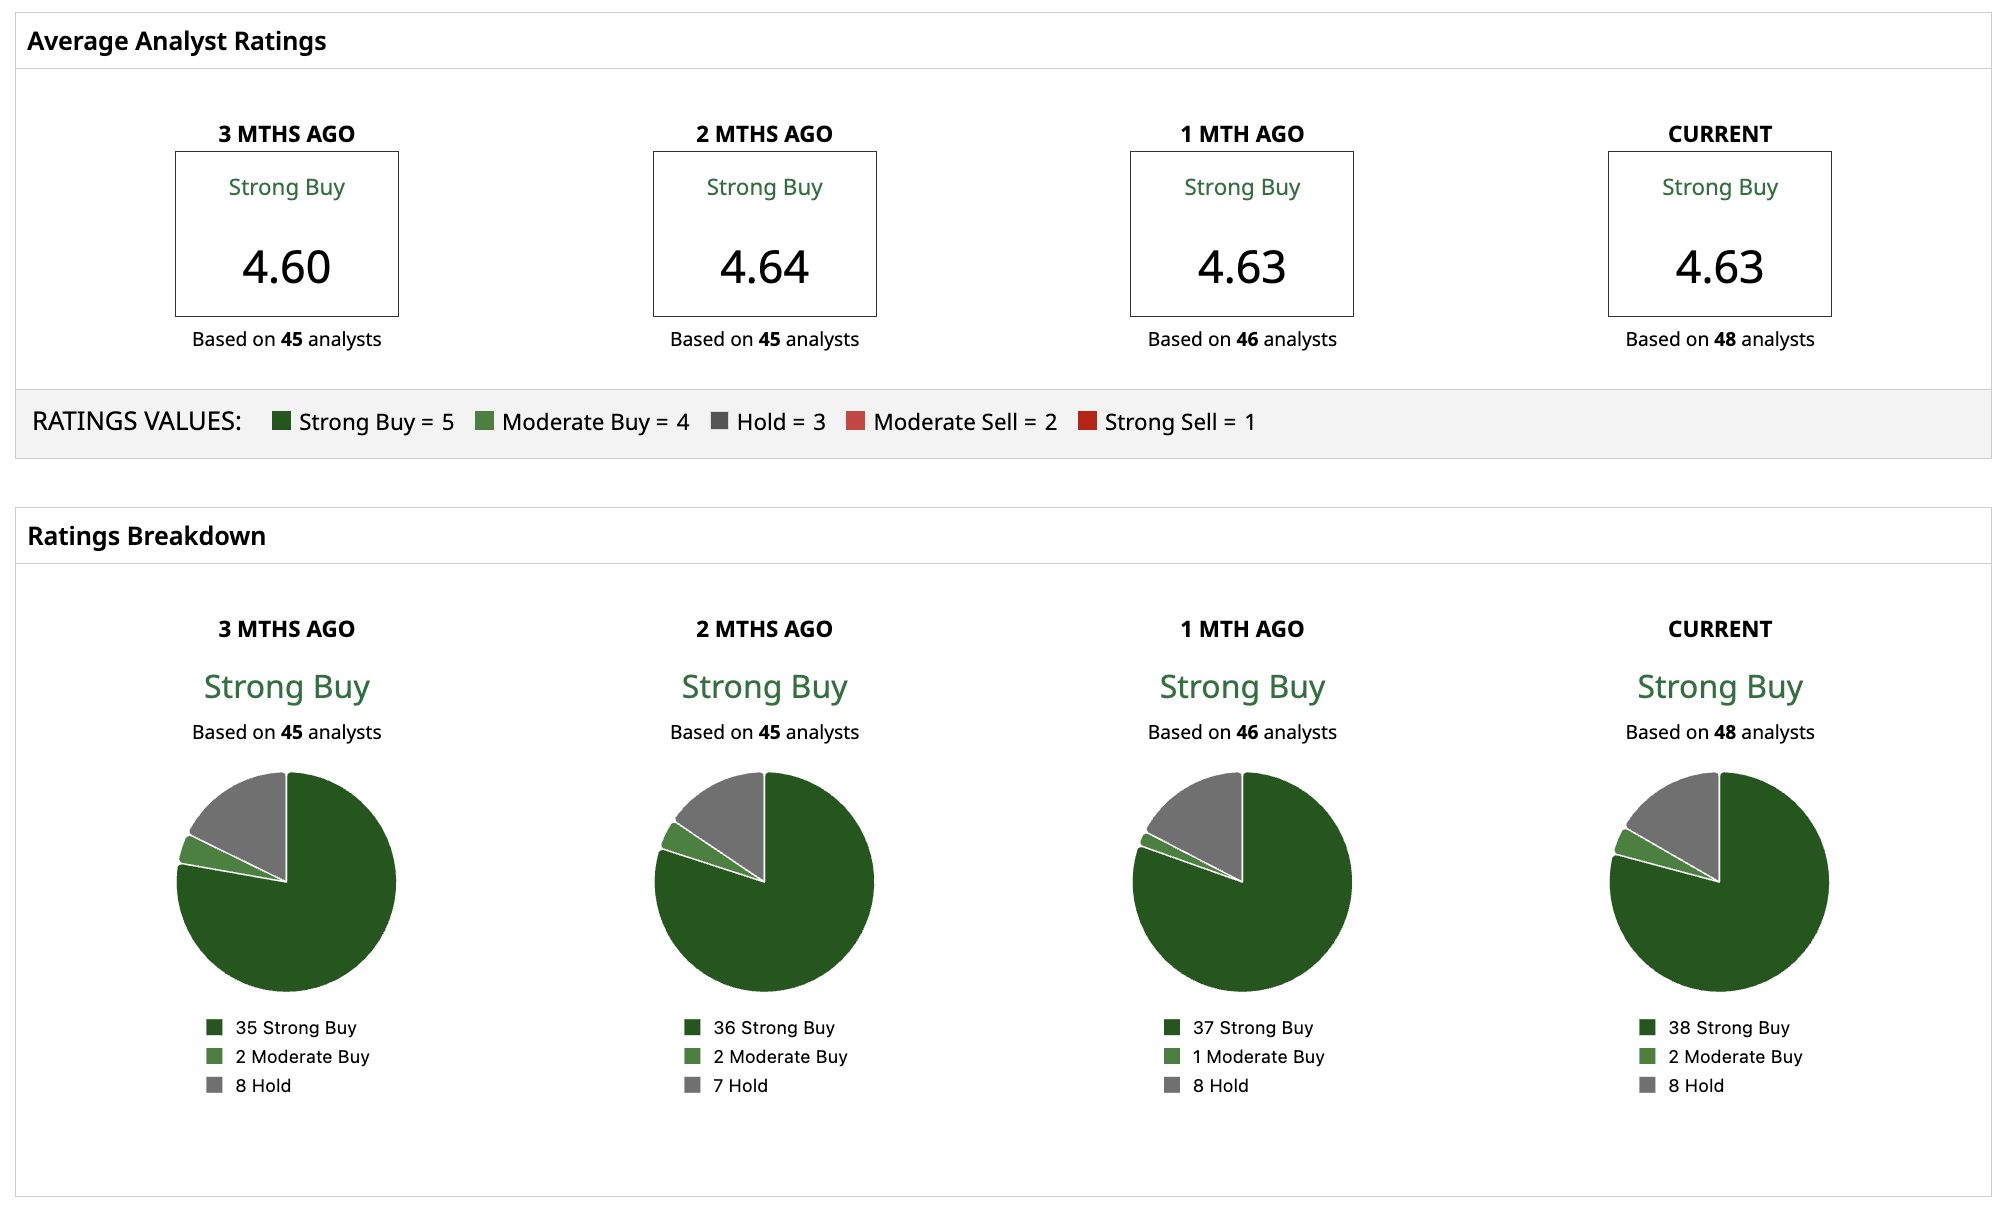
Based on 48 Wall Street analysts, AMD stock holds a “Strong Buy” consensus rating with a mean price target of $630.70. After its recent rally, the stock now trades slightly above that target. With firms like Stifel and Mizuho raising their targets, the average may need to catch up.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
3 Reasons Why You Should Still Buy AMD Stock at a $1 Trillion Valuation MRVL Stock Jumps After Marvell Technology Raises Long-Term Guidance MU Stock Alert: What to Know as Micron, Netlist Reach $600 Million Patent Settlement Howard Hughes Holdings Shows Huge, Unusual Out-of-the-Money Put Options Trading - Investors Bullish on HHH