

Michael Burry became famous for doing what few investors had the stomach to do: looking where everyone else was looking away from. The investor behind Scion Asset Management famously bet against the housing market before the 2008 financial crisis, a trade immortalized in “The Big Short.” So, when Burry makes a move, investors tend to pay attention, even when that move is less about making a big directional bet and more about playing the tax calendar.
In his Oct. 5 Substack post, Burry outlined how he is positioning his portfolio ahead of the fourth-quarter tax-loss harvesting season, saying he tries to “beat the rush” before selling pressure peaks between late October and early December. Among six stocks he identified as likely tax-loss sale candidates was Lululemon Athletica (LULU).
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
That brings us to what Burry calls a “proxy swap.” Simply put, it means selling one stock while temporarily buying another similar company to maintain exposure to the same broader industry or investment theme. The trick is to avoid buying back the same or a substantially identical security during the IRS’s 30-day wash-sale window while still keeping some skin in the game.
That is precisely what Burry has done with LULU and Deckers Outdoor Corporation (DECK). He says he remains bullish on LULU over the long term but swapped his LULU shares for DECK as a proxy, expecting many of the forces that could help LULU recover to benefit DECK as well. And he happens to like Deckers in its own right.
Best known for brands such as UGG and HOKA, Deckers’ shares have delivered impressive returns over the past two decades, yet DECK stock is in the red this year amid margin pressure, tariff concerns, and weakness across athletic footwear. With the stock now trading at a more attractive valuation, Burry’s move is certainly worth a closer look. So, what does he see in Deckers? Let’s dive in.
About Deckers Outdoor Stock
From California to closets worldwide, Deckers has spent more than five decades turning niche footwear ideas into globally recognized names. Based in Goleta, California, the company designs, markets, and distributes footwear, apparel, and accessories built for everything from everyday comfort to high-performance pursuits. Its brand family includes UGG, HOKA, and Teva, each carving out its own loyal following across different corners of the footwear market.
Today, Deckers' products reach consumers in more than 50 countries through specialty and department stores, company-owned retail locations, and online channels. While the brands have grown far beyond their niche beginnings, Deckers remains focused on strengthening its premium portfolio, deepening customer connections, and executing its long-term strategy with discipline. Its market capitalization is approximately $11.1 billion.
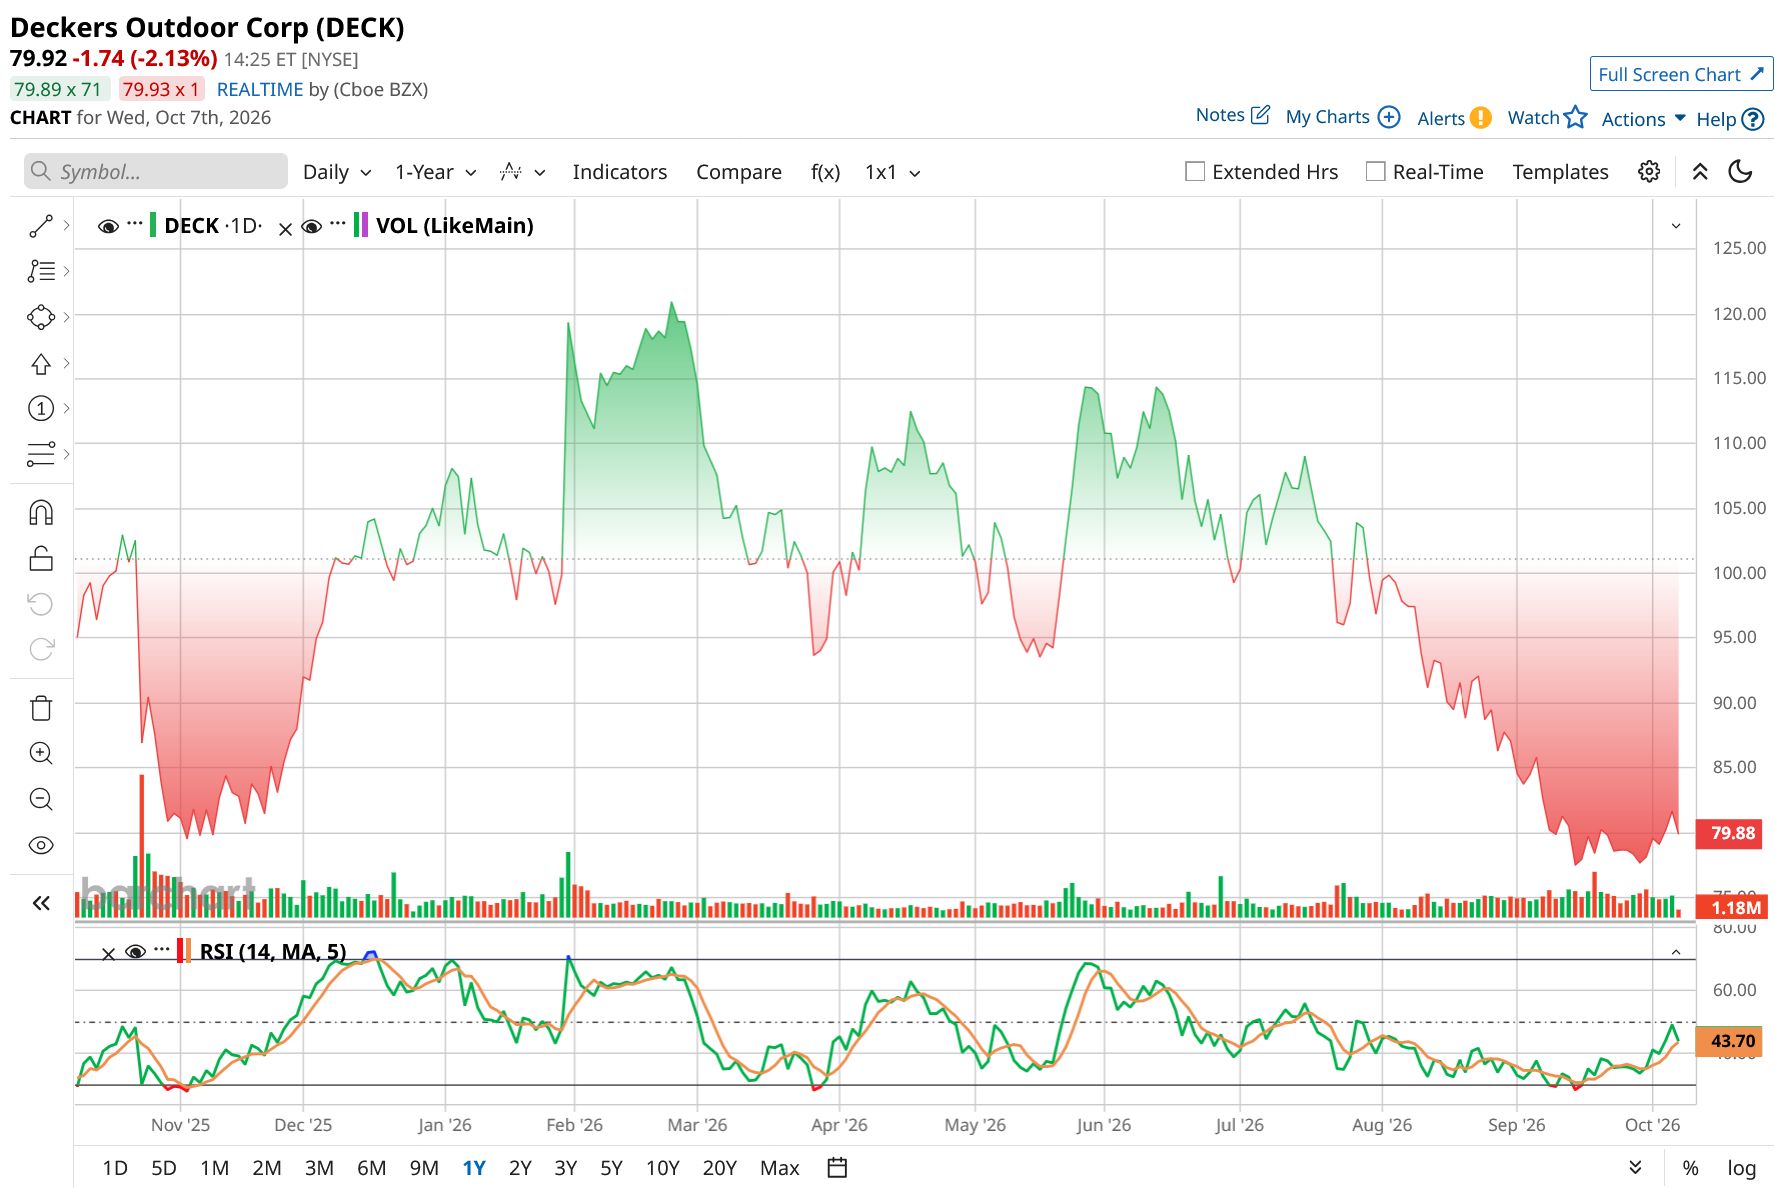
DECK has had one heck of a run over the long haul. Over the past two decades, the stock has delivered a whopping 2,664.5% return, while investors who bought a decade ago are sitting on an 838.8% gain. But 2026 has been a very different story. Shares are down 18% this year, with the pressure getting worse over the past six months and three months, when DECK slipped 20% and 25%, respectively.
Tariff worries, cautious consumer spending, and broader weakness across athletic footwear have clearly taken some shine off the stock. Even a solid Q1 report, which beat earnings and revenue estimates and raised the fiscal 2027 EPS outlook, failed to keep investors happy. Concerns over tariffs and freight costs sent shares down another 6% following the results.
DECK stock eventually hit a 2026 low of $77.20 on Sept. 30. But perhaps the tide is starting to turn. Despite some weakness today, shares have climbed 2.5% over the past five trading sessions, while the 14-day RSI has recovered to 44 after dipping into oversold territory in September. For now, the stock may finally be showing signs of waking up.
Valuation-wise, DECK looks attractive. The stock trades at just 10.86x forward adjusted earnings, below several sector peers and its own historical average. Its 1.89x price-to-sales (P/S) ratio is above the sector average, but still below where DECK has typically traded. Not exactly bargain-bin pricing, but certainly more tempting.
 www.barchart.com
A Closer Look at Q1 2027 Earnings Results
Deckers’ fiscal first quarter numbers were pretty decent. In July, the company posted its first-ever June quarter with more than $1 billion in revenue, with earnings and sales beating consensus estimates. EPS came in at $0.94, up 1.1% year-over-year (YoY), while net sales climbed 5.7% to $1.02 billion, or 4.8% on a constant-currency basis.
The growth story still revolves around its two biggest stars: HOKA and UGG. HOKA remained the clear engine, with sales rising 7.7% to $703.5 million, helped by a 17% jump in DTC revenue and strong demand across the U.S., Europe, China, and Japan. Clifton, Bondi, Speedgoat 7, Mach 7, and other franchise families all contributed, while the early response to Clifton Pro gave management another reason to stay optimistic.
UGG sales grew 4.9% YoY to $278 million, supported by wholesale and DTC demand, particularly in Asia. Its 365, men's, and lifestyle initiatives are also helping push the brand beyond its traditional seasonal image.
Geographically, international sales were particularly encouraging, rising 8.4% to $502.1 million, compared with a 3.2% increase domestically to $517.4 million. Meanwhile, gross profit increased 6.9% to $575.2 million, with gross margin expanding 60 basis points to 56.4%. Deckers also ended June with $1.6 billion in cash and no debt, giving it plenty of financial breathing room. The company repurchased about 3.3 million shares for $338.2 million, with roughly $4.7 billion still available under its buyback authorization.
For the second quarter, management expects growth to remain steady, but margins could take a hit. Consolidated revenue is expected to rise about 5% YoY, with HOKA growing at a high-single-digit rate and UGG at a mid-single-digit pace. However, higher tariffs and freight costs are expected to pressure gross margin, while elevated investments in brand-building, technology, and marketplace expansion keep expenses higher. EPS is projected to be between $1.73 and $1.78.
For fiscal 2027, Deckers expects revenue to be between $5.86 billion and $5.91 billion, with the top-line growth to accelerate in the second half, helped by HOKA and normalization in international wholesale and distributor shipment timing. The company also raised its fiscal 2027 EPS guidance to $7.35 to $7.50, while expecting gross margin to be slightly above 56.5%.
Wall Street analysts tracking Deckers Outdoor project its Q2 EPS to be $1.82, while revenue is expected to rise to $1.5 billion. For fiscal 2027, EPS is anticipated to surge 6.8% YoY to $7.50 and then rise by another 10.9% annually to $8.32 in fiscal 2028.
What Do Analysts Expect for DECK Stock?
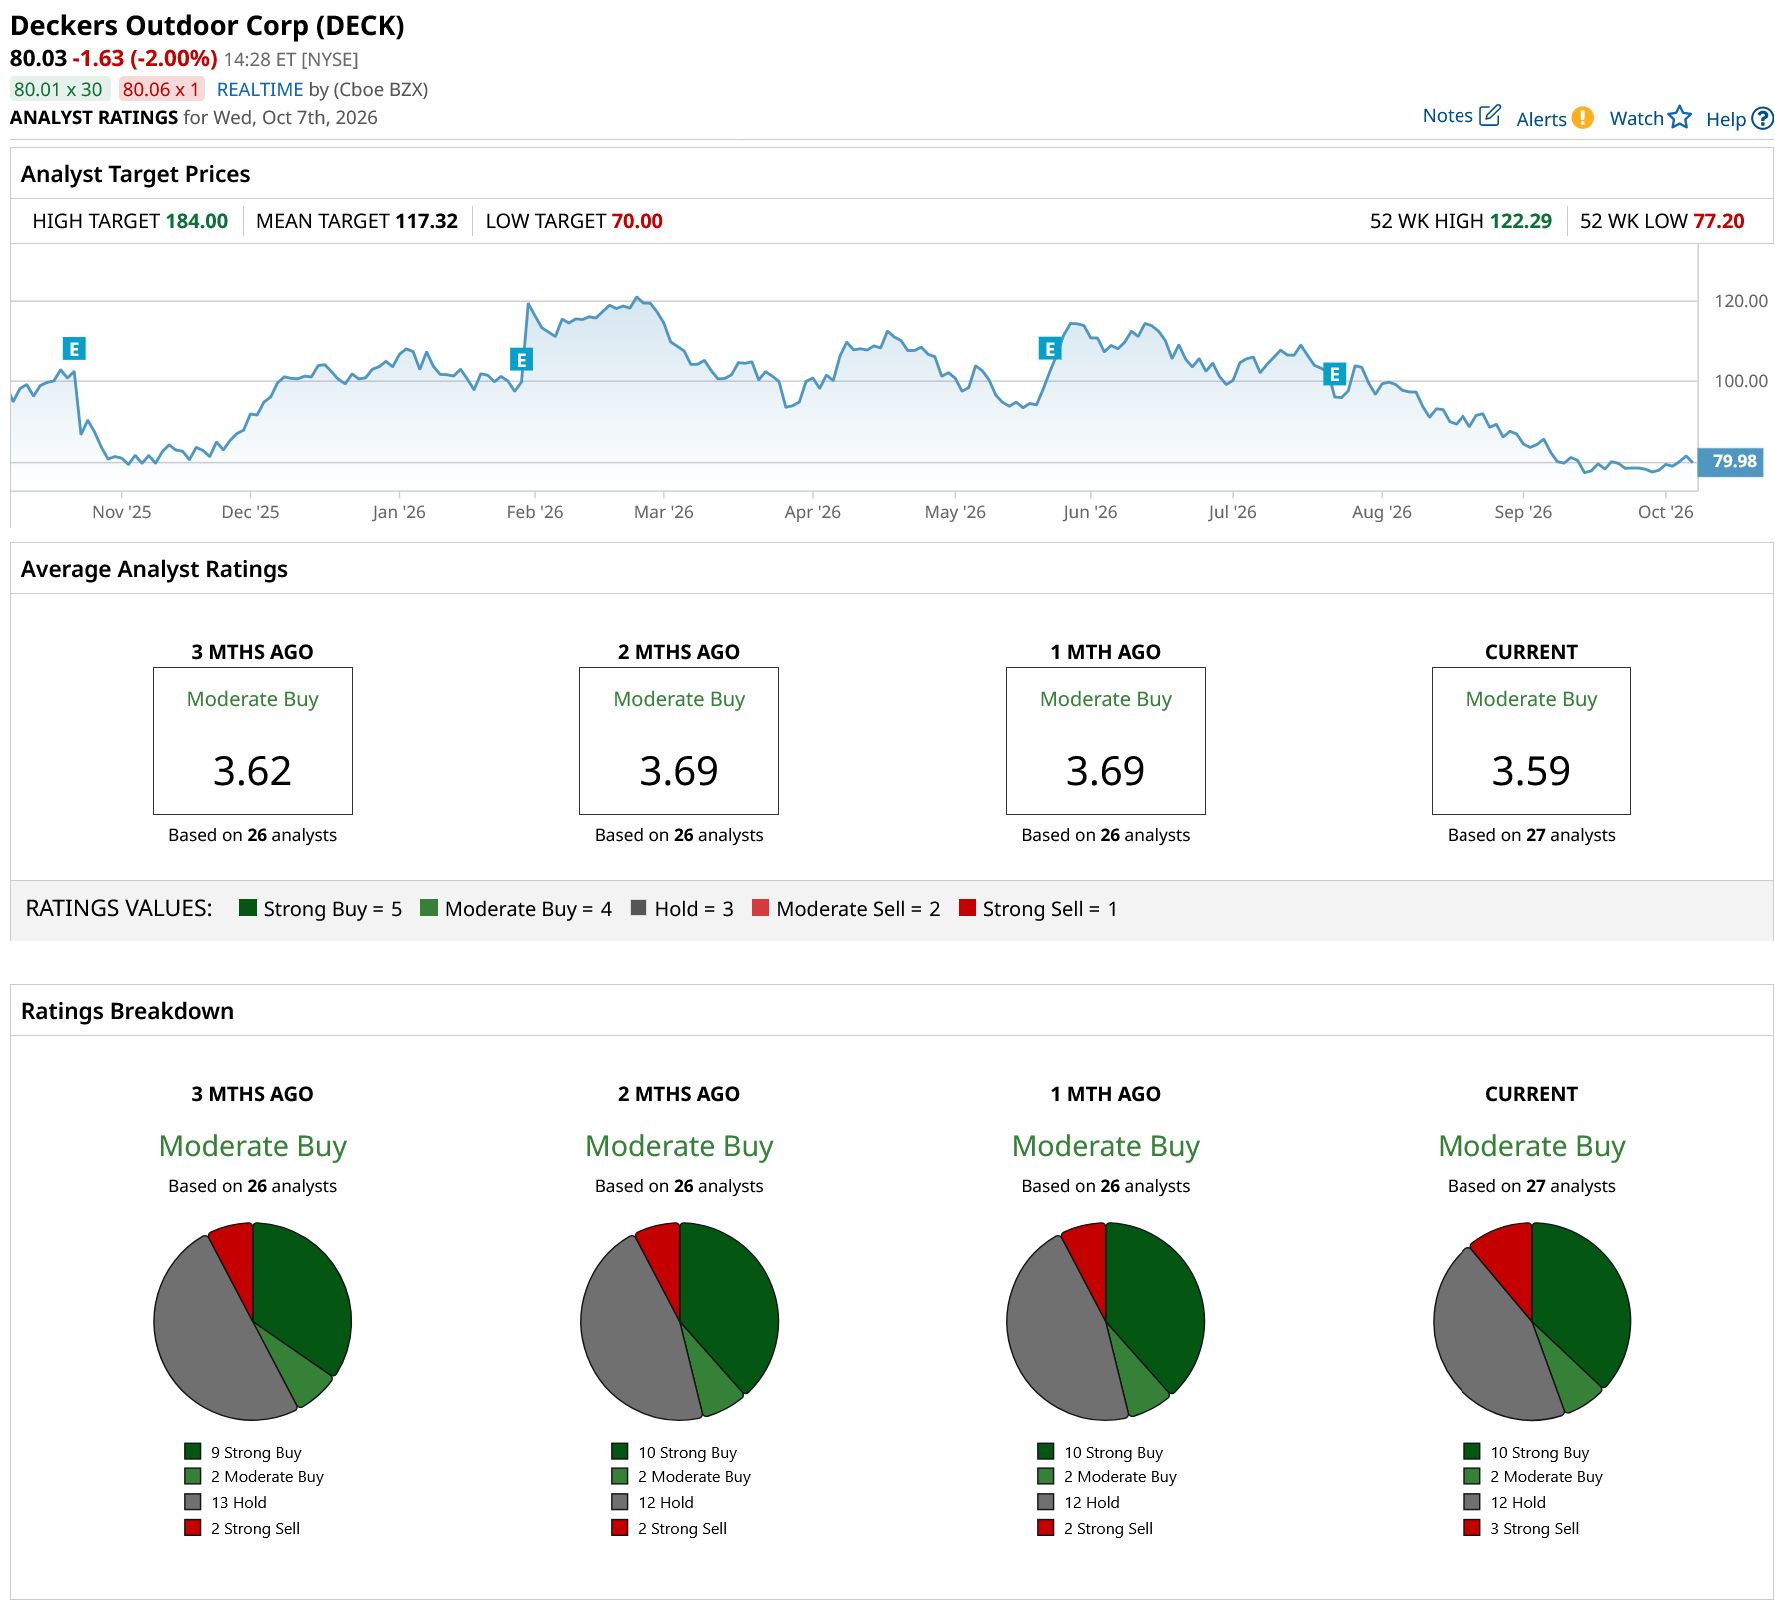
The consensus rating on DECK remains at “Moderate Buy,” from the 27 analysts covering the stock. Of those, 10 recommend a “Strong Buy,” two have a “Moderate Buy,” and 12 analysts are playing it safe, advising a “Hold” rating, while the remaining three are outright skeptical, suggesting a “Strong Sell.”
Wall Street sees plenty of room for DECK to bounce. The average price target of $117.32 points to a potential upside of 47% from current levels. And if the most bullish analyst gets it right, the $184 target suggests a whopping 130% gain.
 www.barchart.com
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Netlist Stock Is Up 970% Over the Past Year, But Its Latest $600 Million Win Suggests Caution Is the Right Approach WeBull Stock Sinks as Congress Flags National Security Risk Why Michael Burry Just Took a New Position in Deckers Outdoor Stock HubSpot Just Cut 7% of Its Workforce. How to Play HUBS Stock Here.