

Waste Management, Inc. (WM), valued at a market cap of $83.1 billion, provides environmental solutions to residential, commercial, industrial, and municipal customers. The Houston-based environmental services giant, which provides everything from waste collection and recycling to resource recovery and waste-to-energy solutions,
WM is heading into its third-quarter earnings report after the market closes on Tuesday, Oct. 27.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
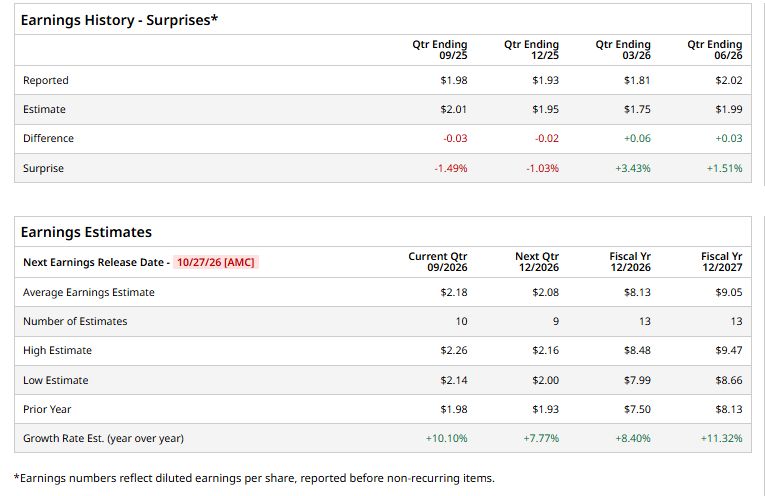
Ahead of the event, analysts expect WM to report a profit of $2.18 per share on a diluted basis, up 10.1% from $1.98 per share in the year-ago quarter. The company beat the consensus estimates in two of the last four quarters while missing the forecast on two other occasions.
For the current year, analysts expect WM to report EPS of $8.13, up 8.4% from $7.50 in fiscal 2025. Its EPS is expected to rise 11.3% year over year to $9.05 in fiscal 2027.
 www.barchart.com
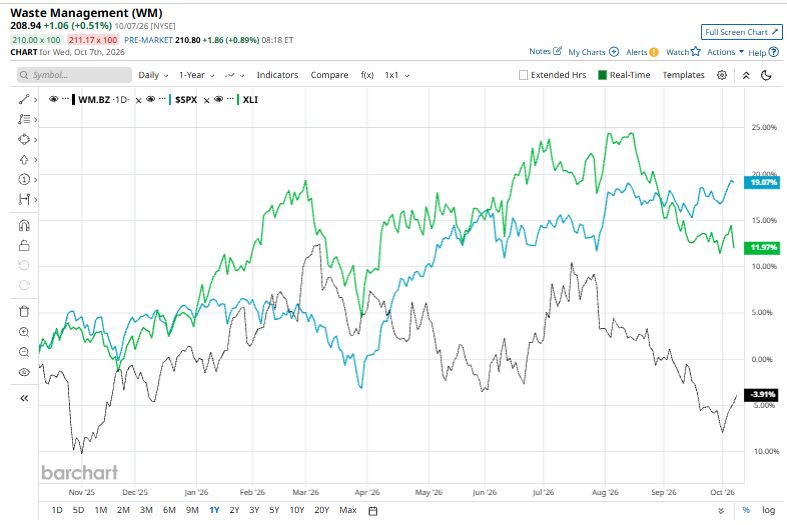
WM has struggled to keep pace with the broader market over the past year. Its Shares have declined 4% over the past 52 weeks, a notable contrast to the 16.2% gain for the S&P 500 Index ($SPX) and the State Street Industrial Select Sector SPDR ETF’s (XLI) 8.8% gains over the same time frame.
 www.barchart.com
WM’s stock has faced a tougher road over the past year, with sluggish waste volumes, softer recycling prices, and rising operating expenses weighing on investor sentiment. Although the company’s earnings remain on a solid growth trajectory, these headwinds have made it harder for WM to match the broader market’s stronger gains.
Analysts’ consensus opinion on WM stock is reasonably bullish, with an overall “Moderate Buy” rating. Of 28 analysts covering the stock, 18 rate it a “Strong Buy,” one suggests a “Moderate Buy,” and nine give a “Hold.” WM’s average analyst price target is $259.65, indicating a potential upside of 24.3% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
BofA Just Sent a Warning Shot for Apple Investors Why Nvidia Stock Is Worth Buying Before It Touches $327 Dear JPMorgan Stock Fans, Mark Your Calendars for Oct. 13 How to Play Rubrik Stock at New All-Time Highs