

Barclays has delivered a fresh warning to Hewlett Packard Enterprise (HPE) investors: even a booming business can become a less attractive investment when its stock price rises too far, too fast.
Barclays downgraded Hewlett Packard Enterprise to Equal Weight from Overweight on Oct. 14, 2026. The firm cut its price target to $77 from $83, with analyst Tim Long making no changes to his financial forecasts.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
He framed this as a pure valuation call. "While we like the networking exposure, we see the improved mix as reflected in the current valuation," Long wrote. The downgrade also flagged potential pressure on HPE's server and storage business as memory prices normalize.
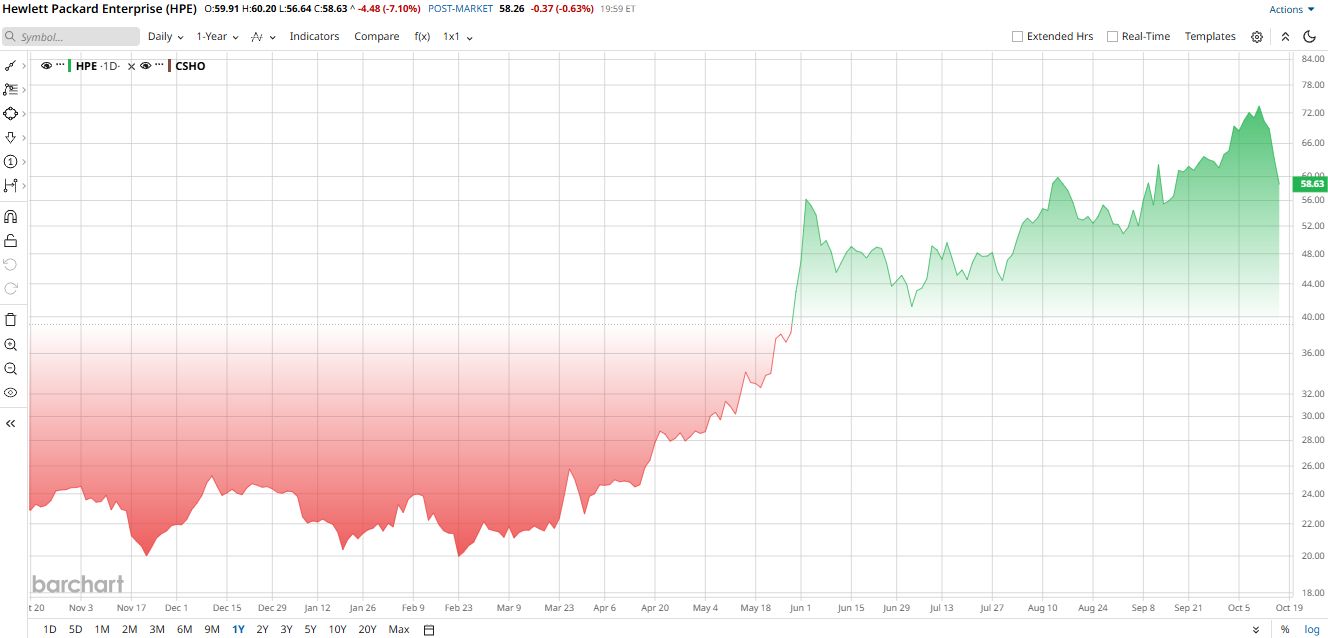
After rallying roughly 145% this year, HPE shares fell about 8% Wednesday and another 7% Thursday as investors reassessed the outlook for AI hardware stocks.
 www.barchart.com
The Rally Has Changed the Investment Case
HPE's improvements come after a big change for the company. Its Juniper Networks acquisition has bolstered its networking business with more presence in data-center infrastructure and equipment to connect AI servers. Reporting on Barclays' assessment shows that networking has massively grown its contribution to operating profit, representing about 50% of the total.
The new figures help to account for investor enthusiasm. HPE earned record revenue of $12.2 billion for its fiscal third quarter, which ended July 31, a 34% increase over the same quarter last year. Networking revenue grew 74.9% to $2.9 billion, and Cloud & AI revenue grew 25.4% to $9 billion. Server revenue grew 35.3% to $6.8 billion. The growth trend illustrated that these numbers don't only reflect HPE's growth in one product category.
Strong Results Have Raised Expectations
Profitability also improved. Operating profit jumped 155% from a year ago, and profit was at $1.02 per share, beating the lower end of management's guidance range of $0.82. The company's free cash flow was $1 billion, while HPE had $6.2 billion in cash and cash equivalents.
CEO Antonio Neri said that the company's results showed the “durability of our profitable growth momentum.” He also said that AI would be a “multi-year growth driver” for HPE.
Management has raised its fiscal 2026 revenue growth guidance from 25% to 29% and projected networking revenue growth of 72% to 75% — the expectations back up the case for further expansion of HPE. But, as with all things, high forecasts don't necessarily mean that the stock is cheap.
Memory Prices Are at the Center of Barclays' Warning
I suppose the concerning thing is what will happen once the tailwinds of hardware sales start to wane. Reported sales are higher as buyers are willing to pay more for increased memory and component prices. That bump may fade if prices for memory products remain steady or fall, which would make it more difficult to achieve comparable growth if demand does not increase significantly.
Barclays also asked if the spending on enterprise AI has hit a meaningful turning point. But at this point, the firm has not detected a “meaningful AI inflection” in the enterprise market, Long said. While companies can still invest in AI, it's possible spending on their own infrastructure could be below expectations embedded in hardware stocks.
Barclays has also lowered its valuation multiple for HPE's projected fiscal 2028 earnings from 14x to 13x. This is just an example: A firm can turn in its projections, but get pressured all the same by a shrinking market for future growth.
Wall Street Still Sees Potential Upside
Barclays is more cautious than several other firms. Goldman Sachs maintained a Buy rating while raising its price target to $80 from $75 on Oct. 6. Citigroup lifted its target to $92 from $76, while Morgan Stanley raised its target to $72 from $67 and retained its Overweight rating. Daiwa also upgraded HPE to Outperform with a $75 target earlier in October.
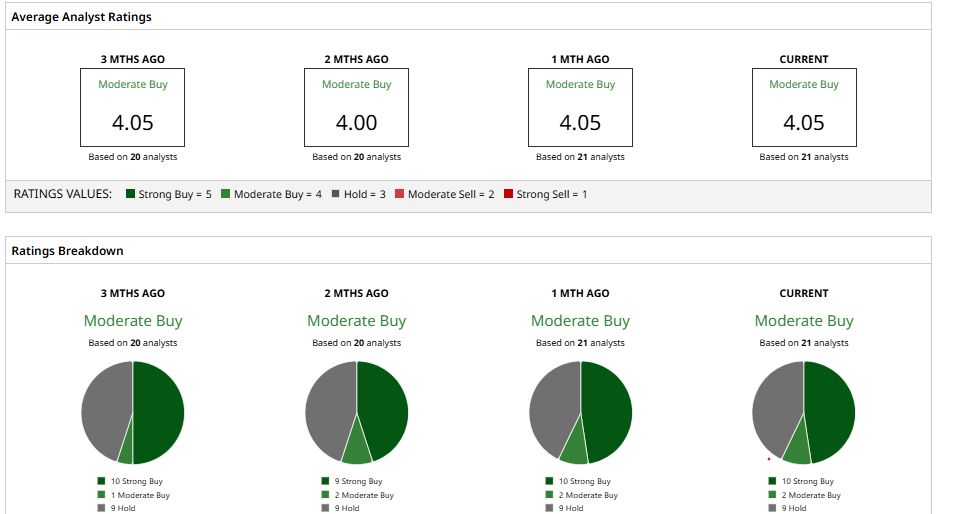
Based on 21 analyst recommendations, the analyst consensus for HPE is “Moderate Buy” according to data from Barchart. The group comes up with an average price of $73.50. That average suggests roughly 26% upside from the $58.26 price after Thursday's slide, but it can lag pronounced market moves.
The split on Wall Street is between valuation and execution. While HPE's results and outlook remain solid, Barclays is not sure how much of the progress has been priced in by the market. Investors are now observing whether memory price tailwinds can continue or will start dampening the demand for AI infrastructure.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
HPE Stock Alert: Barclays Just Delivered A Stark Warning After 145% Rally Lam Research Releases Its Fiscal Q1 Results Next Week - What's the Best LRCX Play? Micron Stock Alert: Elon Musk Just Made The Bull Case Even Stronger Dear Sandisk Stock Fans, Mark Your Calendar for October 29