

Data center developer Soluna Holdings (SLNH) has had a rough ride over the past year, with its shares tumbling amid mounting financial losses, aggressive equity financing that has significantly diluted shareholders, and Nasdaq compliance pressures. However, the company has now given investors a potential reason for optimism. On Wednesday, Soluna announced that it had entered into a definitive agreement with Applied Digital (APLD) to establish a jointly owned company focused on developing a planned 50 MW IT data center in Texas.
The facility will be powered by the Briscoe Wind Farm, aligning the project with Soluna’s renewable energy-powered data center strategy. Under the agreement, Soluna is expected to contribute a portion of its Dorothy 3 site, including land and power-related project assets, to the newly formed project company, while Applied Digital is expected to provide the capital needed to support development. Upon completion of the transactions, Applied Digital is expected to own a 51% stake in the project company, with Soluna retaining the remaining 49% interest.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
Dorothy 3 is a planned AI data center co-located with Briscoe Wind, a 150 MW wind farm in Briscoe County, Texas, near Soluna’s existing Dorothy 1 and Dorothy 2 projects. The partnership could provide Soluna with a development partner and additional financial support as it advances its data center ambitions. But with its shares under heavy selling pressure, does this latest agreement mark a meaningful turning point for Soluna, or should investors remain cautious about SLNH stock?
About Soluna Stock
Headquartered in Albany, New York, Soluna Holdings is on a mission to turn renewable energy into a global computing powerhouse. The company designs, develops, and operates digital infrastructure that transforms surplus renewable energy into valuable computing resources. Its innovative data centers are strategically co-located with wind, solar, and hydroelectric power plants to support high-performance computing (HPC) applications, including Bitcoin mining, generative AI, and other compute-intensive workloads.
At the heart of its operations is MaestroOS, Soluna’s proprietary software platform, which helps create a greener, more efficient power grid while delivering cost-effective, sustainable computing solutions and superior returns. However, Soluna has had a brutal run on Wall Street, with mounting losses, heavy cash burn, and aggressive shareholder dilution overshadowing its revenue growth.
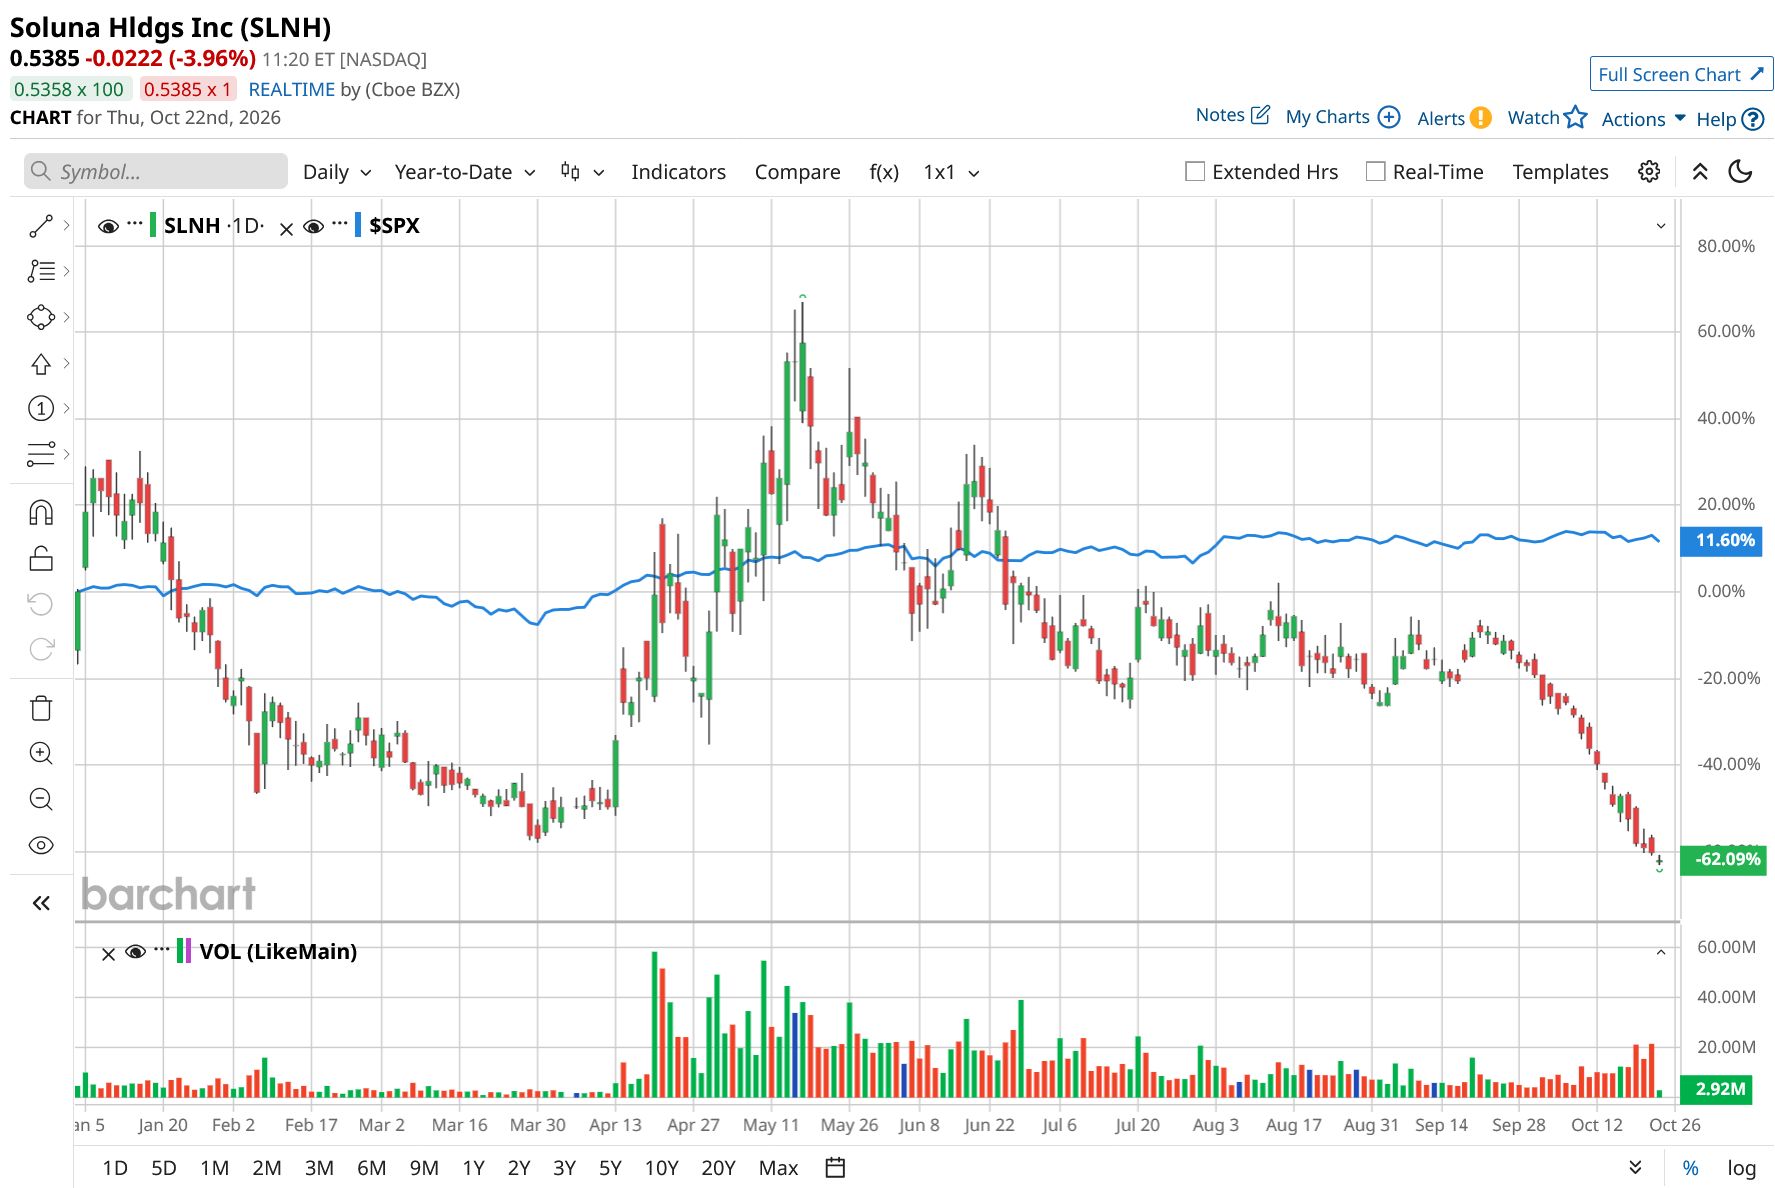
With a market capitalization of approximately $137.14 million, SLNH stock has plunged 84% over the past year and tumbled 54% in 2026, while the broader S&P 500 Index ($SPX) has advanced 14.3% over the past year and 11.9% year-to-date (YTD). Now, just months after regaining compliance with Nasdaq’s minimum bid price requirement in May, Soluna could face renewed listing concerns as its shares have once again fallen below the $1 threshold, raising fresh questions about its ability to regain market confidence.
 www.barchart.com
Inside Q2's Earnings Report
Soluna Holdings unveiled its fiscal 2026 second-quarter earnings on Aug. 13, delivering impressive revenue growth and advancing its strategic shift from Bitcoin mining toward AI infrastructure development. However, the upbeat top-line performance failed to reassure investors, with shares falling nearly 3.7% on the day as concerns over the company’s path to profitability persisted.
Despite building momentum, Soluna continues to grapple with rising operational expenses, widening losses, and the challenge of converting its 6.3-gigawatt renewable power pipeline into revenue-generating AI data center capacity. Revenue climbed for the fifth consecutive quarter, reaching $15.1 million, up 60% sequentially from Q1 and an impressive 145% year-over-year (YoY).
Growth was driven by contributions from Dorothy 2, the ramp-up of Kati 1A, and Briscoe’s first full quarter under Soluna’s ownership, partially offset by hash price compression. The company also reported that adjusted revenue, excluding a presentation change related to electricity pass-through costs, increased 73% YoY and 13% from the previous quarter.
Soluna also made progress in narrowing its adjusted EBITDA loss, which came in at $1.6 million, a 25% improvement from the $2.1 million loss reported in Q1. The improvement reflected lower legal and consulting expenses following the completion of the Briscoe acquisition, reduced compensation costs, and continued gross-profit contributions from Dorothy 2.
Nevertheless, profitability remained a significant weak spot. Gross profit fell to $766,000 in Q2, compared with $1.9 million in Q1 and $1.2 million in the second quarter of fiscal 2025. The decline was primarily attributable to $1.5 million in Briscoe maintenance costs, ramp-up expenses at Kati 1, and depreciation costs that began hitting the books ahead of the facilities’ full revenue contribution.
The bottom line painted a more challenging picture, with Soluna reporting a net loss of $22.6 million, compared with $17.9 million in Q1 and $7.8 million a year earlier. The wider loss was driven primarily by a $4.2 million loss on debt extinguishment, alongside the additional overhead and depreciation burden associated with Briscoe.
On the liquidity front, Soluna ended the quarter with $113.4 million in unrestricted cash and $33.1 million in total debt. Following the quarter’s close, the company also raised approximately $23.6 million through its at-the-market (ATM) equity offering program, providing additional capital while raising continued questions about potential shareholder dilution.
How Do Analysts View SLNH Stock?
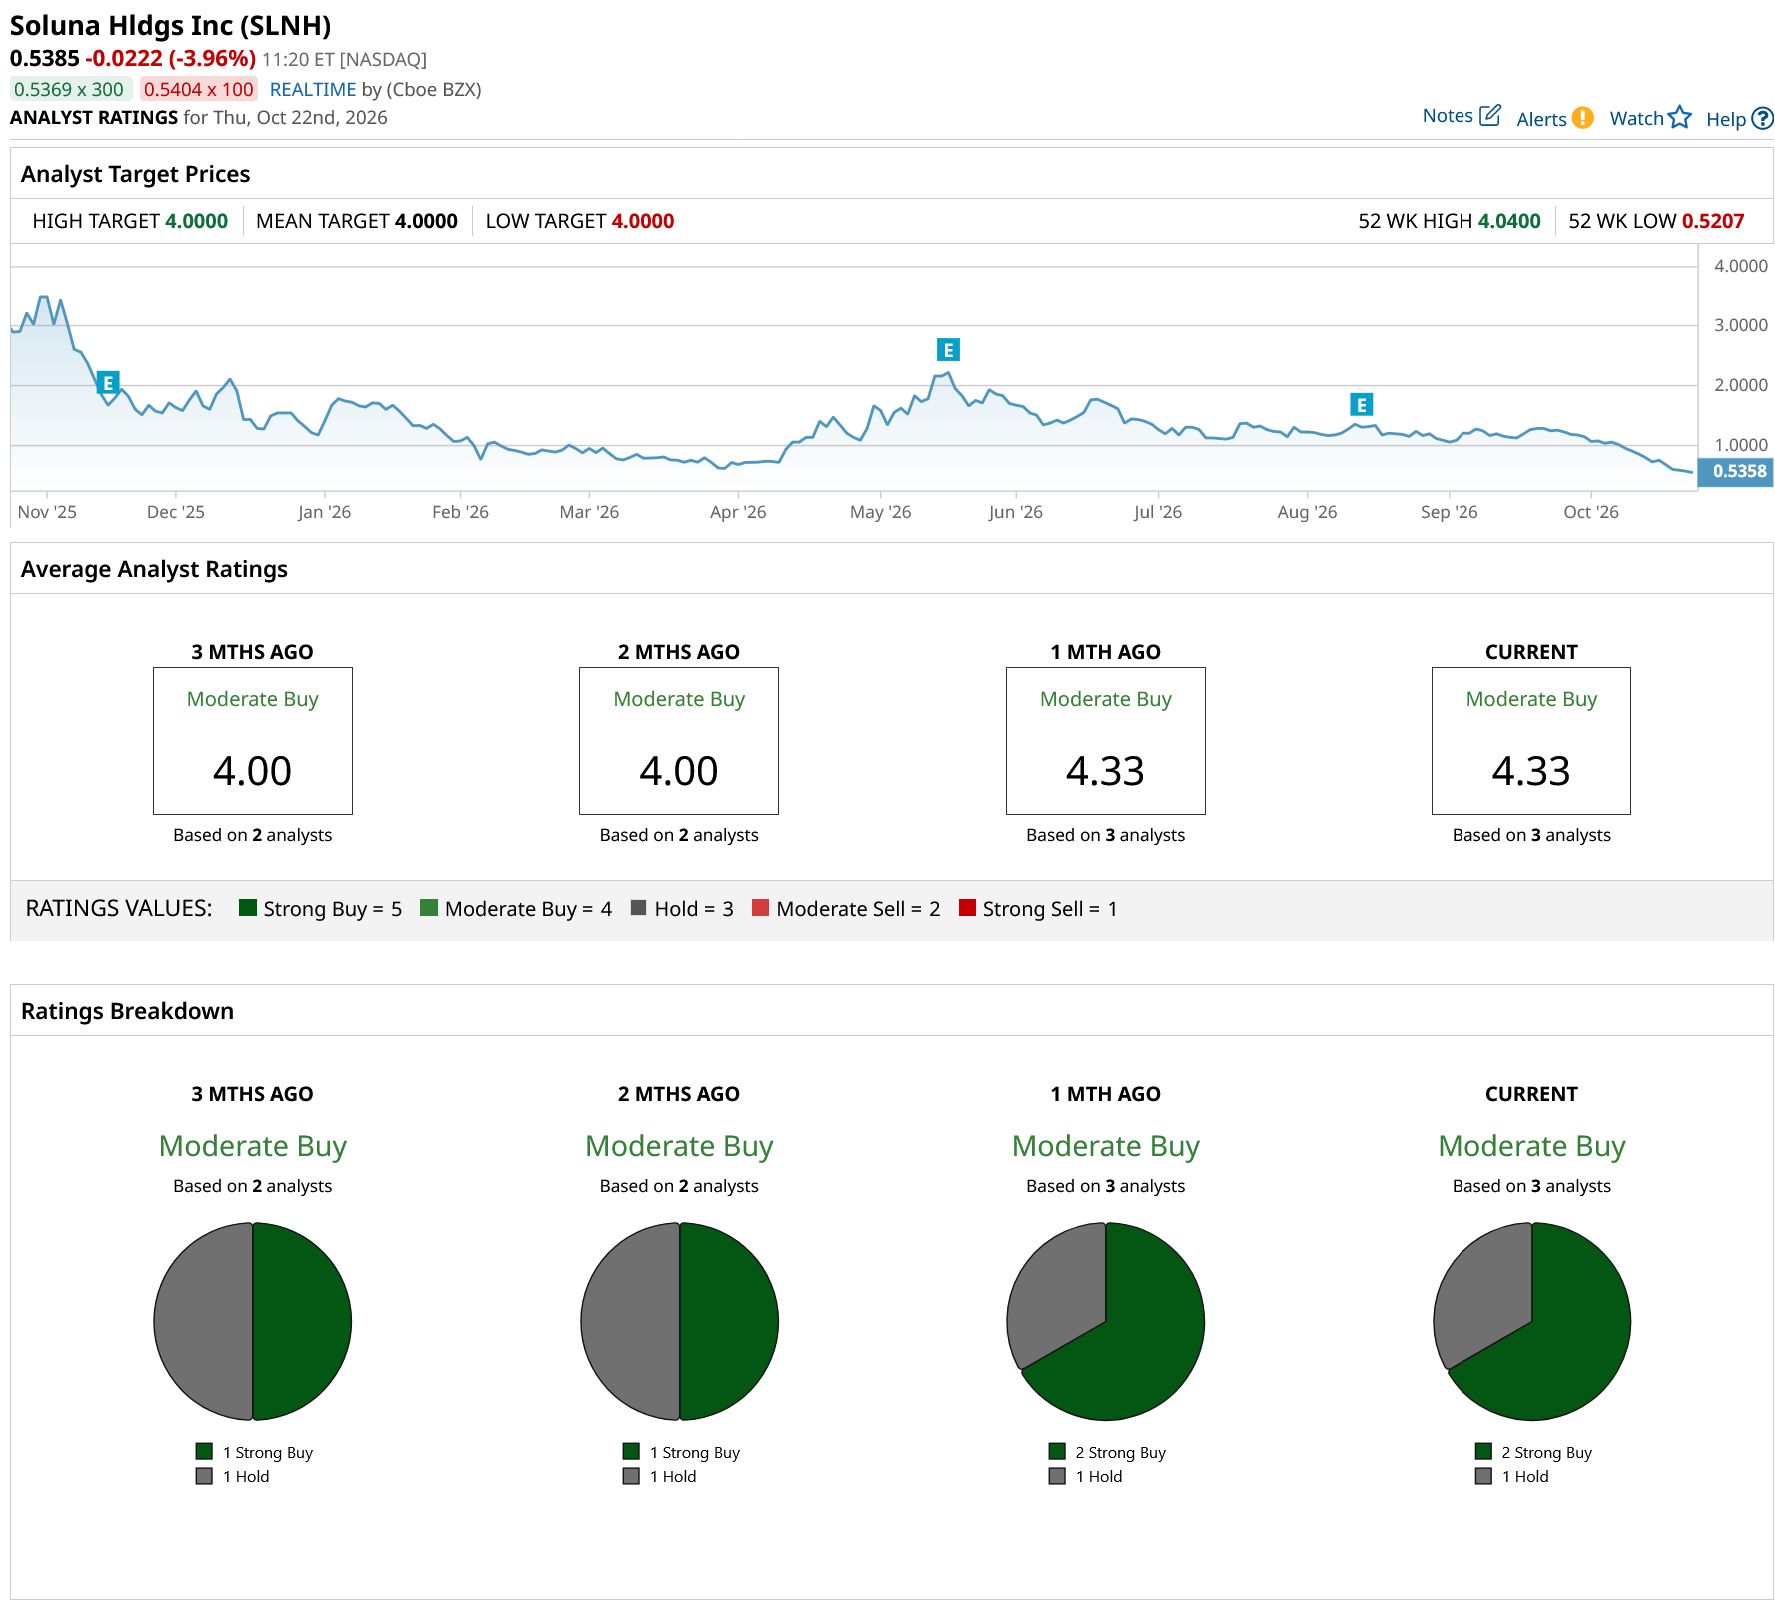
Despite the significant risks surrounding SLNH, Wall Street analysts see considerable upside potential for Soluna. While coverage remains limited to just three analysts, the consensus rating stands at “Moderate Buy,” with two analysts assigning a “Strong Buy” and one maintaining a “Hold.”
Meanwhile, the average price target of $4 points to a potential upside of nearly 641% from current levels, suggesting that analysts anticipate a substantial turnaround despite the company’s ongoing challenges.
 www.barchart.com
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play SLNH Stock as Soluna Scores a Major Data Center Win Which Sector Had the Most Energy Overnight? Down 12% in 1 Month, Bloom Energy Faces a Big Test on October 22. Here’s My Prediction. Electric Utility NiSource’s Data-Center Power Business Can Continue to Grow — And NI Stock Is Cheap