

Amazon (AMZN) will release its third-quarter earnings on Oct. 29. The event matters to Amazon stock fans. Despite growing demand for Amazon Web Services (AWS) and artificial intelligence (AI) infrastructure, AMZN's price doesn’t fully reflect the company’s earnings potential. Strong Q3 results could help close this gap and create room for further gains.
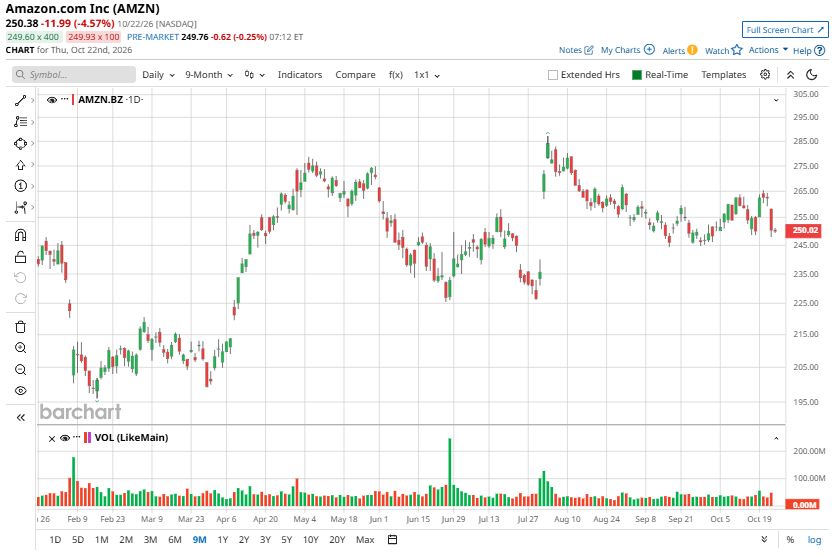
Amazon shares have gained 8% year-to-date (YTD), underperforming the broader market. This underperformance contrasts with the company’s improving business prospects, particularly in its cloud computing division, AWS. Rising cloud demand, growing AI-related workloads, and better infrastructure utilization could accelerate AWS revenue growth. Since AWS plays a major role in Amazon’s profitability, sustained growth in the segment could also boost overall earnings expectations.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Amazon’s high-margin advertising business is another growth driver. Its steady expansion could further support the company’s profitability. Let’s take a closer look.
 www.barchart.com
Amazon Q3 Outlook
Amazon’s Q3 will benefit from multiple catalysts, led by accelerating AWS revenue, rising demand for AI infrastructure, and strong advertising monetization. Continued improvements in e-commerce fulfillment could provide additional support, although substantial AI investments may limit near-term earnings growth.
Amazon has guided Q3 net sales for between $197 billion and $202 billion. At the midpoint, this implies about 11% year-over-year (YoY) revenue growth.
AWS is likely to remain the primary growth engine, supported by enterprise cloud spending and demand for AI computing capacity. The cloud division recorded 36.7% YoY revenue growth in Q2, marking its fifth consecutive quarter of accelerating growth. AWS also generated $4.6 billion in sequential revenue growth, bringing its annualized revenue run rate to approximately $169 billion.
Meanwhile, AWS’ $496 billion backlog highlights substantial contracted demand and provides visibility into future revenue. These indicators suggest that AWS is benefiting from sustained enterprise cloud spending and rising demand for AI infrastructure. The segment will likely maintain its growth momentum, with further acceleration in Q3.
Management indicated that both its custom AI chips and broader AI business have surpassed $25 billion in annualized revenue, with each growing at triple-digit rates. Moreover, the growing use of general-purpose CPUs for post-training AI inference and agentic workloads creates an additional opportunity for Graviton processors. Graviton adoption is likely to remain strong, with solid demand for the latest processor.
Advertising is another important source of growth and profitability for AMZN. Its advertising revenue rose 26% YoY to $19.8 billion in Q2. Momentum will continue in Q3, driven by sustained demand for sponsored Products. Separately, advertising across Prime Video and live sports broadens Amazon's reach beyond retail search and expands the potential to monetize its streaming audience.
In e-commerce, faster delivery and ongoing fulfillment improvements should support customer engagement, purchase frequency, and sales growth. More efficient logistics can also help Amazon balance its focus on convenience with the need to control operating expenses.
From an earnings perspective, AWS and advertising could provide meaningful support because of their attractive profitability profiles. At the same time, substantial AI-related capital spending and infrastructure costs may constrain near-term margin expansion. Improvements across retail and fulfillment could help mitigate some of these pressures.
Analysts expect Amazon to report Q3 earnings of $2.01 per share, up about 3% YoY. Although this suggests moderate near-term EPS growth, analysts expect earnings to accelerate in 2027.
AMZN Stock Is a “Strong Buy” Ahead of Q3 Earnings Release
Amazon’s Q3 earnings will likely strengthen its investment case by showing that its AI investments are translating into solid growth. Accelerating AWS growth, rising AI demand, and expanding advertising revenue support AMZN’s long-term earnings potential.
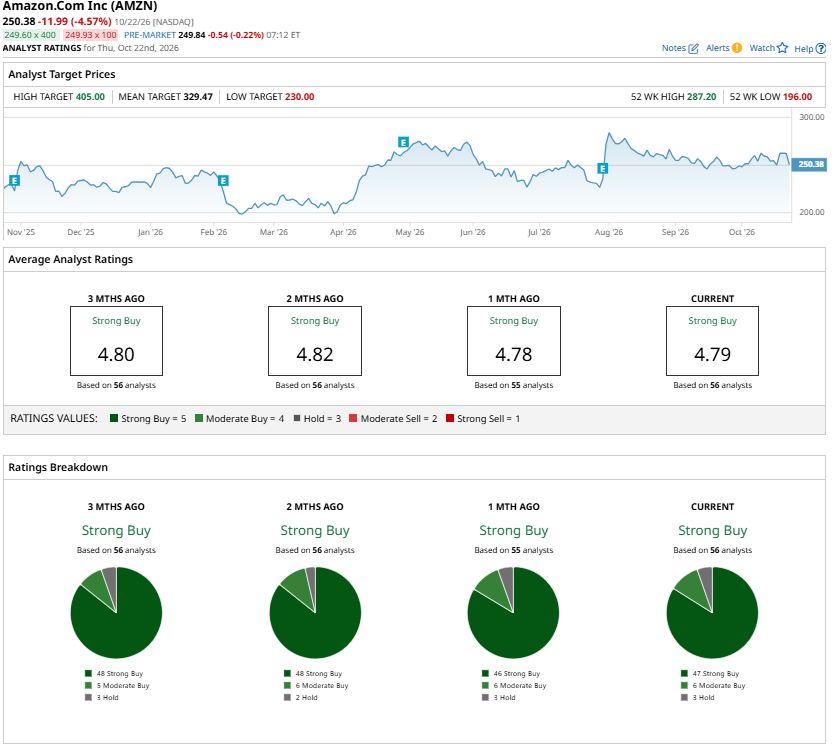
Wall Street remains bullish on AMZN stock, with analysts maintaining a “Strong Buy” consensus rating ahead of the Q3 earnings release.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Meta Stock Is Under Pressure as AI Costs and Legal Bills Mount. Here Are 4 Things Investors Need to Watch. Dear Amazon Stock Fans, Mark Your Calendar for October 29 This Stock Is Hot at New 52-Week Highs. But It Now for Profit Growth Ahead. The Biggest Merger Ever: Tesla and SpaceX Could Combine and Give Elon Musk 56% Control