

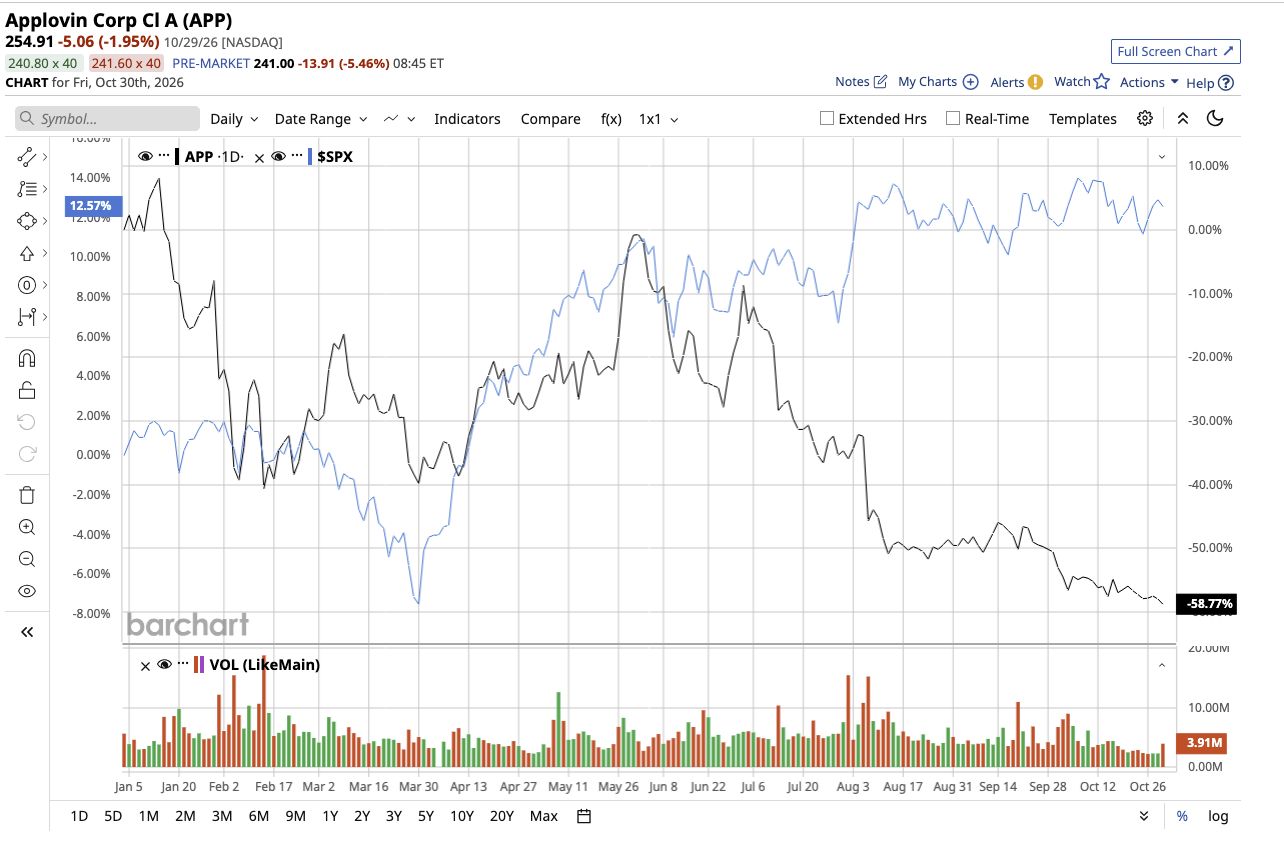
AppLovin (APP) has gone from being one of Wall Street's hottest growth stocks to one investors are suddenly questioning. After soaring 97% in 2025, the stock's dramatic 58% drop this year is enough to rattle even the most bullish AppLovin investors.
But savvy investors know stock performance doesn’t always reflect what's happening with a business. Short-term volatility depends on many factors, including changing market mood, valuation concerns, analyst downgrades, competitive pressures, and broader market conditions. AppLovin is one such case. The company missed Q2 consensus estimates. Analysts have questioned whether AppLovin can consistently improve its AI advertising models and retain its market-share gains against competitors such as Meta Platforms (META), Google (GOOG), and Unity (U), which has weighed on the stock.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
But while these concerns explain much of the selling pressure, they don’t mean the company's growth story is falling apart. Its AI-powered advertising technology is still evolving, and its ambitions in consumer advertising are picking up steam. In fact, AppLovin has several opportunities to win back Wall Street.
Its Q3 earnings report on Nov. 4 could offer important clues.
 www.barchart.com
1. AI Model Improvements Could Put AppLovin's Gaming Business Back on Track
AppLovin is an advertising technology company that helps businesses find customers and monetize apps using AI-powered advertising software. Its three main business segments are AI-powered advertising, app monetization, and e-commerce advertising.
AppLovin's gaming advertising business relies on AI-powered models that help advertisers reach potential customers and improve returns on ad spend. Better targeting encourages advertisers to increase budgets, making ongoing improvements to this technology essential for growth. In Q2, CEO Adam Foroughi openly admitted the company fell short of its usual pace of model improvement, causing a modest revenue dip versus guidance. However, meaningful improvement arrived shortly after the quarter ended, putting the business back on a stronger growth trajectory. He also emphasized that advertiser demand remained healthy, with MAX publisher earnings growing by double digits sequentially.
As the third quarter unfolds, investors will be keen to see if these recent improvements spark a spike in advertiser spending and elevate campaign results. If AppLovin continues to upgrade its models, it is poised to boost its gaming advertising business and revive the growth surge investors have been waiting for.
2. Consumer Advertising Could Be AppLovin's Next Big Growth Driver
AppLovin is setting its sights beyond mobile gaming, striving to tap into the vast advertising budgets of e-commerce and consumer businesses. This audacious move could not only diversify its revenue streams but also open up a much larger audience for its AI-powered advertising platform. During the Q2 earnings call, Foroughi revealed that consumer advertiser spending soared to 28% above Q4 2025 levels. This jump was largely driven by existing customers, who increased their investments after seeing strong results on the platform.
AppLovin has also opened its advertising platform to the public through AppLovin Ads Manager. However, management is initially focusing on mid-market businesses rather than aggressively onboarding smaller advertisers. By targeting clients with healthy advertising budgets, AppLovin aims to gather impactful campaign data and showcase just how effective its platform can be. However, consumer advertising is a relatively newer market for the company. Sustained progress would strengthen the case for consumer advertising as a meaningful second growth engine. I’d keep an eye on that.
3. AppLovin's Strong Cash Flow Leaves Plenty of Room for Further Investment
AppLovin’s financial performance is still a key reason why investors shouldn’t rush to sell. In Q2, revenue rose 53% year over year (YOY) to $1.92 billion. Adjusted EBITDA climbed 58% YOY to $1.61 billion. Free cash flow reached $863 million, showing its ability to generate substantial cash while funding expansion. Its balance sheet also provides financial flexibility. AppLovin wrapped up the quarter with $3.05 billion in cash and $3.7 billion in total debt. After buying and holding about $551 million in shares this quarter, it still has nearly $1.8 billion left in its share-repurchase authorization.
Yet, building smarter AI models demands more computing power, which could weigh on costs. Still, management believes these investments will unlock improved ad performance and boost monetization in the long run. For Q3, AppLovin guided revenue of $2.05 billion to $2.08 billion, representing 46% to 48% growth from the year-ago quarter. Adjusted EBITDA is expected to reach $1.71 billion to $1.74 billion with a margin of 83%. Investors should watch whether the company can meet these targets while continuing strong cash generation. Balancing technology spending with profitability will be important to supporting long-term growth.
The Bottom Line on APP Stock
Despite the stock performance, AppLovin has a strong position in gaming advertising, an expanding consumer advertising opportunity, and generates substantial cash to support further investment. AppLovin deserves a spot on any long-term investor's radar, especially if Q3 brings further proof of stronger advertising models and rising consumer spending. For those already holding shares, the company's ample cash flow and diverse growth opportunities offer compelling reasons to stay the course, even when the market gets choppy.
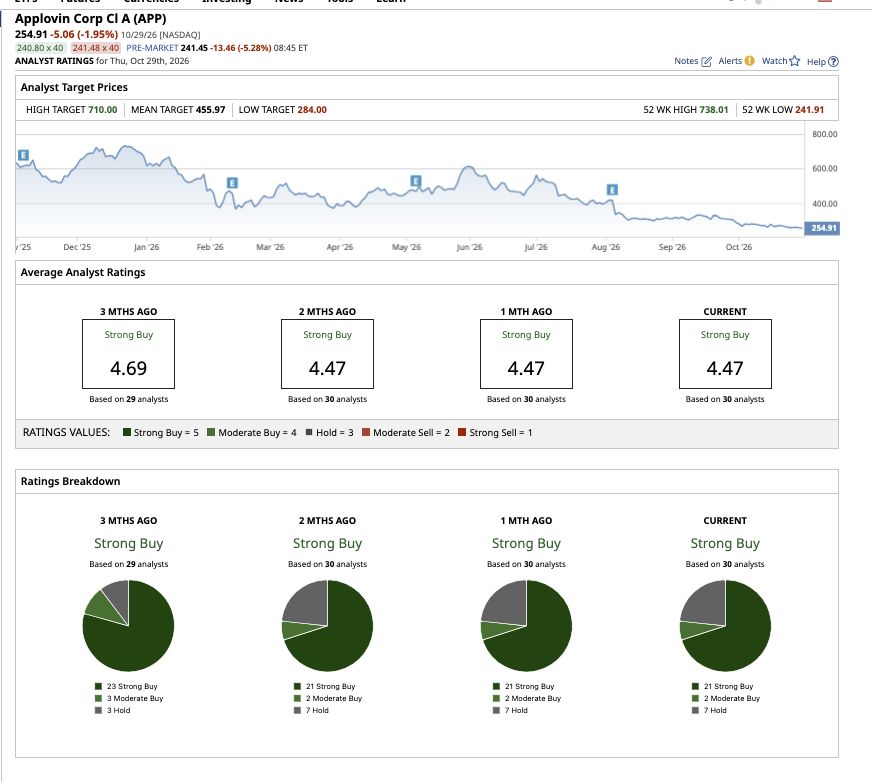
Wall Street still supports AppLovin stock, with an overall “Strong Buy” rating. Out of the 30 analysts who cover APP stock, 21 rate it as a “Strong Buy,” while two rate it as a “Moderate Buy,” and seven rate it a “Hold.” The average target price of $455.97 is 78% above current levels. However, the high price estimate of $710 implies that the stock could rally by up to 178.5% over the next 12 months.
 www.barchart.com
On the date of publication, Sushree Mohanty did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
AppLovin Stock Is Struggling: 3 Things to Watch in Q3 Earnings That Could Get APP Back on Track Coca-Cola Delivers Strong Growth - But is KO Stock Undervalued? Anthropic's Frenemies Meta and Google Are Showing Cracks In the AI Trade. What That Tells Us About the Anthropic IPO. SoFi Stock Is Ready for Its Next Big Move. Here's Why.