

Apple (AAPL) is steadily expanding its artificial intelligence (AI) capabilities through a series of strategic acquisitions, with its latest move involving Ascend.io, a Silicon Valley-based company specializing in AI and data automation.
While several of Apple's recent acquisitions have centered on consumer-facing technology, this agreement takes a different direction. Its primary focus is strengthening the company's internal data infrastructure and supporting the next phase of its AI development.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
According to the European Union's public database of significant acquisitions, Apple completed the transaction on Tuesday, June 30. Notably, the arrangement was not disclosed as a conventional acquisition. Instead, it grants Apple the right to extend employment offers to certain Ascend.io employees, together with a non-exclusive license covering the company's intellectual property and patents.
Although the structure differs from a traditional takeover, the agreement could deliver meaningful long-term benefits. More advanced AI capabilities could help Apple defend its competitive position, accelerate product innovation, improve operational efficiency, and create additional revenue opportunities.
Should these investments translate into better products and stronger financial results, they would reinforce investor confidence, support earnings growth, and provide further momentum for Apple's share price.
About Apple Stock
Apple is among the world's most influential technology companies, with a reputation built on its premium product ecosystem, exceptional customer loyalty, and consistent innovation. Its flagship offerings include the iPhone, iPad, Mac computers, Apple Watch, AirPods, and Apple TV.
Beyond hardware, the Cupertino, California-based technology giant has established a substantial services business through platforms such as the App Store, Apple Music, iCloud, and Apple Pay.
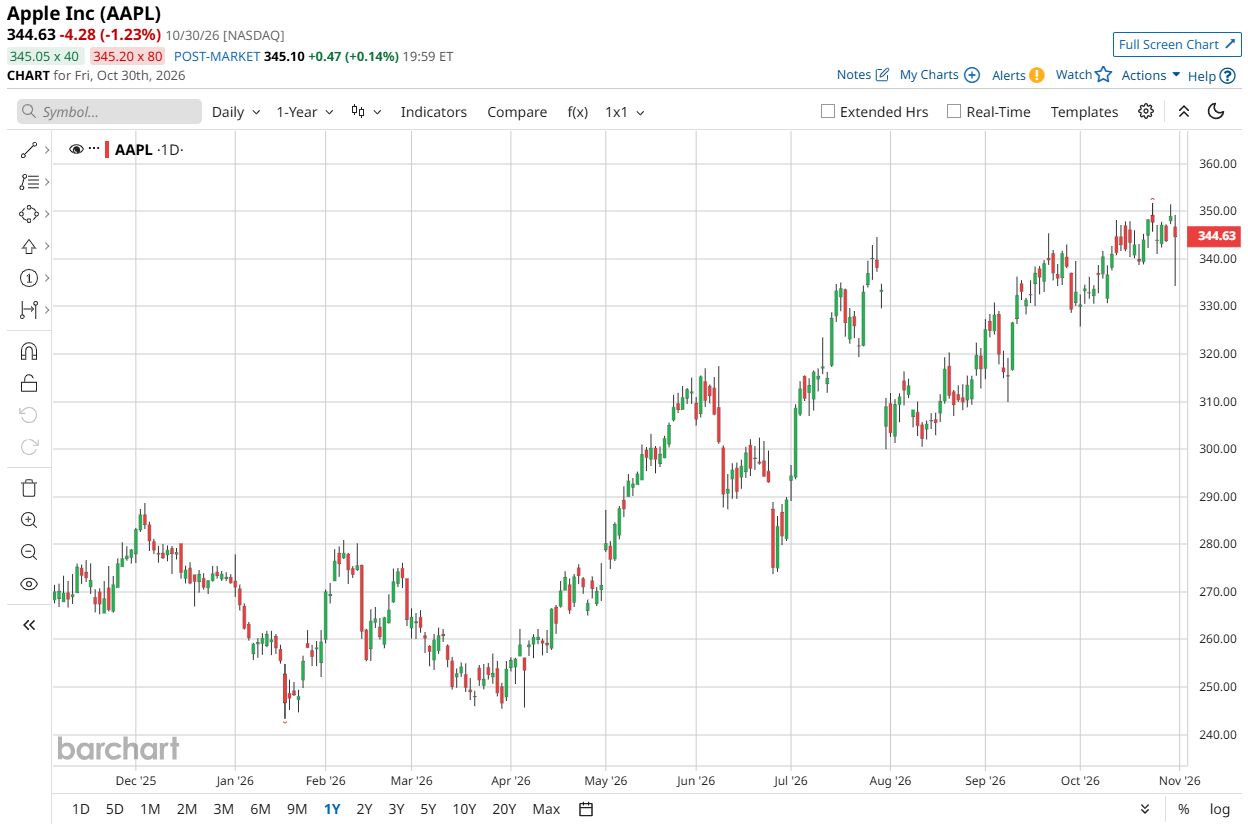
Apple's broad business portfolio has also translated into solid returns for shareholders. The company, which has a market cap of around $5 trillion, has seen shares climb 26% over the past 52 weeks and gain 25% year-to-date (YTD). The upward trend has extended into the shorter term, with shares climbing 2% over the last month.
 www.barchart.com
That performance, however, comes at a price. AAPL stock is currently trading at 38.98 times forward adjusted earnings and 10.53 times sales. Both valuation multiples sit above industry averages and their own five-year historical levels, suggesting a premium.
Apple has also increased its dividend payout for 13 consecutive years. Its current annual dividend stands at $1.08 per share, translating into a yield of 0.31%. The most recent distribution amounted to $0.27 per share and was paid on Thursday, Aug. 13, to shareholders of record as of Monday, Aug. 10.
Apple Surpasses Q3 Earnings
On July 30, Apple released its Q3 FY2026 financial results, exceeding Wall Street's expectations for both revenue and earnings. Revenue increased 16.4% year-over-year (YoY) to $109.4 billion, ahead of the $108.65 billion analyst estimate. Adjusted EPS came in at $1.91, surpassing analysts' forecast of $1.89.
Revenue from the iPhone segment rose 22% YoY to $54.3 billion, reflecting strong demand for the iPhone 17 lineup and sustained customer upgrade activity. Mac revenue delivered an equally encouraging performance, climbing 29% from the year-ago value to $10.4 billion on robust demand for the MacBook Neo and MacBook Pro.
Not every product category shared in the gains. iPad revenue slipped 6% from the prior year’s quarter to $6.2 billion, primarily because the segment faced a more challenging comparison with the previous year's product launch. Meanwhile, Wearables, Home and Accessories revenue increased 6% YOY to $7.9 billion.
Apple's Services division continued to provide a dependable source of growth. Revenue in the segment advanced 12.1% YoY to $30.7 billion, with every Services category recording revenue highs. Cloud services, payments, advertising, and subscriptions all contributed to the performance. Paid subscriptions also surpassed 1.5 billion, further strengthening Apple's recurring-revenue base.
On the profitability front, Profitability remained solid. Gross margin reached 50.1%, receiving an approximately 200-basis-point boost from tariff refunds. Operating income increased 26.6% despite operating expenses rising 22.9%, with research and development (R&D) spending leading the increase at 32.3%. The higher R&D investment also highlights Apple's accelerating efforts to develop its AI capabilities.
Looking ahead, Apple expects September-quarter revenue growth of 9% to 11%, about 500 basis points below June's pace, as supply constraints and FX headwinds weigh on performance. Gross margin is forecast at 47% to 48%, including roughly one percentage point from tariff refunds.
Rising memory costs remain a key pressure, which has prompted price increases across iPad and Mac products, although the impact on demand is still uncertain. Meanwhile, operating expenses are expected to reach $19.1 billion to $19.4 billion.
Apple is now scheduled to release its Q4 FY2026 earnings results on Monday, Nov. 2, after the market closes. Analysts anticipate Q4 EPS to grow 7% YoY to $1.98. For FY2026, the bottom line is projected to rise 17.3% YoY to $8.75, while for FY2027, analysts estimate EPS of $9.57, marking a 9.4% YoY increase.
What Do Analysts Expect for AAPL Stock?
Analyst sentiment toward Apple's growth remains broadly positive. Monness analyst Brian White reaffirmed his “Buy” rating while lifting his price target on AAPL stock to $355 from $335.
Bank of America Securities analyst Wamsi Mohan also reiterated his “Buy” recommendation, maintaining a $370 price target. Similarly, Evercore ISI analyst Amit Daryanani retained his “Outperform” rating on AAPL, with a price target of $380.
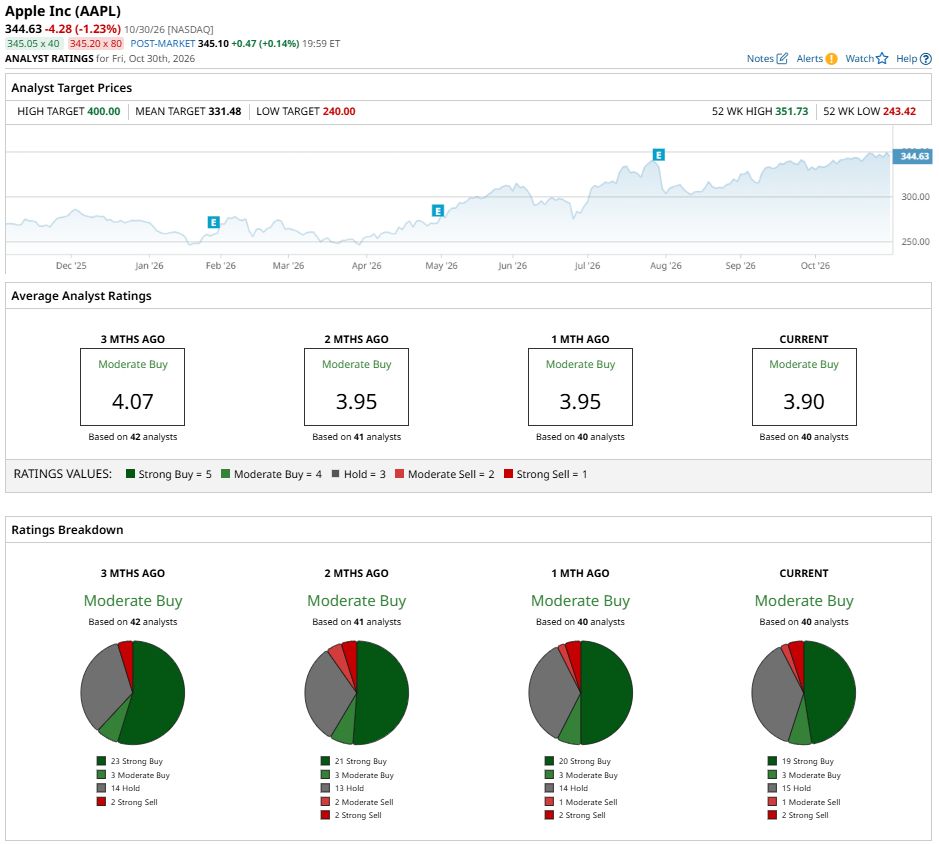
Overall, Wall Street rates AAPL a “Moderate Buy.” Of the 40 analysts covering the stock, 19 recommend a “Strong Buy,” three assign a “Moderate Buy,” 15 recommend “Hold,” one has a “Moderate Sell” rating, and two maintain a “Strong Sell” recommendation.
However, Apple’s shares are already trading above the average analyst price target of $331.48. The Street-high target stands at $400, suggesting further upside of 16% from current levels.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
3 Cash Cow Stocks I Like Better Than Anthropic Heading into a Historic IPO Bill Ackman Isn’t Sweating Meta Platforms’ AI Spending. In Fact, He Says META Stock Is ‘Incredibly Undervalued.’ Dan Ives Thinks Apple’s New MacBook Pro Is a Positive Move with Q4 Earnings Almost Here Anthropic Takes Aim at Wall Street’s 1% Fee Machine With ‘Claude For Financial Advisors.’ Here’s What I Think as a Former Advisor.