

Cloudflare (NET) will report its Q3 earnings Thursday, Nov. 5. Expectations ahead of the earnings release remain positive, supported by the company’s ability to sustain customer acquisition momentum while deepening its penetration of existing accounts. Continued growth in its paying customer base, coupled with higher spending from large customers, could serve as key drivers of revenue expansion.
While strong quarterly performance and an expected upbeat forward guidance support its investment case, Cloudflare’s premium valuation remains a key risk.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Cloudflare's Q3 Outlook
Cloudflare’s strong operating momentum provides a favorable foundation for continued growth in the third quarter and beyond. The company is positioned to benefit from sustained customer acquisition and expanding spending from its existing customer base. These factors are expected to support revenue growth.
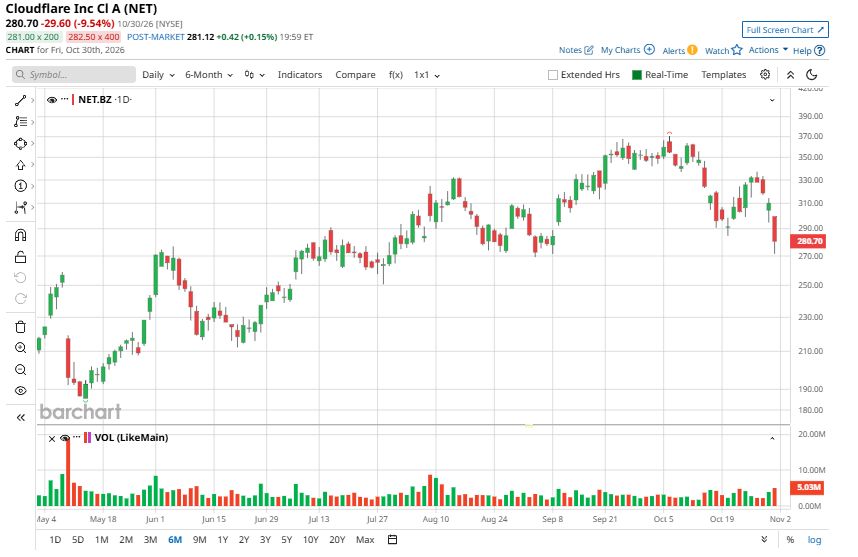 www.barchart.com
Customer acquisition trends remain encouraging. During Q2, Cloudflare recorded its strongest pace of new customer bookings in more than five years, while new pipeline generation continued to accelerate, reaching its fastest sequential growth rate over the same period. NET added more than 80,000 paying customers during the quarter, up 74% year-over-year (YoY). This acceleration in customer additions highlights the continued demand for Cloudflare’s platform and its ability to attract new users.
Equally important, Cloudflare is expanding its relationships with larger enterprise customers. At the end of Q2, the company had 4,698 customers generating more than $100,000 in annualized revenue, representing 27% YoY growth, compared with 25% in the previous quarter. Cloudflare added 282 large customers during Q2 and a record 986 over the past year. Notably, every enterprise spending cohort, ranging from $100,000 to $500,000, $1 million, and $5 million in annualized revenue, recorded its highest-ever YoY net customer additions. This broad-based expansion suggests that demand is strengthening across multiple enterprise spending tiers.
The growth in enterprise relationships is also reflected in Cloudflare’s remaining performance obligations (RPO). Total RPO reached $2.73 billion, up 7% sequentially and 38% YoY. Meanwhile, the current RPO, which represents the portion expected to be recognized over the next 12 months, accounted for 64% of total RPO and increased 35% from the prior-year period. The sustained expansion in these metrics indicates a healthy backlog.
Against this backdrop, Cloudflare appears well-positioned to deliver another quarter of solid growth. Management anticipates Q3 revenue growth of approximately 31% YoY. However, accelerating customer bookings, expanding enterprise relationships, and robust pipeline generation indicate underlying business momentum remains strong. Consequently, the company could outperform its Q3 revenue guidance.
Revenue growth should also contribute to continued improvement in profitability. Management expects Q3 adjusted earnings of $0.34 per share, compared with $0.27 in the corresponding quarter last year. This implies approximately 26% YoY growth in adjusted EPS.
Overall, strong customer acquisition, deeper enterprise penetration, and expanding contractual commitments support a constructive Q3 outlook.
Valuation Remains a Key Risk for NET Stock
Despite expectations of strong revenue growth in Q3, Cloudflare’s premium valuation remains a significant risk. Trading at approximately 50.6 times sales, NET stock appears to reflect substantial future growth expectations, leaving limited room for growth.
Consequently, even positive quarterly results may not necessarily translate into meaningful share price appreciation. This valuation risk appears to be reflected in analysts’ relatively measured outlook, with NEt stock's consensus sentiment remaining at “Moderate Buy” ahead of the company’s Q3 earnings announcement.
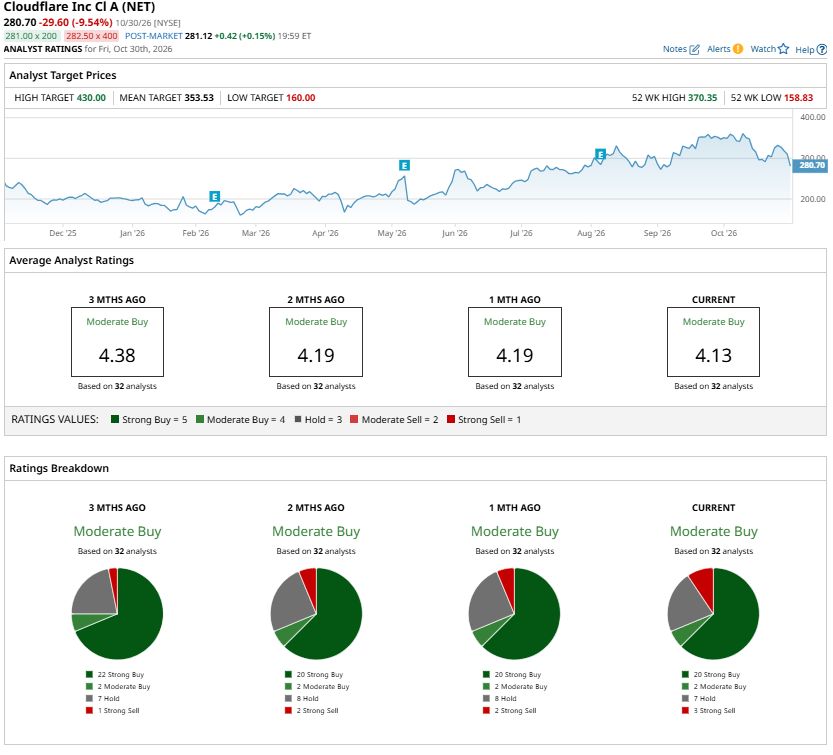 www.barchart.com
Cloudflare’s Growth Story Remains Strong, but Valuation Warrants Caution
Cloudflare’s strong customer acquisition, expanding enterprise relationships, and growing contractual backlog position the company for another solid quarter, with potential to exceed its Q3 revenue guidance.
Continued growth in large-customer spending should also support its longer-term revenue and earnings outlook. However, NET stock’s premium valuation remains a significant concern, as much of its future growth potential is already reflected in the share price.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Nvidia Stock Looks Surprisingly Cheap. Why NVDA Could Rise 61%. Indian Trading Apps Just Opened the Floodgates for SpaceX Stock PepsiCo Generated Strong FCF - Huge, Unusual Put Options Volume Trade Today is a Bullish Signal Dear Cloudflare Stock Fans, Mark Your Calendar for November 5