

Property and casualty insurers faced pressure heading into third-quarter earnings, with hurricane-related catastrophe losses and more competitive commercial insurance pricing. Before The Hartford Insurance Group’s (HIG) Oct. 26 report, analysts expected earnings of $3.09 per share, down 18% from $3.78 a year earlier. The company had beaten estimates in three of the previous four quarters.
The Hartford Insurance Group beat expectations again in Q3, reporting core earnings of $3.50 per share. The firm also gave shareholders a bigger dividend, raising its quarterly payment from $0.60 to $0.67, an increase of roughly 12%.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
That follows a 66% increase in its dividend over the past five years. Can The Hartford Insurance Group keep raising its payout as insurance pricing becomes more competitive? Let’s find out.
The Earnings Behind the Higher Payout
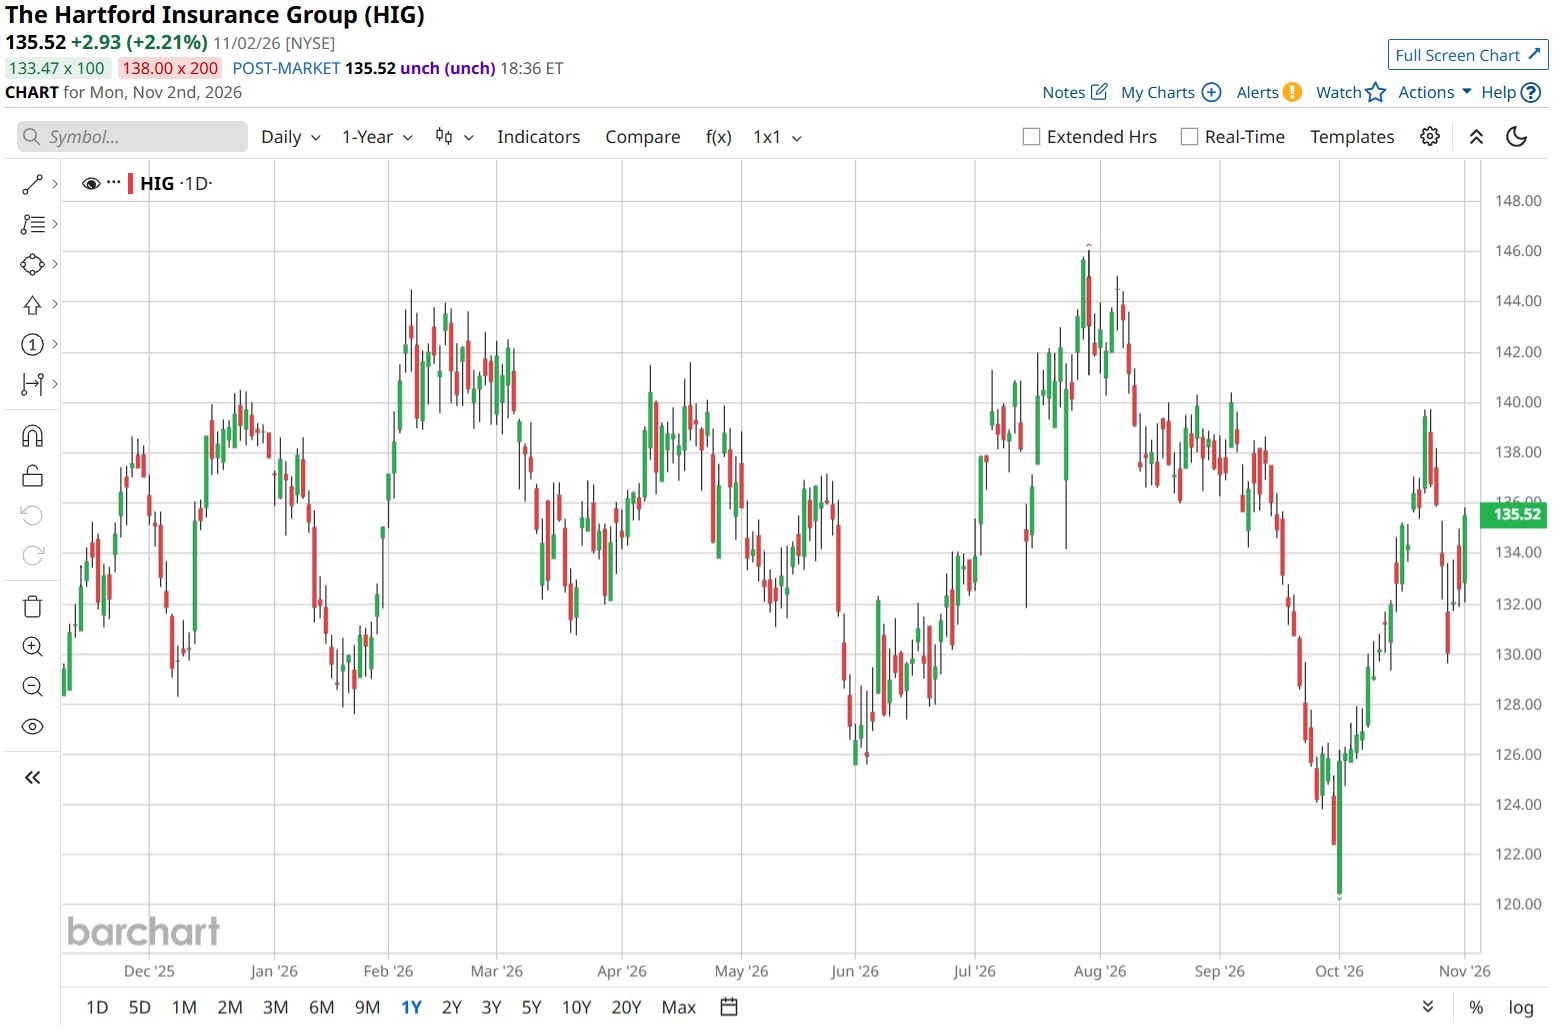
The Hartford Insurance Group makes money from business insurance, personal insurance, and employee benefits, and earns additional income by investing its insurance assets. Shares of HIG stock are up 8% over the past 52 weeks but up less than 1% year-to-date (YTD).
 www.barchart.com
HIG stock trades at 10.2 times expected earnings, below the sector’s 11.2 times, meaning investors pay less for each $1 of expected profit.
The company raised its quarterly dividend by 12%, from $0.60 to $0.67, taking the annual payout to $2.68. The next payment is due Jan. 5, 2027, to shareholders on record as of Dec. 1. The increase extends its dividend-growth streak to 14 years. Before the raise, the $2.40 annual payout yielded 1.77% and represented 15.82% of expected earnings. The new payout yields about 2.07% at the current share price.
Q3 results were mixed. Net income available to common shareholders rose 23% year-over-year (YOY) to $1.3 billion, or $4.82 per share, from $1.1 billion, or $3.77 per share. Income from continuing operations increased 24% to $1.26 billion, or $4.60 per share, from $1.02 billion, or $3.56. But core earnings fell 6% to $956 million, or $3.50 per share, from $1.02 billion, or $3.59. A one-time $497 million reinsurance gain helped lift reported profit without boosting core earnings.
Catastrophe losses rose to $198 million from $70 million, mainly because of tornadoes, wind, and hail. Higher investment income helped offset that pressure, rising 13% to $850 million. Over the trailing 12 months, net-income return on equity reached 25%, while core return on equity reached 17.9%. Book value per share also rose 7% to $68.31, or 16% to $82.47 excluding accumulated other comprehensive income, giving the company a stronger equity base behind its higher payout.
What Could Keep Hartford Insurance Group Growing?
The Hartford Insurance Group is working with the University of Connecticut on energy innovation, worker safety, and ways to keep businesses running during disruptions. Through its Laborer Safety Fund, the insurer will support the Korey Stringer Institute’s research into how short-term and prolonged extreme heat affects workers’ health and productivity. The research will also look at ways to reduce heat exposure and keep businesses operating. Separately, the company will fund an energy-innovation fellowship at UConn’s Institute of the Environment and Energy.
The Hartford is also partnering with UC Berkeley’s Bakar Labs for Energy and Materials to help energy and materials startups understand insurance and manage risk. It will offer advice, educational programs, and mentoring. Possible projects include case studies on how insurance needs change as startups grow and how risks shift when technologies move from the lab into commercial use.
The company's completed acquisition of Equitable’s Employee Benefits business adds about $500 million in premiums and 300 employees. The business serves small and midsize employers with life, disability, paid family and medical leave, supplemental health, dental, and vision coverage. It also brings digital tools and real-time connections between software systems. Management expects the deal to slightly reduce 2027 core earnings, including about $30 million in annual intangible amortization, before adding to earnings as the businesses are integrated. The long-term Employee Benefits margin target remains 6% to 7%.
How Analysts See Hartford Insurance Group’s Next Chapter
The Hartford Insurance Group’s next earnings report is scheduled for Feb. 4, 2027. Analysts expect December-quarter earnings of $3.27 per share, down 19% from $4.06 a year earlier. For fiscal 2026, analysts forecast earnings of $13.31 per share, down 1% from $13.42.
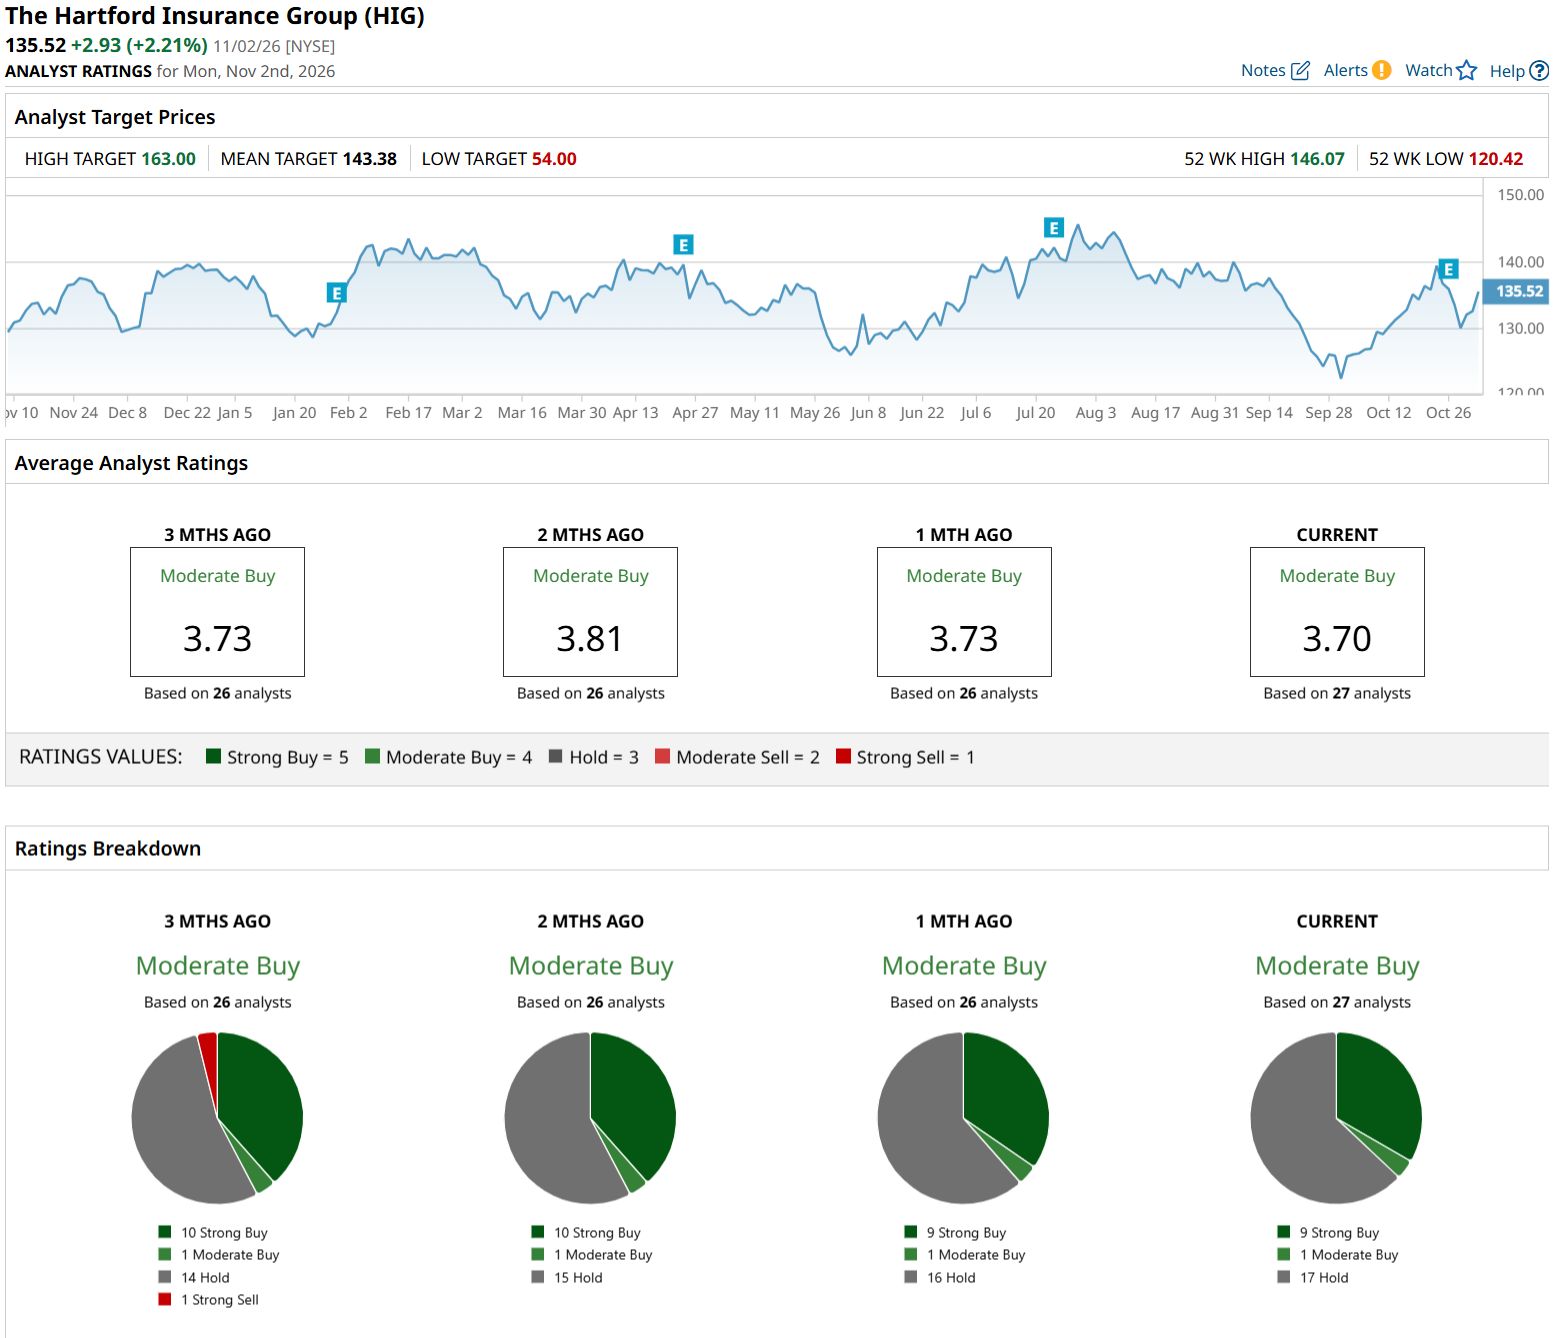
Some analysts have lowered their price targets on HIG stock. Mizuho recently lowered its price target to $144 per share with a “Neutral” rating. On Nov. 2, Cantor Fitzgerald kept its “Overweight” rating but cut its target from $145 to $136.
The consensus among 27 analysts with coverage is still a “Moderate Buy" rating. The average price target of $143.33 suggests potential upside of 4% from current levels.
 www.barchart.com
Conclusion
The Hartford Insurance Group looks capable of growing its dividend, even with more competitive insurance pricing. The payout remains modest relative to expected earnings, while investment income and the expanded Employee Benefits business provide support. Still, falling core earnings and higher catastrophe losses argue against expecting another double-digit increase automatically. I lean toward a gradual move higher in the shares rather than a sharp rally, consistent with Wall Street’s consensus “Moderate Buy” rating. For investors, the appeal is a growing payout at a reasonable valuation, not a high starting yield or the promise of quick gains.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Insurance Stock Just Raised Its Dividend by Over 11% This Could be a Major Problem for Alphabet Investors Uber Technologies Delivers Strong FCF - What's the Best UBER Play? Apple Flagged Supply Constraints and Rising Memory Costs Ahead of Its December Quarter. Here’s What to Know.