

VICI Properties Inc. (VICI) is an experiential real estate investment trust (REIT) headquartered in New York City, specializing in the ownership and acquisition of gaming, hospitality, entertainment, wellness and leisure properties. The company is valued at $27.8 billion by market cap and owns a portfolio of 103 experiential assets across the United States and Canada, including 63 gaming properties and 40 other experiential properties.
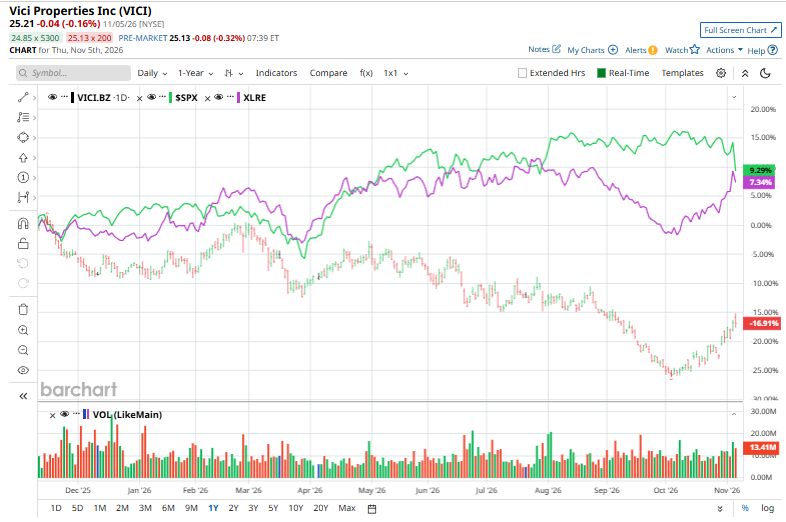
Shares of this diversified commercial REIT have underperformed the broader market over the past year. VICI has declined 16.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 8.2%. In 2026, VICI stock is down 10.4%, compared to the SPX’s 7.4% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Narrowing the focus, VICI has also trailed the State Street Real Estate Select Sector SPDR ETF (XLRE). The exchange-traded fund has gained about 8.2% over the past year and a 9.8% rise this year.
 www.barchart.com
VICI Properties reported a solid Q3 2026 performance on Oct. 28, with total revenue increasing 5.8% year over year to $1.10 billion and AFFO rising 7.5% to $685.2 million, or $0.62 per share, up 4.3%. However, net income declined 55.1% to $342.5 million, while EPS fell 56.4% to $0.31, primarily due to the impact of changes in its CECL credit-loss allowance.
During the quarter, the company issued $1.75 billion in investment-grade senior notes to refinance upcoming debt maturities and announced a new triple-net master lease agreement with Highfield Investment Group, which will expand its tenant base upon closing. VICI also increased its quarterly dividend by 2.2% to $0.46 per share and raised its full-year 2026 AFFO guidance to $2.695 billion–$2.705 billion, or $2.47–$2.48 per diluted share. Additionally, its board authorized a $2 billion share repurchase program following the quarter-end, underscoring its commitment to shareholder returns.
For the current fiscal year, ending in December, analysts expect VICI’s FFO to grow 3.8% to $2.47 per share on a diluted basis. The company’s earnings surprise history is impressive. It matched the consensus estimates in each of the last four quarters.
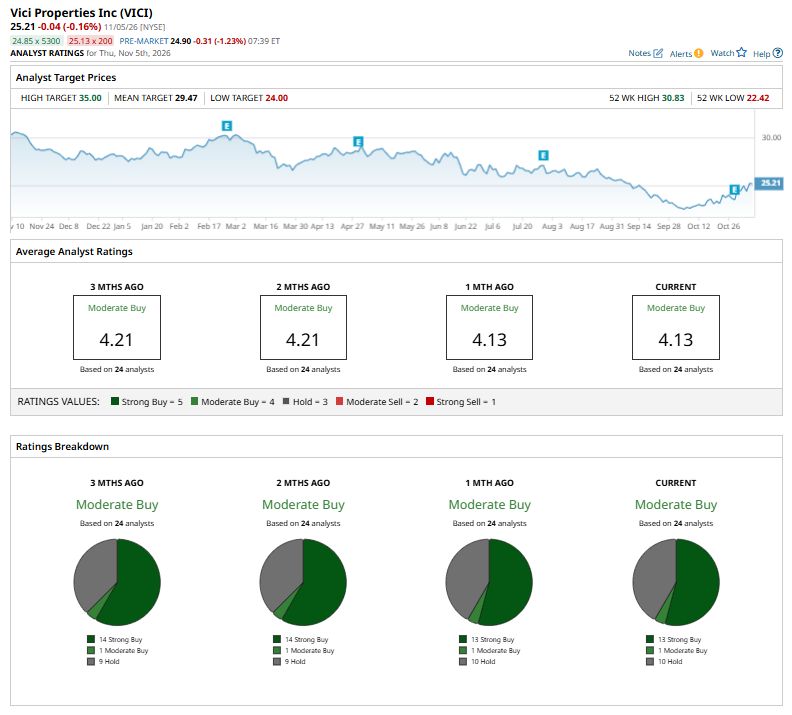
Among the 24 analysts covering VICI stock, the consensus is a “Moderate Buy.” That’s based on 13 “Strong Buy” ratings, one “Moderate Buy,” and 10 “Holds.”
 www.barchart.com
The configuration is bearish than two months ago, when the stock had 14 “Strong Buy” suggestions.
On Nov. 5, Citigroup analyst Nick Joseph maintained a “Buy” rating on VICI Properties while lowering the price target to $30 from $36, a 16.7% reduction.
The mean price target of $29.47 represents a 16.9% premium to VICI’s current price levels. The Street-high price target of $35 suggests an ambitious upside potential of 38.8%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
2 Red Flags Supermicro Investors Shouldn’t Ignore After Earnings Nasdaq Futures Climb as Chip Stocks Bounce After Rout; Key U.S. Jobs Report in Focus This Insurance Stock Just Raised Its Dividend by Over 11% This Could be a Major Problem for Alphabet Investors