

Palantir (PLTR) just gave Wall Street a big surprise. In its most recent quarterly earnings report, U.S. commercial revenue topped U.S. government revenue for the first time in the company's history. Palantir's reliance on government revenue has been something the bulls have whined about for years. Now, though, Palantir is no longer only a defense contractor with a software side business. Its commercial engine has become a much larger feature.
During the third-quarter earnings call, CEO Alex Karp was fairly blunt. He noted how the commercial business had “eclipsed” Palantir's government business, moving from being a secondary growth area to a primary engine for the company. The impact of that is enormous, especially as the mix change should benefit Palantir's fortunes by de-risking and diversifying its business.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
This is a structural change for the company. However, PLTR stock is still overvalued, and Wall Street isn't completely united in the belief that the U.S. commercial revenue news makes Palantir stock worth its current price. Let's take a closer look.
A Bumpy Ride for Palantir Stock
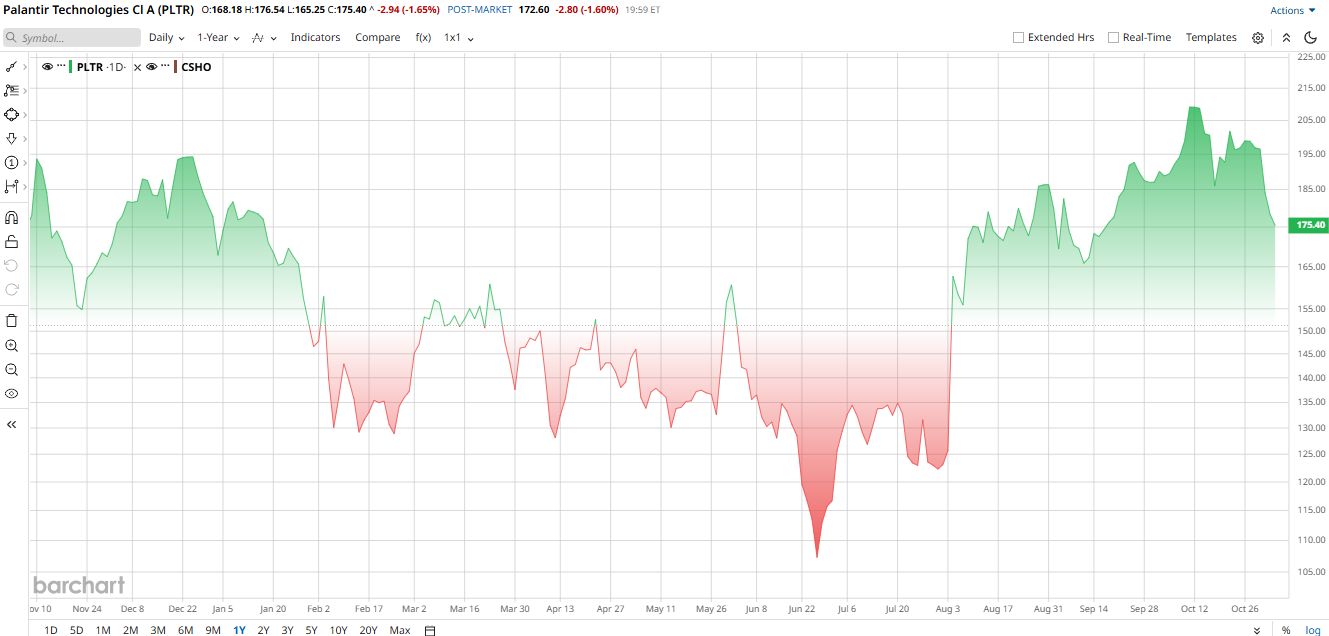
After soaring in 2025, Palantir stock has finally received a reality check this year, down 10% year-to-date (YTD). Shares hit a 52-week high of $212.94 in October 2026 but have cooled down since then.
The catalysts have been real. Sovereign AI deals with names like L3Harris (LHX) and Nvidia (NVDA) have lit a fire under Palantir stock. Goldman Sachs upgraded the stock to a “Buy” rating in early October with a $230 price target.
Still, the negatives are just as loud. Valuation fears keep capping every rally. Palantir stock fell after the Q3 earnings report despite a massive beat. Investors love the growth, but they hate the price.
Despite strong recent quarters, Palantir’s valuation is considered extremely high, with a price-to-earnings (P/E) ratio exceeding 118 times and an enterprise value-to-EBITDA multiple far above peers. That makes the stock vulnerable if growth slows or a market downturn occurs.
 www.barchart.com
The Commercial Business Finally Wins
The most recent headline for Palantir has to do with its commercial business. U.S. commercial revenue hit $984 million in Q3, up 148% year-over-year (YOY). Meanwhile, U.S. government revenue came in at $953 million, showing YOY growth of 96%. So, the commercial side won, both in terms of growth and revenue.
"The Sovereign AI movement is imposing the most dramatic dichotomy between haves and have nots that I have witnessed in 30 years of business," Karp noted alongside earnings. That impact is huge. “The Sovereign AI moment is purpose-built for Palantir,” he said.
Meanwhile, commercial deals tend to be larger and stickier over time. With this mix change, Palantir will be able to rely less heavily on unpredictable defense budget cycles. That's transformational for the whole business.
Palantir Reports Q3 Numbers
The third quarter was a blowout overall. Total revenue came in at $2.31 billion, up 96% YOY. The quarter also marked the first time Palantir has crossed $2 billion in revenue in a single quarter.
Net income was $1.13 billion, making for a 49% margin, while adjusted EPS came in at $0.44. The company's adjusted operating margin was 62%, while Palantir scored a Rule of 40 score of 158% for the quarter. Adjusted free cash flow was $1.22 billion, representing a 53% margin. As of the end of Q3, Palantir had $10.4 billion in cash, cash equivalents, and U.S. Treasury securities.
Management provided strong guidance as well. For Q4, the firm expects revenue between $2.649 billion and $2.653 billion. For the full year, Palantir also raised its revenue guidance to $8.53 billion to $8.534 billion. U.S. commercial revenue is now expected to top $3.559 billion in fiscal 2026, while adjusted free cash flow guidance sits at $4.8 billion to $5.0 billion. Meanwhile, analysts expect EPS of $1.36 in fiscal 2026 on revenue of $8.55 billion.
What Else Is Palantir Doing?
The commercial milestone seen in Q3 was not just a lucky occurrence. Whether it's sovereign AI deals or partnerships, Palantir has been busy for a while.
In October, Palantir said that it planned to deploy sovereign AI capabilities with L3Harris, Ondas (ONDS) and Regna AI, Nvidia, and other customers. These deployments are not little pilots. This is business spin on the flywheel. With sovereign AI, enterprises can use and maintain sophisticated models on their own data without giving that data to the big AI labs. Data sovereignty is a real pain point, and one of the few companies selling the fix is Palantir.
What Are Analysts Saying About Palantir Stock?
Wall Street is not unanimous on PLTR stock, and that is putting it mildly.
Analysts at JPMorgan began coverage in late October with an “Overweight” rating and a price target of $262. Morgan Stanley also recently raised its price forecast to $233 but maintained an “Equal Weight” rating, while Piper Sandler upgraded its target to $235 with an “Overweight” rating. Finally, Jefferies has an “Underperform” rating with an $80 price target.
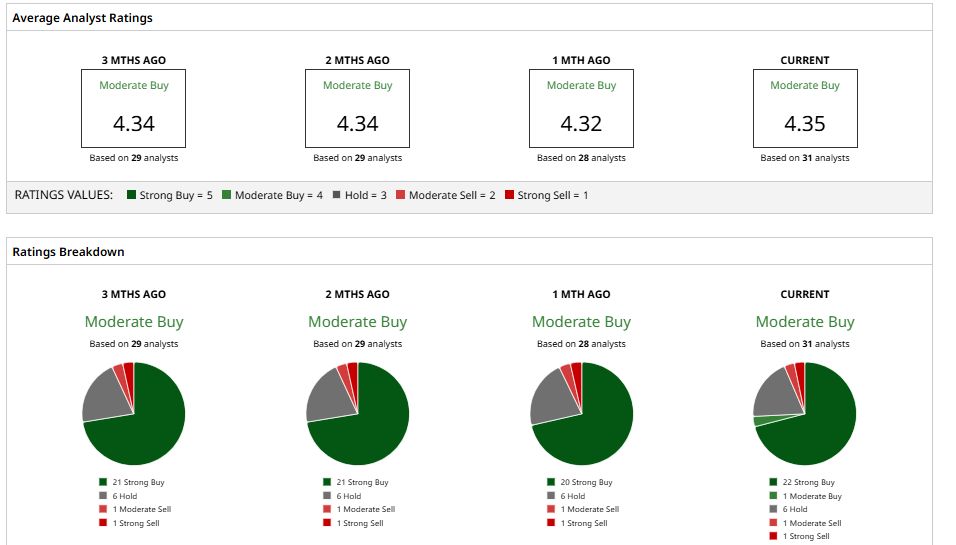
Overall, Palantir has a consensus “Moderate Buy" rating on Wall Street based on 31 analysts with coverage. The average price target of $223.86 points to potential upside of about 40% from current levels.
In my view, PLTR stock is somewhat akin to a lottery ticket right now. If you are a believer in sovereign AI, Palantir is the pickaxe seller, and its recent commercial milestone may be more important than the valuation multiple. Still, the valuation battle shows no signs of letting up.
 www.barchart.com
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Palantir’s Commercial AI Business Just Changed the Story, But It’s Stock Could Be Too Expensive Apple Delivers Strong Free Cash Flow, But Analysts See AAPL At a Peak - What's the Best Play? Andy Jassy Claims Amazon ‘May Have Two’ Trillion-Dollar Businesses. Here’s the Math Behind It. Option Volatility and Earnings Report For Nov 9-13