

Target (TGT), the leading general merchandise retailer competing with Walmart (WMT) and Costco (COST), is working to regain its growth momentum after a prolonged period of declining sales and softer discretionary demand.
The company is now undertaking a significant business overhaul, with a sharper focus on merchandise, convenience, and operational efficiency. Since Michael Fiddelke became CEO in February, the retailer has been refining its product assortment, improving the shopping experience, and strengthening its competitive position.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Faster order fulfillment is another vital part of this transformation. Target is investing heavily in same-day and next-day services to keep pace with changing online shopping habits, and its Q2 FY2026 results suggest that these efforts are gaining traction.
The next important update is scheduled for Wednesday, Nov. 18, when Target releases its Q3 FY2026 financial results before the market opens. The numbers and management commentary would offer a better understanding of how the turnaround is progressing and what lies ahead for the retail giant.
About Target Stock
Target offers an extensive merchandise selection spanning clothing, beauty, groceries, electronics, home furnishings, household essentials, toys, and pet supplies. With a market cap of nearly $73.4 billion, the Minneapolis, Minnesota-based retailer serves customers through its physical stores and digital platforms, including Target.com.
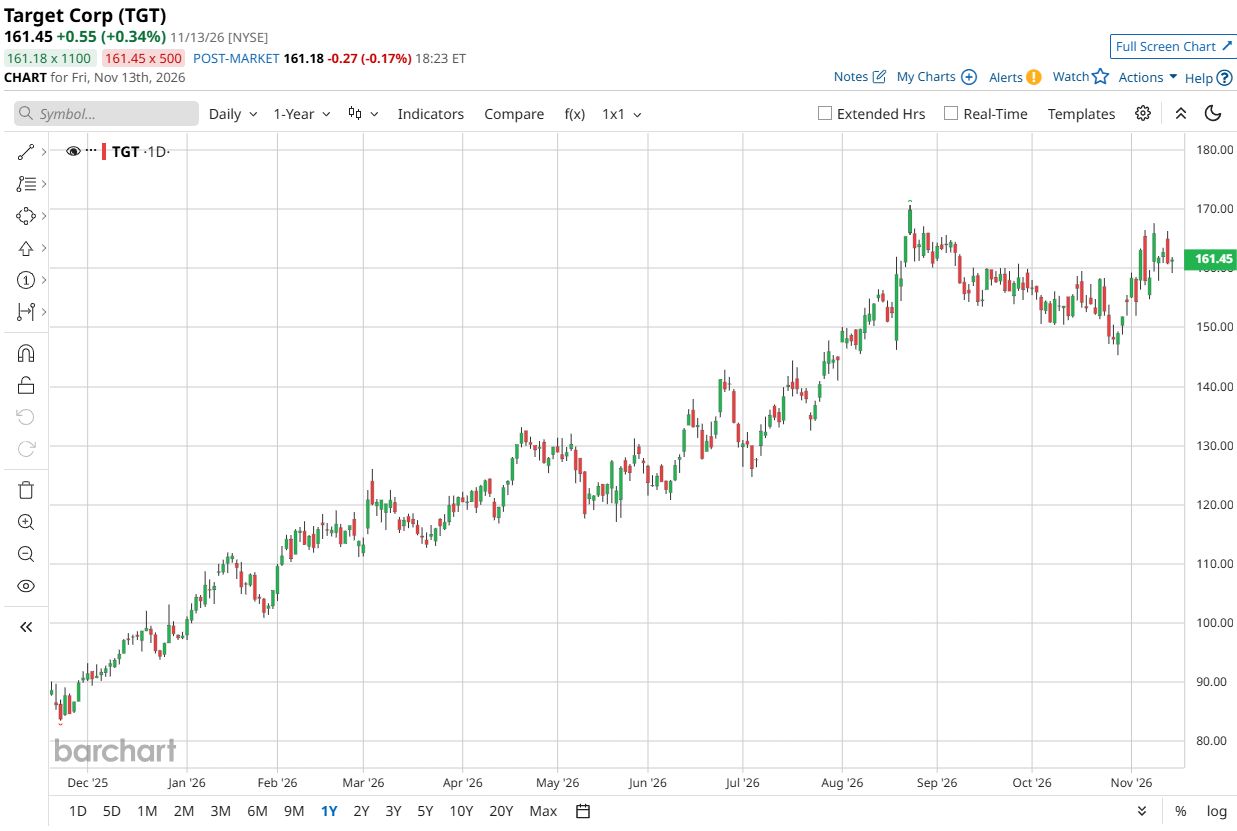
TGT stock has also delivered an impressive performance over the past year, gaining 78% in the last 52 weeks. Its year-to-date (YTD) advance stands at 64%, while shares have climbed 32% over the past six months, extending their upward momentum.
 www.barchart.com
On the valuation front, TGT stock is currently trading at 15.44 times forward-adjusted earnings and 0.66 times sales. Both multiples remain below their respective industry averages, suggesting that Target continues to trade at a discount relative to its industry peers.
Its dividend history is another notable feature, with 58 consecutive years of dividend increases. The retailer currently pays an annual dividend of $4.64 per share, yielding 2.87%. Its latest distribution of $1.16 per share is scheduled for Tuesday, Dec. 1, payable to shareholders of record as of Wednesday, Nov. 11.
Surpasses Q2 Earnings
On Aug. 19, Target reported its Q2 FY2026 financial results, sending its shares 4.3% higher during the session. The numbers pointed to improving demand, although the earnings picture requires some distinction between underlying operating progress and the one-time benefit associated with tariff refunds.
Net sales increased 5.3% year-over-year (YoY) to $26.5 billion, exceeding analyst expectations of $26.15 billion. Comparable sales climbed 3.8%, supported by 3.6% growth in customer traffic, while the average ticket remained flat. More frequent shopping visits, rather than higher prices or larger purchases, drove the improvement.
Physical stores recorded a 2.7% increase in comparable sales, while digital comparables climbed 8.7%, supported by more than 25% growth in same-day delivery. Merchandise sales advanced 5%, whereas non-merchandise sales rose 20.1%, reflecting stronger contributions from advertising, membership programs, and marketplace activities.
Profitability also improved as adjusted operating income rose 94.4% to $2.6 billion, while adjusted EPS increased 100.5% from the previous year’s period to $4.11. The latter comfortably exceeded analyst expectations of $2.34.
Following the results, management has raised its FY2026 sales-growth guidance to around 5% and its adjusted EPS outlook to $9.90–$10.90, including tariff refunds. Excluding those refunds, Target expects operating margin to be approximately 50 basis points above FY2025's 4.6%.
On the other hand, analysts expect Q3 FY2026 EPS to increase 14.6% YoY to $2.04. The full-year FY2026 estimate stands at $8.91, up 17.7% from the previous year, while the FY2027 forecast of $9.50 points to a growth of 6.6% from the previous year.
What Do Analysts Expect for TGT Stock?
Telsey Advisory Group analyst Joe Feldman maintains his “Buy” rating and $182 price target. Wells Fargo analyst Edward Kelly also reiterated his “Buy” recommendation, keeping his price target on the shares at $185.
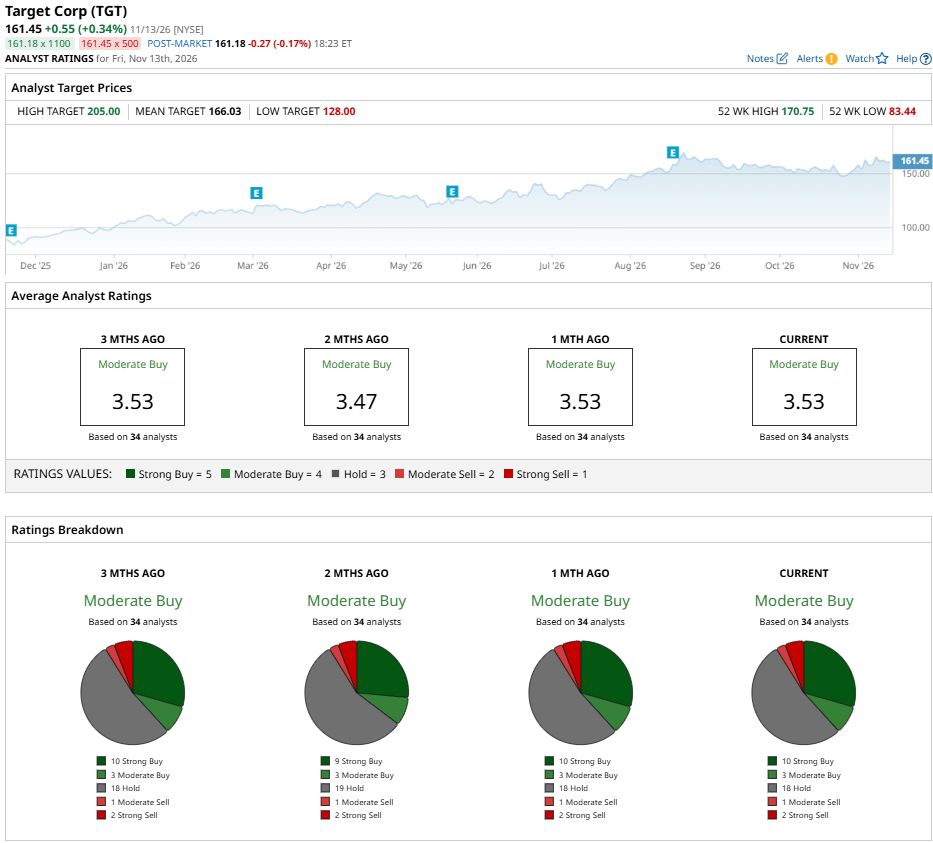
Across the analyst community, TGT stock carries an overall “Moderate Buy” rating. Of 34 analysts covering the stock, 10 recommend a “Strong Buy,” three assign a “Moderate Buy,” and 18 maintain a “Hold” rating. The remaining recommendations include one “Moderate Sell” and two “Strong Sell” ratings.
To that end, the average price target of $166.03 indicates a potential upside of 2.8%. Meanwhile, UBS analyst Michael Lasser has set a Street-high target of $205, suggesting potential gains of 27% from current levels.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Novo Nordisk vs. Amgen: 1 Has the Blockbuster Weight-Loss Drugs, the Other Has a Promising Rival Cathie Wood and Jim Cramer Disagree on Nvidia Stock Without Jensen Huang. Earnings Could Decide Who's Right A $1.3 Billion Reason to Buy Firefly Aerospace Stock Here Why at Least 1 Analyst Says Nvidia Stock Has Already Bottomed – Or Is Very Close