

Palo Alto Networks (PANW), a cybersecurity software subscription company, reported strong free cash flow (FCF) margins and guided to 38% this fiscal year. PANW stock rose 8% on this guidance on Thursday after rising ahead of the results. Could it be worth more?
PANW is at $364.77, up more than 7.0% midday on Thursday, Nov. 19, after rising 9.9% on Wednesday from a recent low of $309.29 on Nov. 17 ahead of the Nov. 18 fiscal Q1 2027 earnings release (ending Oct. 31) after the market closed.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
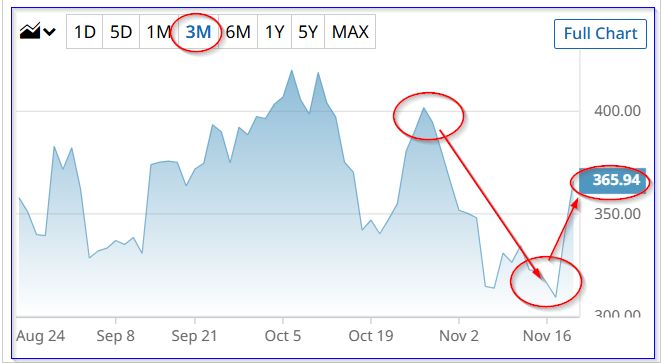 PANW stock - last 3 months - Barchart - Nov. 19, 2026
Moreover, analysts seem to be very positive on the stock. For example, Yahoo! Finance reports that the average price target (PT) of 54 analysts is $405.78, and Barchart's mean survey PT is $398.62. These PTs are only about 8% higher than Thursday's price (11/19).
So, is there much upside left in PANW?
FCF performance and high FCF Margin Guidance
Palo Alto Networks' fiscal Q1 revenue was up 39.25% YoY, and over the past year it rose 30.29%, according to Stock Analysis data.
Moreover, its adjusted free cash flow (FCF rose 13.1% to $1.937 billion YoY. However, its adj. FCF margin fell from 69.2% in Q1 last year to 59.6% in fiscal Q1 2027.
Nevertheless, on a trailing 12-month (TTM) basis (which is important since many of its clients renew subscriptions annually), the adj. FCF rose almost $1 billion from last year.
This can be seen on page 31 of its presentation deck. It shows that TTM adj. FCF rose from $3.75 billion last year to $4.638 billion in Q1 (+23.5%). It was even 5% higher than the Q4 TTM figure.
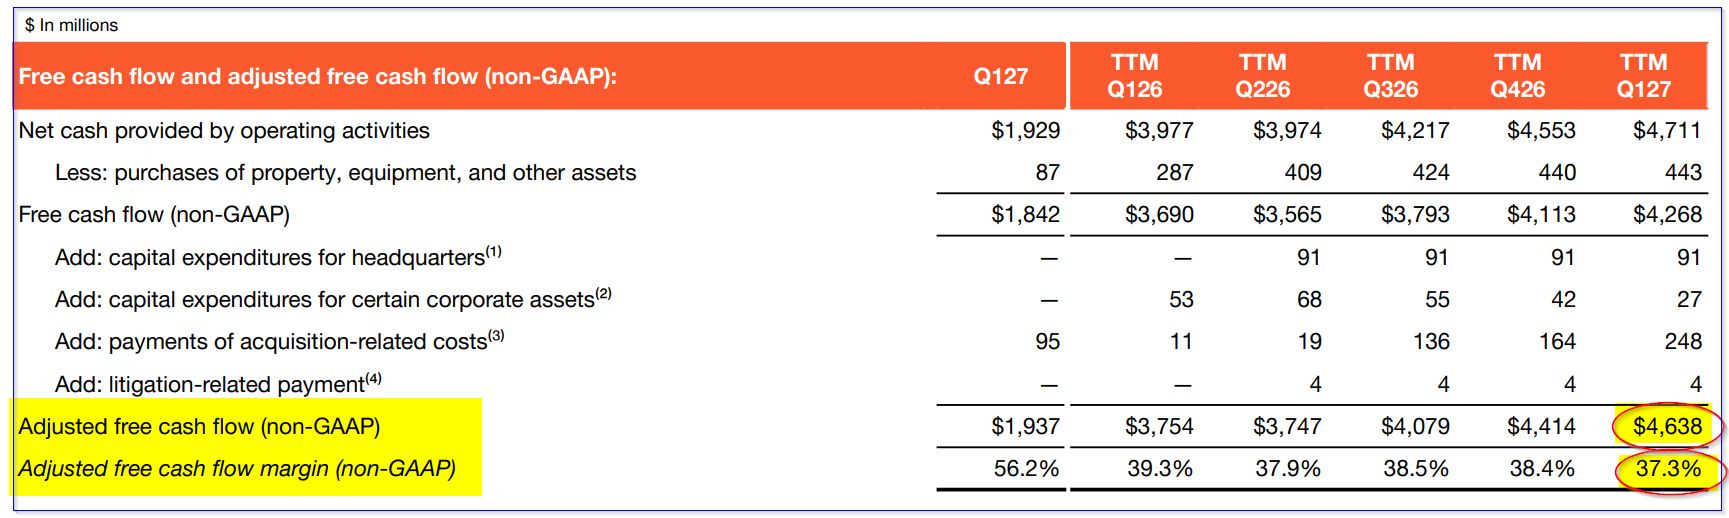 Palo Alto Networks - Adj. FCF trailing 12 months (TTM) - Q1 deck page 31 - Nov. 18, 2026
Note, however, that the TTM adj. FCF margin dipped slightly to 37.3% from 39.3% of revenue last year and even 38.4% in fiscal Q4.
However, management provided a 38.0% adj. FCF guidance for the year ending July 31, 2027. Let's see how that might work out.
Forecasting FCF and Price Targets
Management expects its revenue to be between $14.52 billion and $14.57 billion. That's even higher than prior analysts' average forecasts of $14.4 billion.
For the next year, these analysts forecast $16.47 billion in revenue. So, over the next 12 months (NTM), revenue could be about $15 billion:
$14.55b x 0.75 + $16.47b x 0.25 = $10.91b +$4.12b = $15.02 billion NTM revenue
So, applying a 38% margin, adj. FCF could hit $5.708 billion
That's over $1 billion higher than the $4.638 billion TTM figure shown above. In other words, its forecasted NTM adj. FCF could rise over 23%.
That certainly shows why the stock is up so much. But, how much is left?
For example, Palo Alto Networks' adj. FCF yield has averaged about 2.0% over the last year (i.e., a 50x multiple). So, applying this metric to its NTM adj. FCF forecast:
$5.708 / 0.02 = $285.4 billion fair value
That's only about 2.5% above its present market cap of $278.32 billion today. And that implies a PT of $372.30. That's lower than other analysts' targets, as I showed above.
Even with a slightly better 1.85% FCF yield (i.e., a 54x multiple), the stock is worth just $308.54 billion, or +10.9% higher. That gives it a NTM price target of $402.81.
Summary and Conclusion
Palo Alto Networks produced strong adj. FCF with lower quarterly margins, including slightly lower TTM adj. FCF as a percent of revenue (37.3%). As a result, with management's guidance of 38% margin this year and applying this to a next 12-month (NTM) revenue forecast, its adj. FCF could hit $5.7 billion.
With a generous 54x multiple, that only implies a 10.9% higher price target for Palo Alto Networks. Nevertheless, the stock could exceed this at any time.
But value investors have to take this into account when deciding whether its recent rise leaves any upside.
On the date of publication, Mark R. Hake, CFA did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Palo Alto Networks Stock Soars on Strong FCF Guidance - Any More Upside Left in PANW? 2 Stocks to Buy on a Potential U.S. Ban on Some Chinese Tech Synopsys Stock Just Scored a New Bullish Rating. Here's Why. Nasdaq Futures Plunge as AI Selloff Rolls On