

Washington is looking to put the brakes on another piece of Chinese tech. This time, optical transceivers are in the crosshairs. The Federal Communications Commission (FCC) is reportedly seeking to block imports of new models of Chinese-made optical transceivers, the high-speed components that help data travel through fiber-optic networks. The concern is potential national-security risks, with officials worried that Chinese networking equipment could expose U.S. data centers to data theft, malware, or even service disruptions.
Here’s where things get interesting for Wall Street. Chinese manufacturers currently control roughly two-thirds of the global optical transceiver market, with suppliers such as Innolight and Eoptolink serving major U.S. cloud companies. So, cutting off that supply won't exactly be a walk in the park. Replacing Chinese suppliers could take years, given the limited manufacturing capacity elsewhere.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
But that supply gap could create an opening for U.S. players like Lumentum (LITE) and Coherent (COHR). Wedbush analyst Matt Bryson believes both companies could pick up market share over the medium term while enjoying near-term pricing power as U.S. buyers look for alternative suppliers. Bryson sees the potential restrictions as a meaningful opportunity, even though neither company currently has the capacity to replace Chinese suppliers at scale.
So, could Washington’s latest tech crackdown turn into a business opportunity for these two optical networking players? Let’s take a closer look at why LITE stock and COHR stock could be wise buys now.
Stock #1: Lumentum (LITE)
Founded in 2015 and headquartered in San Jose, California, Lumentum has become an increasingly important player in the optical technology space, particularly as artificial intelligence (AI) infrastructure spending takes off. With a market capitalization of roughly $50 billion, the company develops the laser chips, photonic components, and high-speed optical transceivers that keep data moving across AI data centers, cloud networks, and fiber-optic systems.
The company's operations are divided into two segments. Cloud & Networking serves hyperscalers and network equipment manufacturers, while Industrial Tech supplies precision lasers for semiconductor, solar, display, and electric vehicle (EV) manufacturing applications.
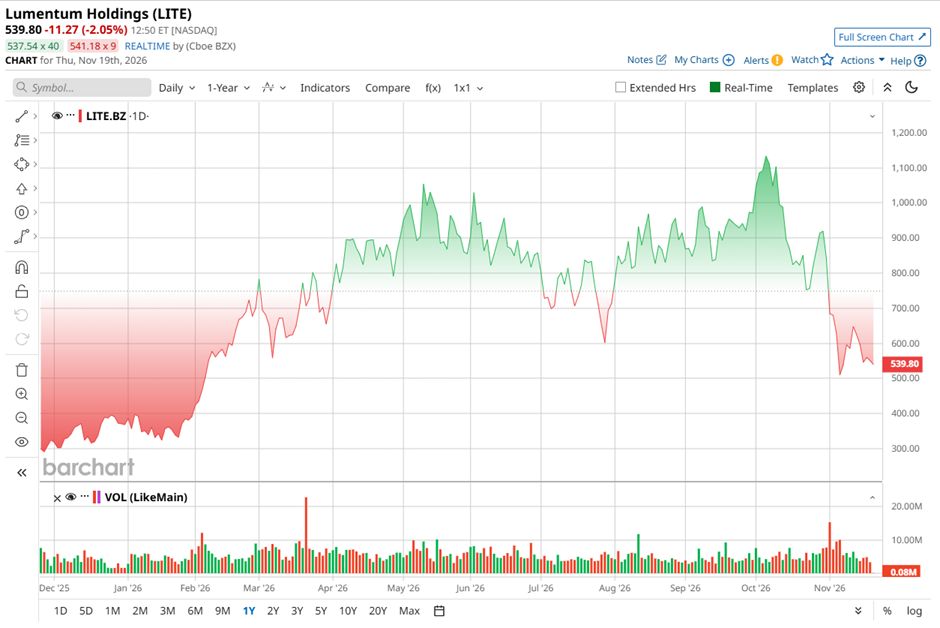
Investors have certainly taken notice. Lumentum’s shares have ridden the AI infrastructure wave, gaining 99% over the past 52 weeks and climbing more than 45% in 2026. At one point, shares reached an impressive $1,143 in October. However, the rally has since cooled considerably.
LITE stock has tumbled roughly 53% from that peak and shed about 36% over the past month. Concerns surrounding a proposed acquisition from Marvell Technology (MRVL), alongside a broader retreat from AI-related stocks, have weighed on sentiment. Still, even after this sharp pullback, Lumentum remains a significant market outperformer over the longer term, suggesting that investors have not entirely lost faith in its role in the next generation of AI networking.
 www.barchart.com
Lumentum is not exactly cheap, trading at around 28 times forward earnings, a premium to industry peers. However, the multiple remains below its own historical average. So, while investors are still paying up for its AI-driven growth prospects, the valuation is not as stretched as LITE stock’s past trading levels might suggest.
Lumentum’s latest numbers suggest that the AI infrastructure boom is translating into some serious business momentum. On Nov. 2, the company reported its Q1 fiscal 2027 results for the quarter ended Sept. 26, delivering growth across every business, with pump lasers and optical circuit switches (OCS) leading the charge. Revenue skyrocketed 137% year-over-year (YOY) to $1.3 billion, while non-GAAP EPS jumped to $4.57 from $1.10 a year earlier. Both figures comfortably topped Wall Street’s expectations.
Breaking down the performance, components remained the bigger revenue contributor, accounting for 59.7% of total revenue, or $754.2 million, up 99% annually. Systems delivered an even bigger leap, with revenue surging 229% YOY to $508.4 million, representing the remaining 40.3% of revenue. Beyond the headline numbers, management pointed to improving demand visibility for OCS, which it believes could develop into a multibillion-dollar annual revenue stream.
Looking ahead, management expects Q2 2027 revenue of $1.575 billion to $1.625 billion and non-GAAP EPS of $5.90 to $6.20.
Wall Street is equally upbeat, projecting current-quarter EPS of $4.86, up 292% YOY, alongside revenue of roughly $1.6 billion. For fiscal 2027, analysts forecast EPS growth of 145% to $19.93, followed by another 72% jump to $34.32 in fiscal 2028.
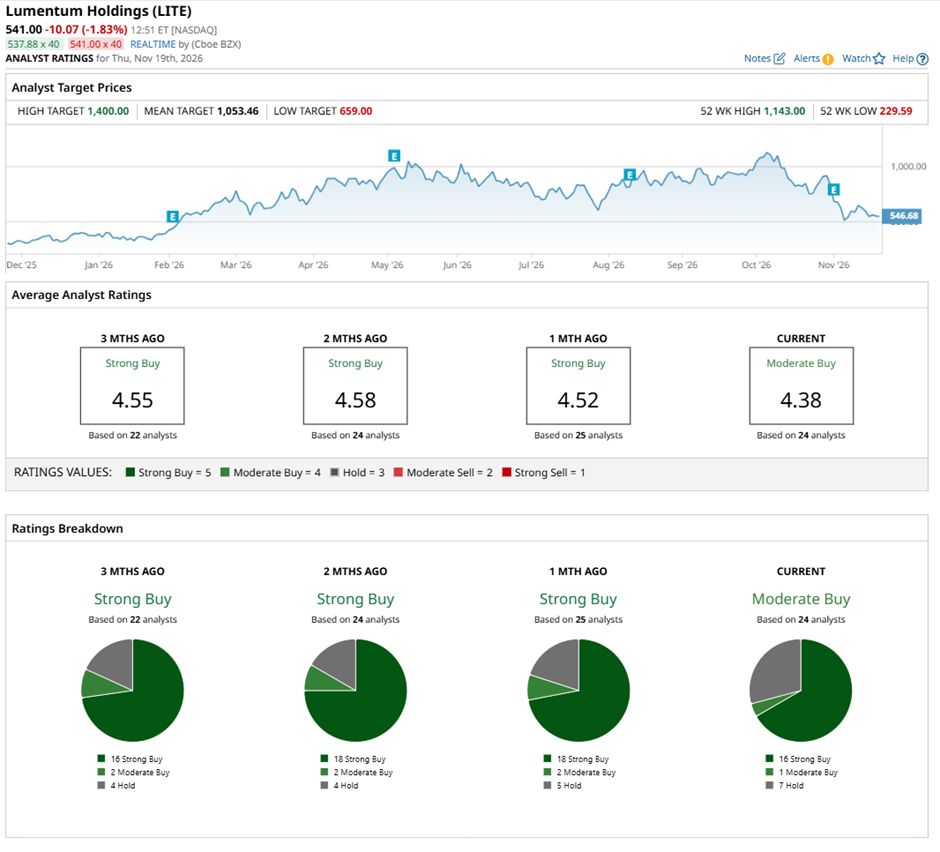
Wall Street remains broadly positive on Lumentum, with LITE stock carrying a consensus “Moderate Buy” rating. However, enthusiasm has cooled somewhat, as analysts have pulled back from their “Strong Buy” consensus just a month ago. Of the 24 analysts with coverage, 16 have a “Strong Buy,” one has a “Moderate Buy,” and seven analysts have a “Hold” rating.
The average price target of $1,053.46 represents potential upside of 97% from current levels. Moreover, the Street-high price target of $1,400 indicates that the stock could rise as much as 162%.
 www.barchart.com
Stock #2: Coherent (COHR)
Founded in 1971, Coherent has spent decades building the technology that helps move data, power machines, and keep modern industries running. Headquartered in Saxonburg, Pennsylvania, the company is a global photonics specialist, developing everything from optical communication products and lasers to engineered materials and optoelectronic components.
Its products serve a wide range of markets, including AI data centers, telecommunications, industrial manufacturing, and semiconductors. With operations spanning research, production, and distribution worldwide, Coherent has built a sizable presence in the global tech supply chain. It currently commands a market cap of approximately $41.9 billion.
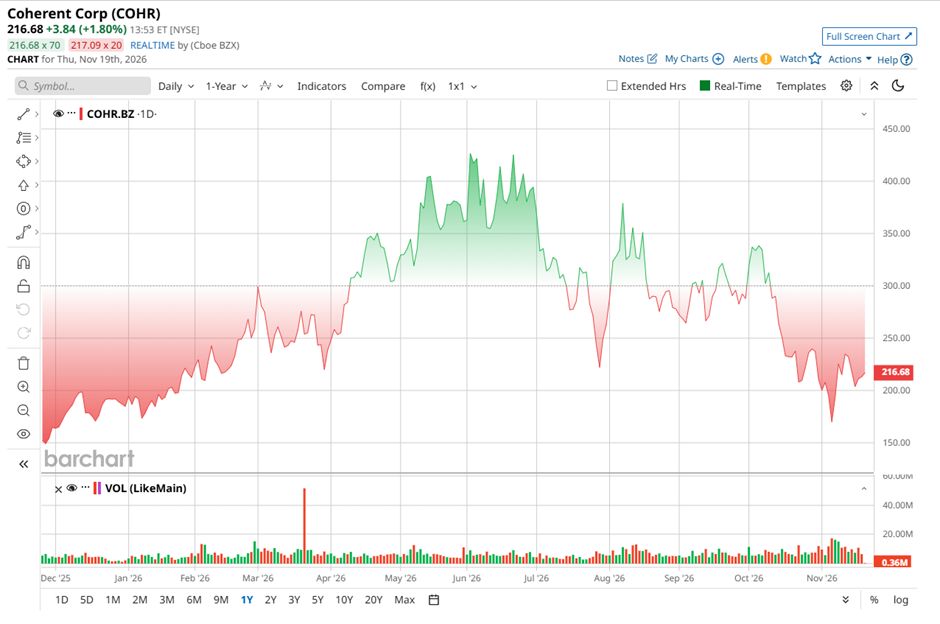
Investors have had plenty to cheer about over the past year, thanks largely to Coherent's growing exposure to AI data-center infrastructure and high-speed optical connectivity. COHR stock has surged 50% over the past 52 weeks and is up 16% in 2026. But that journey has not been particularly smooth lately.
After touching a 52-week high of $440 on June 3, COHR stock has surrendered half its value and slipped 25% over the past three months. Part of the pressure comes from investors reconsidering its expensive valuation and the amount of money needed to support future growth. Even a quarterly earnings beat could not fully calm the nerves. Following its Q1 fiscal 2027 report, shares came under pressure as concerns over heavy capital spending, negative free cash flow, and rising debt overshadowed better-than-expected revenue and earnings.
 www.barchart.com
Coherent is not handing investors a bargain, either. Shares are priced at 22.9 times forward earnings.
The latest earnings show just how much AI infrastructure is changing its business mix. Reported on Nov. 4, the results came in ahead of Wall Street’s expectations, with revenue jumping 50% YOY to $2.4 billion and adjusted EPS climbing 80% to $2.09.
The biggest engine was the Datacenter & Communications segment, which brought in $1.95 billion, up 79% YOY and accounting for roughly 82% of total revenue. Within that segment, data-center revenue surged 85% as demand for faster optical connections picked up. Even more impressive, scale-across revenue topped $200 million, nearly four times its year-ago level.
However, Industrial segment revenue slipped 15% YOY to $418.6 million as some applications remained weak. Still, the data-center business more than made up for the shortfall.
Management’s Q2 forecast suggests there is plenty more room to run. Coherent expects Q2 revenue of $2.55 billion to $2.75 billion, with the midpoint implying 12% sequential growth. Adjusted EPS is projected at $2.28 to $2.48.
Looking further ahead, management expects fiscal 2027 pro forma revenue to grow more than 60%. Coherent also sees quarterly revenue reaching $3 billion before fiscal 2027 wraps up and $4 billion sometime in fiscal 2028.
Meanwhile, analysts are optimistic, anticipating Q2 revenue of $2.65 billion. EPS for the quarter is expected to rise 93% YOY to $2.14. For fiscal 2027, analysts project EPS to climb 90% YOY to $9.18, then rise by another 57% to $14.39 in fiscal 2028.
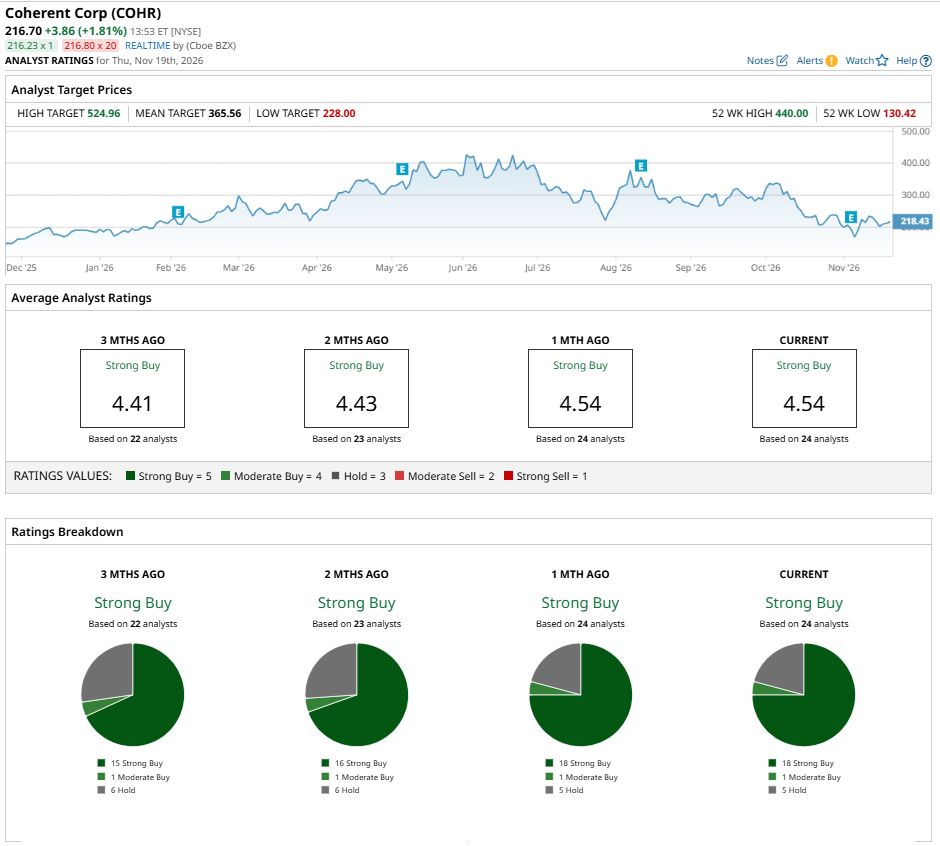
Overall, COHR stock has a consensus “Strong Buy” rating. Of the 24 analysts covering the stock, 18 advise a “Strong Buy,” one suggests a “Moderate Buy,” and the remaining five analysts have a “Hold” rating.
The average price target of $365.56 indicates potential upside of 24% from current levels, while the Street-high target of $524.96 suggests the stock could rally as much as 144% from here.
 www.barchart.com
On the date of publication, Sristi Suman Jayaswal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Palo Alto Networks Stock Soars on Strong FCF Guidance - Any More Upside Left in PANW? 2 Stocks to Buy on a Potential U.S. Ban on Some Chinese Tech Synopsys Stock Just Scored a New Bullish Rating. Here's Why. Nasdaq Futures Plunge as AI Selloff Rolls On