

Boot Barn Holdings, Inc.’s BOOT expanding digital business is becoming an important pillar of its broader growth strategy. Rather than treating online sales as a separate channel, the retailer uses its store network to fulfill orders, extend merchandise availability and create a seamless shopping experience. Buy-online-pickup-in-store and ship-to-store services also encourage customer visits while lowering fulfillment costs and improving merchandise margins.
The strategy delivered encouraging results in the first quarter of fiscal 2027. E-commerce same-store sales advanced 13.4% year over year, driven by double-digit growth at bootbarn.com. This digital performance outpaced the 3.8% increase in retail-store comps and helped lift consolidated same-store sales 4.7%.
Higher comparable sales and new-store contributions drove net sales up 17.7% to $593.5 million. Boot Barn opened 27 stores during the quarter, ending the period with 566 locations across 49 states. This expanding footprint provides additional fulfillment and pickup points, strengthening the connection between the company’s physical and digital channels.
Management expects online momentum to continue. Fiscal 2027 guidance calls for e-commerce same-store sales growth of 11-13%, compared with projected retail-store comp growth of 1-3%. Consolidated same-store sales are expected to increase 2-4%, while total sales are forecast to be between $2.58 billion and $2.63 billion, representing 14-16% growth.
Near-term trends still warrant attention. Preliminary July e-commerce comps moderated to 10.7%, while consolidated comps were approximately flat amid difficult comparisons and weaker event-related store traffic. The online channel maintained double-digit growth. Boot Barn’s expanding store base, store-based fulfillment capabilities and continued digital adoption should reinforce customer engagement and support comparable-sales growth, making omnichannel execution a meaningful competitive advantage for BOOT.
Boot Barn’s Price Performance, Valuation & Estimates
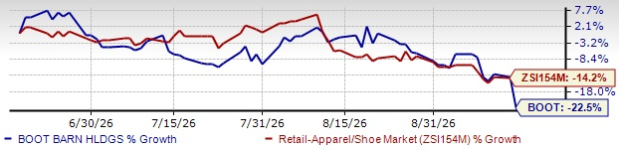
Shares of Boot Barn have lost 22.5% over the past three months compared with the industry’s 14.2% decline.
Image Source: Zacks Investment Research
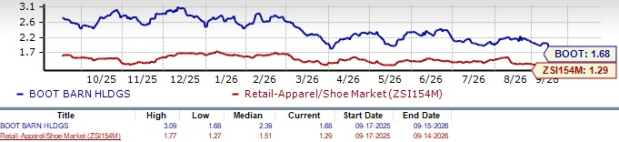
From a valuation standpoint, BOOT trades at a trailing price-to-sales ratio of 1.68, above the industry’s average of 1.29. It has a Value Score of A.
Image Source: Zacks Investment Research
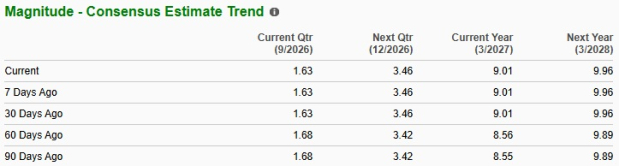
The Zacks Consensus Estimate for Boot Barn’s fiscal 2027 earnings implies year-over-year growth of 22.6%, while the same for fiscal 2028 indicates an uptick of 10.5%. Estimates for fiscal 2027 and 2028 have been revised upward by 5 cents and 7 cents, respectively, over the past 60 days.
Image Source: Zacks Investment Research
Boot Barn currently carries a Zacks Rank #2 (Buy).
Other Key Picks
Genesco Inc. GCO is a Nashville-based specialty retailer and branded company. It sells footwear and accessories through retail stores. The company flaunts a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Genesco’s current fiscal-year earnings indicates growth of 62.1% from the year-ago actuals. GCO delivered a trailing four-quarter average earnings surprise of 11.2%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2.
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
FIGS, Inc. FIGS is an apparel company focused on the healthcare industry. Its offerings include lab coats, jackets, footwear, bags, socks and other accessories used by healthcare professionals. The company carries a Zacks Rank #2 at present.
The Zacks Consensus Estimate for FIGS’ current financial-year earnings and sales suggests growth of 89.5% and 19.7%, respectively, from the year-ago actuals. FIGS delivered a trailing four-quarter average earnings surprise of 201.8%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Boot Barn Holdings, Inc. (BOOT): Free Stock Analysis Report
Genesco Inc. (GCO): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
FIGS, Inc. (FIGS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).