

CoreWeave, Inc. CRWV offers investors a sharp trade-off. AI demand is translating into a large contracted backlog and rapid revenue growth, while the shares trade below several forward sales benchmarks.
The question is whether that valuation gap is enough to offset a capital-intensive expansion model, rising financing needs and continuing losses, or whether waiting for clearer evidence of sustainable profitability makes more sense.
CoreWeave’s Backlog Supports an Unusual Growth Runway
Revenue backlog stood at $104.2 billion at June 30, 2026, up 246% year over year, and excluded more than $25 billion of net new commitments added in early third-quarter 2026. More than half of that backlog was already tied to contracts where delivery had begun.
Management raised 2026 revenue guidance to $12.4-$13.2 billion and lifted its year-end annualized run-rate revenue forecast to $18.5-$19.5 billion. Those targets give investors a measurable framework for judging whether new capacity is coming online fast enough to convert demand into revenues.
CRWV Valuation Offers a Lower Sales Multiple
CRWV trades at a forward 12-month price-to-sales ratio of 1.76, compared with 4.2 for the Zacks sub-industry, 5.95 for the sector and 4.63 for the S&P 500. That places the stock below each cited benchmark on this measure.
The lower multiple, however, sits beside an unusually capital-intensive model and negative earnings. Whether the valuation gap adequately compensates investors depends on future cash generation and the financing required to deliver contracted capacity.
CoreWeave Must Finance a Massive Capacity Buildout
CoreWeave ended the second quarter with $15.553 billion of total liquidity, including facility availability. In the first half of 2026, net cash used in investing activities reached $14.874 billion, while financing activities provided $13.985 billion. The company expects future infrastructure investment to use debt, equity, delayed-draw facilities, vendor financing and balance-sheet cash.
The industry backdrop shows why capital access matters. Microsoft Corporation MSFT reported $41 billion of fiscal fourth-quarter capital expenditures as Azure demand continued to exceed available capacity. Oracle Corporation ORCL said fiscal first-quarter 2027 cloud infrastructure revenues rose 121% to $7.4 billion, while free cash flow was negative $5 billion as it invested to support cloud growth.
CRWV Profitability Still Trails Its Revenue Expansion
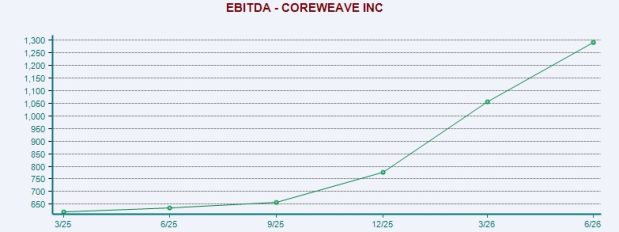
Adjusted EBITDA reached $1.51 billion in the second quarter, up from $753 million a year earlier, but adjusted EBITDA margin slipped to 59% from 62%. Net loss widened to $626 million from $290 million as interest expense and infrastructure costs weighed on results.
Image Source: Zacks Investment Research
CoreWeave Signals Point to a Wait-and-See Setup
CoreWeave has substantial evidence of demand and a lower forward sales ratio than the cited benchmarks, but its funding model and continuing losses leave important execution questions unresolved. Investors therefore have growth visibility and valuation support to weigh against financing and profitability risk.
CRWV currently carries a Zacks Rank #3 (Hold). It also has a VGM Score of F, a Value Score of D, a Growth Score of D and a Momentum Score of D. The #3 Rank lacks the stronger near-term signal associated with the top Zacks Ranks, while the D and F Style Scores are less favorable on value, growth and momentum characteristics. Together, those readings fit a wait-and-see setup while investors monitor backlog conversion, funding costs and earnings progress. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CoreWeave Inc. (CRWV): Free Stock Analysis Report
Microsoft Corporation (MSFT): Free Stock Analysis Report
Oracle Corporation (ORCL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).