

AstraZeneca’s AZN stock has taken a beating recently, with the company facing several pipeline setbacks in the past few months.
AZN’s Recent Pipeline Setbacks
In July, AstraZeneca announced the failure of a phase III study evaluating Wainua (eplontersen) in patients with transthyretin-mediated amyloid cardiomyopathy (ATTR-CM). The company is co-developing this drug in partnership with Ionis IONS. Wainua is already approved for the treatment of adults with polyneuropathy of hereditary transthyretin-mediated amyloidosis (ATTRv-PN). Success in the ATTR-CM indication was expected to significantly expand Wainua's commercial opportunity, as the ATTR-CM market is considerably larger than the ATTRv-PN market.
In July, a phase III study evaluating Ultomiris in adults and adolescents with thrombotic microangiopathy following hematopoietic stem cell transplant (HSCT-TMA) also failed to achieve statistical significance. In August, AstraZeneca discontinued the phase III eVOLVE-Lung02 study of experimental bispecific antibody volrustomig in non-small cell lung cancer (NSCLC).
In September, Etcamah, AstraZeneca’s next-generation oral selective estrogen receptor degrader (SERD), failed to achieve statistical significance in a phase III study evaluating the combination of Etcamah and palbociclib as an upfront first-line treatment in a broader population of patients with ER-positive/HER2-negative advanced breast cancer.
Etcamah (camizestrant) was approved in the United States in combination with a CDK4/6 inhibitor for treating HR-positive, HER2-negative advanced breast cancer earlier this month and for first-line advanced ER-positive, HER2-negative advanced breast cancer in the EU in July 2026.
AZN’s Pipeline Depth Provides Several Upcoming Catalysts
We believe that though AZN’s pipeline has hit a roadblock with the recent failures, it still boasts a deep late-stage pipeline of multi-blockbuster opportunities. AstraZeneca’s pipeline remains one of the broadest in the large-cap pharma space.
Key late-stage candidates in its oncology pipeline are volrustomig, sonesitatug vedotin, surovatamig and rilvegostomig.
Promising non-oncology pipeline candidates which are under regulatory review in some countries are tozorakimab for chronic obstructive pulmonary disease (COPD), efzimfotase alfa for hypophosphatasia, gefurulimab for generalized myasthenia gravis and anselamimab for severe light chain amyloidosis. Other key candidates in late-stage development are laroprovstat, a PCSK9 inhibitor for dyslipidaemia, elecoglipron, an oral GLP-1 receptor agonist for type II diabetes and obesity, eneboparatide for chronic hypoparathyroidism and cliramitug for ATTR-CM.
Ultomiris is under priority review in the United States for treating immunoglobulin A nephropathy (IgAN). Tezspire is being evaluated in phase III studies in eosinophilic esophagitis and COPD.
In July, AstraZeneca said that over the next 18 months, AstraZeneca expects more than 20 high-value readouts. Since that update, however, data from several important phase III programs have been released.
The remainder of 2026 and the first half of 2027 should remain very catalyst-heavy, particularly in oncology with several data readouts expected. The FDA is expected to decide on Ultomiris in IgANduring the fourth quarter, while tozorakimab's COPD decision is anticipated in the first quarter of 2027. Overall, we can say that the recent pipeline setbacks have not fundamentally weakened the breadth of AZN’s pipeline.
AZN’s Price Performance, Valuation and Estimates
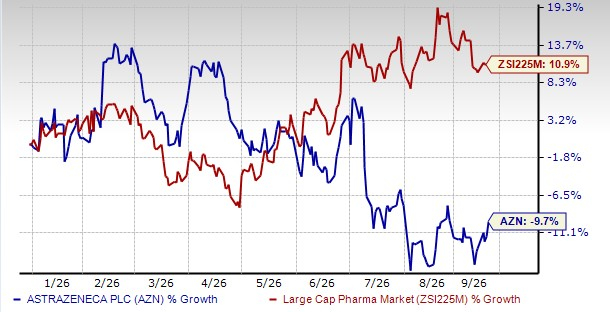
AZN stock has declined 9.7% so far this year against an increase of 10.9% for the industry.
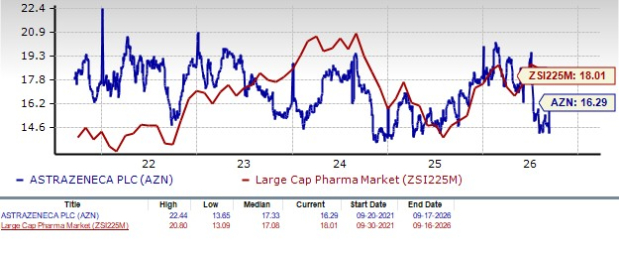
From a valuation standpoint, AstraZeneca is reasonably valued. Going by the price/earnings ratio, the company’s shares currently trade at 16.29 forward earnings, slightly lower than 18.01 for the industry. The stock is also trading lower than its 5-year mean of 17.33. The stock is also cheaper than other large drugmakers like Eli Lilly LLY, AbbVie, Merck, Gilead and J&J JNJ.
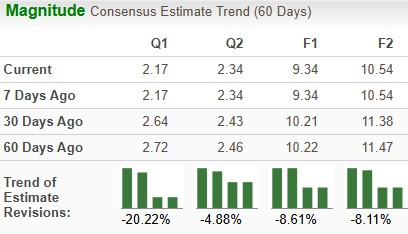
The Zacks Consensus Estimate for 2026 earnings has declined from $10.21 per share to $9.34 per share over the past 30 days. For 2027, earnings estimates have declined from $11.38 per share to $10.54 per share over the same timeframe.
AstraZeneca has a Zacks Rank #5 (Strong Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
AstraZeneca PLC (AZN): Free Stock Analysis Report
Johnson & Johnson (JNJ): Free Stock Analysis Report
Eli Lilly and Company (LLY): Free Stock Analysis Report
Ionis Pharmaceuticals, Inc. (IONS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).