

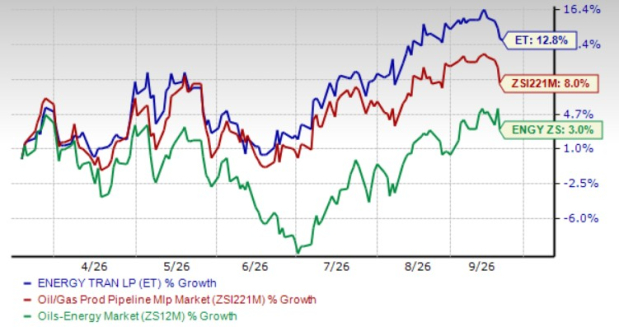
Units of Energy Transfer LP ET have rallied 12.8% in the past six months compared with the Zacks Oil and Gas - Production Pipeline - MLB industry’s growth of 8% and the Zacks Oil-Energy sector’s rise of 3%. This oil and gas midstream firm owns a wide network of pipelines across the United States and is pursuing opportunities to serve growing power loads from new demand centers across its network.
The midstream energy company benefits from the fee-based contract structure and increasing production volumes in the Permian Basin boost its cash flows. ET is also expanding its natural gas liquids (“NGL”) export infrastructure to meet growing global demand.
Price Performance (Six Months)
Image Source: Zacks Investment Research
Another company having extensive midstream operations in the United States is Kinder Morgan KMI. Kinder Morgan is poised to benefit from rising U.S. natural gas demand, supported by its extensive pipeline and storage assets serving key LNG export hubs along the Gulf Coast. In the past three months, KMI’s shares have plunged 4%, underperforming its industry and sector.
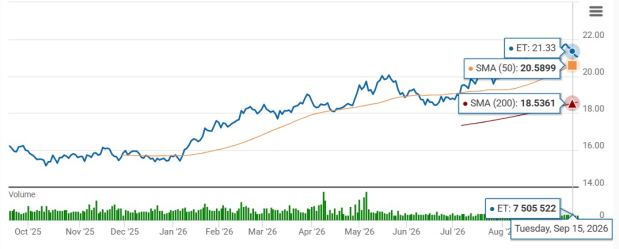
Energy Transfer’s units have been trading above both 50 and 200-day simple moving averages (SMAs), signaling a short-term bullish trend.
The 50 and 200-day SMAs are key indicators for traders and analysts to identify support and resistance levels. It is considered particularly important as this is the first marker of an uptrend or downtrend.
ET’s 50 Day and 200 Day SMA
Image Source: Zacks Investment Research
Another major player in the U.S. midstream space is Energy Transfer peer Plains All American Pipeline LP PAA. Similar to Energy Transfer, Plains All American relies heavily on fee-based contracts, which support relatively stable and predictable cash flows. Plains All American’s units are also trading above both 50 and 200-day SMAs, signaling a short-term bearish trend.
Should investors consider adding Energy Transfer to their portfolios after its share price gains? Examining the company’s underlying fundamentals can help assess whether ET offers a compelling entry point at current levels.
Key Drivers Supporting Energy Transfer’s Operational Growth
Energy Transfer operates one of the largest midstream infrastructure networks in the United States, spanning more than 140,000 miles of pipelines and related assets across 44 states. Its diversified portfolio includes crude oil and natural gas pipelines, gathering and processing facilities, and storage assets positioned across major producing regions and key demand centers. This extensive footprint supports diversified operations and relatively stable earnings.
The firm’s integrated network enables it to serve a broad customer base across multiple end markets. Energy Transfer also benefits from a largely fee-based business model, with nearly 90% of its revenues derived from transportation and storage services. This structure reduces exposure to fluctuations in commodity prices and supports more predictable cash flows and earnings.
Energy Transfer is positioned to capitalize on rising electricity demand from AI and cloud computing. The company has secured long-term agreements to supply natural gas for large-scale data center power generation. As grid constraints increase and coal-fired capacity declines, its expanding pipeline network should support reliable gas deliveries to power producers nationwide, creating additional avenues for long-term growth.
The firm continues to expand its operations through organic growth projects, strategic acquisitions and partnerships. Energy Transfer has more than 1.3 million barrels per day of NGL export capacity and is further enhancing its export capabilities through ongoing expansion projects at the Nederland terminals.
The firm has adopted a more disciplined capital allocation approach, focusing on balance sheet strength, high-return organic growth projects and returning excess cash to unitholders. Moderated capital spending and lower leverage have improved financial flexibility while allowing the partnership to maintain healthy distribution coverage.
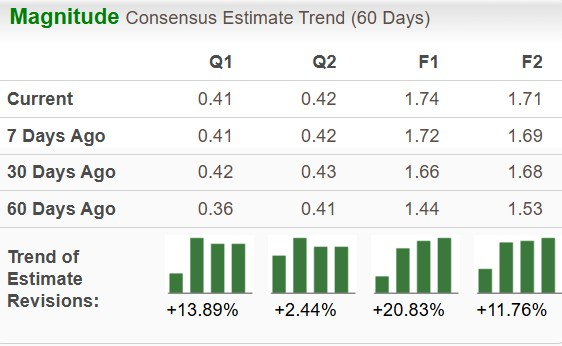
ET’s Earnings Estimates Moving North
The Zacks Consensus Estimate for Energy Transfer’s 2026 and 2027 earnings per unit (“EPU”) indicates increases of 20.83% and 11.76%, respectively, in the past 60 days.
Image Source: Zacks Investment Research
The same for Plains All American’s 2026 and 2027 EPU indicates an increase of 8.02% and 3.64%, respectively, in the past 60 days.
ET Shares More With Unitholders
The partnership’s current quarterly cash distribution is 34 cents per unit. Management has raised distribution rates 19 times in the past five years, and the current yield is 6.44%, better than its industry’s 5.25%.
Plains All American has raised cash distribution rates five times in the past five years. The current yield of PAA is 6.57%.
ET Stock’s ROE Is Lower Than the Industry
Return on equity (“ROE”) is a financial ratio that measures how well a company uses its shareholders’ equity to generate profits. The current ROE of the company indicates that it is using shareholders’ funds more efficiently than peers.
Energy Transfer’s trailing 12-month ROE is 11.55%, lower than the industry’s 14.22%.
Image Source: Zacks Investment Research
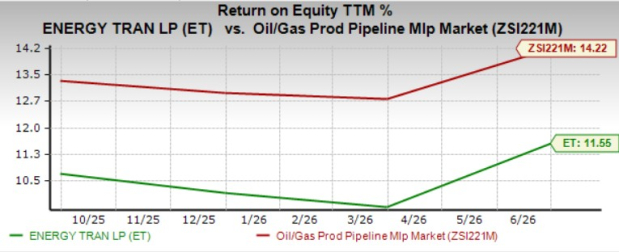
Kinder Morgan’s ROE is currently pegged at 10.46%, which is also lower than its industry level.
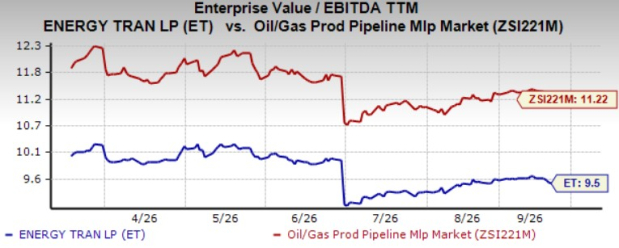
ET’s Units Are Trading at a Discount
ET’s current trailing 12-month Enterprise Value/Earnings before Interest Tax Depreciation and Amortization (EV/EBITDA) is 9.5X compared with the industry average of 11.22X. This indicates that the firm is presently undervalued compared with its industry.
Image Source: Zacks Investment Research
ET’s Net Profit Margin
Net margin measures the percentage of revenue retained as profit after deducting all expenses, taxes and interest. ET’s net margin is currently pegged at 4.87% compared with the industry’s 6.23%.
Wrapping Up
Energy Transfer’s extensive network of more than 140,000 miles of pipelines and related infrastructure positions the partnership to capitalize on sustained growth in U.S. oil, natural gas and NGL production. Its largely fee-based business model provides strong cash-flow visibility, supporting distributions, balance-sheet flexibility and continued investment in growth projects.
Improving earnings prospects, combined with an attractive valuation, further strengthen ET’s investment appeal and long-term return potential for unitholders. Existing investors may consider holding this Zacks Rank #3 (Hold) stock to continue benefiting from its consistent cash distributions. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
However, Energy Transfer’s return on equity and net margin currently remain below industry averages. Given these lower profitability metrics, prospective investors may prefer to wait for a more attractive entry point before initiating a position in ET.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Energy Transfer LP (ET): Free Stock Analysis Report
Plains All American Pipeline, L.P. (PAA): Free Stock Analysis Report
Kinder Morgan, Inc. (KMI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).