

lululemon athletica inc. LULU is trading at lower valuation levels as investors assess whether its long-term growth opportunities can offset weaker near-term operating trends. The stock currently carries a Zacks Rank #5 (Strong Sell), with a Value Score of B, Growth Score of B, Momentum Score of F and VGM Score of C. While valuation has become more attractive after the stock’s decline, investors are weighing slowing demand, lower earnings expectations and increased competition in the global athletic apparel market.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
LULU Balances Valuation and Competitive Pressure
LULU shares have declined as sales trends weakened across key markets. The stock trades at 10.5X forward 12-month earnings, below the Zacks sub-industry average of 14.4X, the sector average of 15.5X and the S&P 500 index average of 19.8X. The lower multiple reflects concerns around slower growth, margin pressure and uncertainty around the timing of a recovery.
The company operates in a highly competitive athletic apparel market where global brands continue to invest in product innovation, digital engagement and direct-to-consumer channels. NIKE Inc. NKE, with its broad athletic footwear and apparel portfolio, competes across many of the same consumer categories through its global brand presence, product launches and athlete-driven marketing. adidas AG ADDYY, meanwhile, remains a major global sportswear competitor with strength in lifestyle and performance categories, creating additional pressure on brands seeking consumer attention and market share.
Against this backdrop, lululemon’s second-quarter fiscal 2026 results highlighted the challenges facing the company. Revenue declined 4% year over year to $2.4 billion, while comparable sales decreased 9% and 10% on a constant-dollar basis. The Americas remained the largest area of weakness, with revenue down 8% and comparable sales down 12%.
lululemon athletica inc. Price, Consensus and EPS Surprise
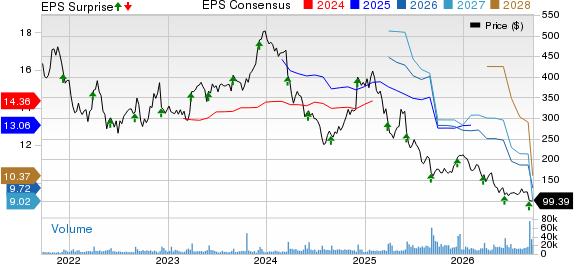
lululemon athletica inc. price-consensus-eps-surprise-chart | lululemon athletica inc. Quote
lululemon Builds Recovery Through Product Innovation
lululemon is attempting to improve product relevance through faster inventory decisions, updated core franchises and a broader assortment strategy. Management’s recovery plan focuses on product creation, product activation and enterprise efficiency, with the goal of improving full-price sales trends.
The company said it is chasing approximately 20% more volume this year compared with last year, allowing it to respond faster to customer demand. Product performance, however, remains uneven. Management highlighted stronger demand for newer away-from-body women’s bottoms, including Groove Wide-Leg, Align Foldover Jogger, Breezily and updated Dance Studio Pant. At the same time, leggings sales declined approximately 20% in the second quarter as consumer preferences shifted toward looser silhouettes.
Nike and adidas have also emphasized product innovation as a way to maintain consumer engagement, particularly as athletic apparel demand becomes increasingly influenced by lifestyle trends, performance features and brand identity. For lululemon, strengthening its product pipeline remains important as it works to defend its core categories while expanding beyond traditional yoga-inspired apparel.
LULU Maintains Financial Flexibility Amid Slower Demand
lululemon’s balance sheet provides resources to support investments during the current slowdown. The company ended the second quarter of fiscal 2026 with $1.4 billion in cash and cash equivalents and $593.7 million of available capacity under its revolving credit facility. Inventory totaled $1.7 billion, down 1% year over year, while inventory units declined 7%.
Cash generation has remained supportive. The company generated $589.3 million in operating cash flow during the first two quarters of fiscal 2026 compared with $209.7 million in the prior-year period. lululemon also repurchased 2.7 million shares for $330 million during the quarter.
The company continues to invest in stores, digital capabilities and brand-building initiatives. As of Aug. 2, 2026, lululemon operated 825 company-operated stores globally, expanding its retail footprint despite softer demand trends.
lululemon’s Earnings Outlook Remains Uncertain
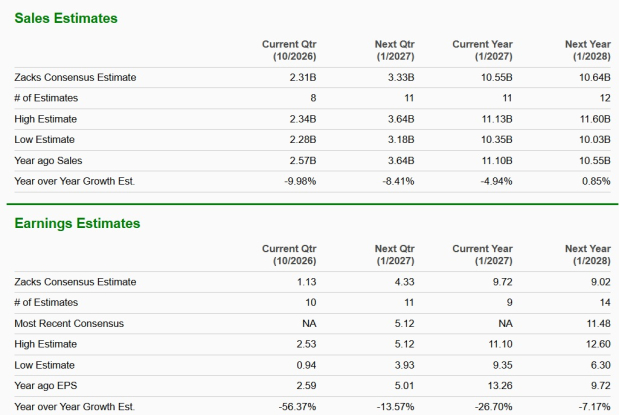
Management lowered its fiscal 2026 outlook as demand trends weakened. The company now expects revenue of $10.35 billion to $10.50 billion, representing a decline of 5% to 7%, while earnings per share are projected at $9.48 to $9.73.
For the third quarter of fiscal 2026, lululemon expects revenue of $2.29 billion to $2.32 billion, representing a decline of 10% to 11%. Earnings per share are expected at 93 cents to 98 cents compared with $2.59 in the prior-year quarter.
Image Source: Zacks Investment Research
Profitability remains under pressure from weaker sales leverage, higher marketing investments and markdown activity. Second-quarter operating income declined 13% to $453.7 million, while operating margin decreased to 18.8%. The quarter benefited from $134.5 million in tariff refunds, which increased gross margin by 560 basis points and contributed $0.86 per share after tax.
LULU Signals Need Broader Context
LULU’s Zacks Rank and Zacks Style Scores provide additional context alongside valuation and operating trends. Zacks Style Scores evaluate characteristics such as value, growth, momentum and combined style factors as complementary indicators to the Zacks Rank.
The stock’s Value Score of B reflects relatively lower valuation metrics, while its Growth Score of B reflects longer-term growth characteristics. The Momentum Score of F indicates weaker recent price momentum, and the VGM Score of C combines these factors into a broader style measure.
Investors evaluating LULU are balancing a lower valuation against slowing sales, competitive pressures and uncertainty around the recovery timeline. Product innovation, international expansion and financial flexibility remain important factors, while execution against the company’s strategy will determine whether operating trends improve over time.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
lululemon athletica inc. (LULU): Free Stock Analysis Report
NIKE, Inc. (NKE): Free Stock Analysis Report
Adidas AG (ADDYY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).