

CAVA Group, Inc. CAVA continues to generate strong cash flow while investing in restaurant expansion and initiatives designed to enhance the guest experience. Through the second quarter of 2026, the company generated $44.8 million in free cash flow, while cash flow from operations increased to $134.5 million from $98.9 million in the comparable prior-year period. Management expects full-year free cash flow to remain strong, although the second half is expected to be less seasonally favorable and include additional capital investments.
The second half is expected to include additional investment as CAVA builds its pipeline for 2027 restaurant openings. Management noted that the remaining quarters are less seasonally favorable and typically generate lower free cash flow. In addition to development-related spending, the company expects to invest approximately $5 million-$10 million in opportunities to enhance existing restaurants and improve the guest experience. These investments are expected to include refreshes related to aspects of Project Soul and potential grill expansions.
CAVA also retains substantial liquidity as it continues to invest for growth. At the end of the second quarter, CAVA had $435.6 million in cash and investments, compared with $393 million as of the 2025 end. The company reported no debt and retained access to a $150 million undrawn revolver.
CAVA’s strong first-half cash generation provides a solid foundation for continued investment in restaurant growth and existing locations. However, less favorable seasonality and additional CapEx in the second half could moderate cash generation. With management expecting full-year free cash flow to remain strong, the pace of investment and cash generation will likely remain key considerations through the remainder of 2026.
CAVA’s Price Performance, Valuation & Estimates
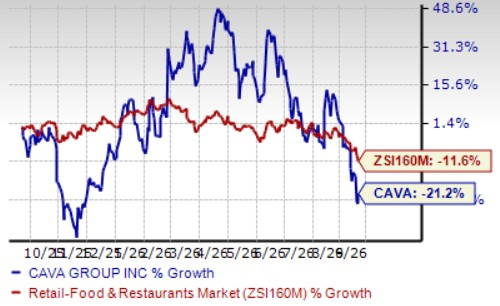
CAVA’s shares have declined 21.2% in the past year compared with the industry’s fall of 11.6%. In the same time frame, other industry players like Dutch Bros Inc. BROS and McDonald's Corporation MCD have declined 27.8% and 18.1%, respectively.
CAVA’s One-Year Price Performance
Image Source: Zacks Investment Research
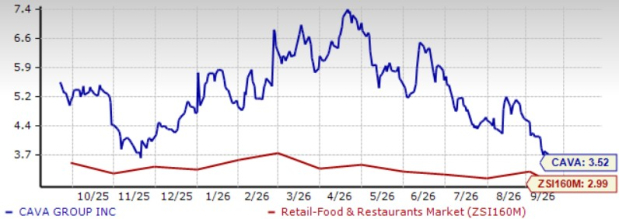
From a valuation standpoint, CAVA trades at a forward price-to-sales (P/S) multiple of 3.52, above the industry’s average of 2.99. Conversely, industry players, such as Dutch Bros and McDonald's, have P/S multiples of 2.78 and 6.01, respectively.
CAVA’s P/S Ratio (Forward 12-Month) vs. Industry
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for CAVA’s 2026 earnings per share has increased in the past 30 days.
EPS Trend of CAVA Stock
Image Source: Zacks Investment Research
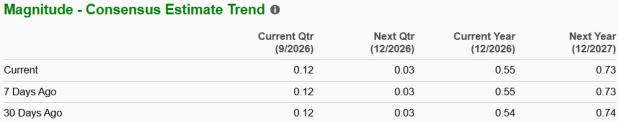
The company’s earnings in 2026 are likely to increase 1.9% on a year-over-year basis. Conversely, industry players such as McDonald’s and Dutch Bros are likely to witness an increase of 5.6% and 27.6%, respectively, year-over-year in 2026 earnings.
CAVA’s Zacks Rank
CAVA stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CAVA Group, Inc. (CAVA): Free Stock Analysis Report
McDonald's Corporation (MCD): Free Stock Analysis Report
Dutch Bros Inc. (BROS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).